Tag: #Acts

  • Container Manufacturing Assistance Scheme: Building India’s Maritime Future

    Container Manufacturing Assistance Scheme: Building India’s Maritime Future

    Date: 18.08.2026

    India is accelerating its maritime ambitions with the Container Manufacturing Assistance Scheme (CMAS), a transformative initiative designed to establish a robust domestic container manufacturing ecosystem. This article provides a comprehensive overview of CMAS, its strategic importance, recent milestones, and the broader reforms shaping India’s maritime sector, with direct links to official sources and references.

    The Need for Domestic Container Manufacturing

    Maritime transport is the backbone of global trade, with about 80% of merchandise trade by volume carried by sea (UNCTAD Review of Maritime Transport). Containerized cargo accounts for nearly two-thirds of the value of international trade, making efficient container logistics critical for supply chains. Recent disruptions and geopolitical tensions have exposed vulnerabilities in global shipping, prompting countries like India to focus on domestic manufacturing of critical logistics assets such as shipping containers.

    India currently imports nearly 2 million empty containers annually, making it susceptible to global market fluctuations and supply-chain disruptions. The CMAS aims to reduce this dependence, strengthen supply-chain resilience, and support India’s long-term trade ambitions. The scheme complements initiatives like Make in India, Maritime Amrit Kaal Vision 2047, and multimodal logistics development.

    What is the Container Manufacturing Assistance Scheme (CMAS)?

    Announced in the Union Budget 2026–27, CMAS is a targeted initiative with a β‚Ή10,000 crore outlay over five years. Its objectives include:

    • Establishing new Greenfield manufacturing facilities
    • Expanding existing Brownfield units
    • Providing operational support to enhance competitiveness
    • Supporting testing infrastructure, skilling, and capacity building

    The scheme targets an annual domestic manufacturing capacity of up to 7.5 lakh Twenty-foot Equivalent Units (TEUs)β€”about ten times the current capacity. This is expected to create a market opportunity of nearly β‚Ή80,000 lakh crore and position India as a reliable global supplier of shipping containers.

    For more details, see the Ministry of Ports, Shipping and Waterways official document.

    Building an Integrated Maritime Ecosystem

    CMAS is part of a broader strategy to create an integrated, domestically anchored container ecosystem. In February 2026, the Ministry of Ports, Shipping and Waterways signed an MoU to establish the Bharat Container Shipping Line (BCSL), bringing together major public sector stakeholders. The initiative includes investments of around β‚Ή99,149 crore in fleet development and domestic container procurement.

    This approach complements other government initiatives:

    • PM Gati Shakti: Enhancing connectivity between ports, railways, highways, and industrial centers
    • National Logistics Policy: Supporting operational efficiency
    • Sagarmala Programme: Promoting port-led development

    These efforts collectively support a resilient logistics network for India’s growing trade volumes.

    Employment and Industrial Growth

    CMAS is expected to generate around 3,000 direct jobs and over 50,000 indirect jobs in container manufacturing and allied industries. The scheme will also stimulate growth in ancillary sectors such as corner castings, wooden frames, and Corten steel production.

    Recent Progress and Industry Response

    A major milestone was achieved in July 2026 with the rollout of India’s first domestically manufactured EXIM shipping container for A.P. Moller–Maersk. Manufactured to international ISO and CSC standards, this container is suitable for global deployment. Maersk’s subsequent order for 1,000 additional Made-in-India containers with DCM Shriram Group signals growing confidence in India’s manufacturing capabilities. For more, see the DG Shipping address.

    Part of Wider Maritime Transformation

    CMAS is complemented by a series of legislative, institutional, and infrastructure reforms:

    • Merchant Shipping Act, 2025; Coastal Shipping Act, 2025; Indian Ports Act, 2025: Modernizing the legal framework for shipping and port governance
    • Digital Initiatives: One Nation One Port Process (ONOP), Maritime Single Window, and e-Samudra to streamline regulatory procedures (PIB Press Release)
    • Shipbuilding Financial Assistance Package: A β‚Ή70,000 crore package to boost domestic shipbuilding
    • Major Infrastructure Projects: Vadhavan Port, International Container Transshipment Port at Galathea Bay, Tuna Tekra Container Terminal, and Outer Harbour Container Terminal at V.O. Chidambaranar Port

    Way Forward

    The Container Manufacturing Assistance Scheme is a pivotal step in building a globally competitive maritime manufacturing ecosystem. By fostering domestic container production, reducing import dependence, and supporting broader maritime reforms, CMAS is set to enhance India’s supply-chain resilience, generate employment, and position the country as a leading maritime and logistics hub.

    References:

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Authenticity of Country of Origin Certificates, Preferential Duty Exemption, and Customs Valuation Dispute

    Authenticity of Country of Origin Certificates, Preferential Duty Exemption, and Customs Valuation Dispute

    Date: 18.08.2026

    The Customs, Excise & Service Tax Appellate Tribunal (CESTAT) Allahabad recently delivered a significant judgment in the case of M/s SSN Steel Impex, a New Delhi-based importer and trader of stainless steel products. The case revolved around the denial of preferential customs duty benefits, allegations of unauthentic Country of Origin (COO) certificates, undervaluation of goods, and imposition of penalties. This article provides a detailed analysis of the case, the Tribunal’s findings, and its broader implications for importers and customs administration in India.

    Background of the Case

    M/s SSN Steel Impex imported stainless steel cold rolled sheets, coils, and circles, primarily from Malaysia, to avail preferential duty benefits under Notification No. 46/2011-Cus (ASEAN-India Free Trade Agreement). The customs authorities alleged that many COO certificates submitted by the appellant were unauthentic, leading to the denial of duty exemption and the imposition of differential duty, interest, and penalties. The appellant challenged these actions, arguing that due process was not followed and that most COOs were genuine.

    Key Issues Examined

    1. Authenticity of COO Certificates
      • Customs authorities, based on communications from Malaysia’s MITI, claimed that 87 out of 143 COOs were unauthentic.
      • SSN Steel Impex submitted 38 COOs; only one was found unauthentic, for which the company had already paid the differential duty.
      • The Tribunal found that the remaining 37 COOs were not listed as unauthentic and thus should be accepted.
    2. Eligibility for Preferential Duty
      • The Tribunal held that since the majority of COOs were authentic and verified at the time of import, the appellant was eligible for duty exemption under Notification No. 46/2011-Cus.
      • The Tribunal emphasized that subsequent communications from MITI could not retroactively invalidate COOs that were valid and verified at the time of import.
    3. Allegations of Undervaluation
      • Customs authorities alleged undervaluation based on statements from third parties and price comparisons.
      • The Tribunal found no evidence that SSN Steel Impex paid amounts over and above the declared invoice prices or that the declared values were not at arm’s length.
      • The Tribunal relied on Supreme Court precedents, holding that transaction values could not be rejected without concrete evidence.
    4. Imposition of Penalties
      • Penalties were imposed for alleged mis-declaration and undervaluation.
      • The Tribunal found no evidence of intent to evade duty or collusion and set aside all penalties.

    Tribunal’s Final Order

    The CESTAT Allahabad ruled in favor of SSN Steel Impex, with the following key directives:

    • All 37 COOs (except the one already settled) were deemed authentic and acceptable.
    • The appellant was entitled to the benefit of duty exemption for all consignments covered by these COOs.
    • The declared transaction values were accepted; the enhanced values determined by customs were set aside.
    • All penalties imposed on the appellant were quashed.

    Legal Precedents and Principles Affirmed

    • Due Process: The Tribunal reiterated the importance of natural justice, including the right to cross-examination and proper consideration of evidence.
    • Finality of Assessment: Once goods are assessed and cleared based on valid documents, subsequent doubts cannot retroactively deny benefits unless clear evidence emerges.
    • Burden of Proof: The onus is on customs authorities to provide concrete evidence for allegations of mis-declaration or undervaluation.

    Implications for Importers and Customs Administration

    1. Reliance on Valid COOs: Importers can rely on COOs issued and verified by competent authorities at the time of import, unless there is clear evidence of fraud or forgery.
    2. Protection Against Retroactive Actions: Subsequent communications or doubts from foreign authorities cannot, by themselves, invalidate benefits already granted unless accompanied by formal revocation or evidence.
    3. Importance of Documentation: Importers should maintain comprehensive records of all import documents, including COOs, invoices, and customs clearances.
    4. Customs’ Investigative Standards: Customs authorities must adhere to due process and provide substantive evidence before denying benefits or imposing penalties.

    Conclusion

    The CESTAT Allahabad’s decision in the SSN Steel Impex case sets a strong precedent for the protection of importers’ rights and the importance of procedural fairness in customs adjudication. It underscores the need for robust evidence and adherence to natural justice before denying statutory benefits or imposing penalties. This ruling will likely influence future disputes involving preferential duty claims and the authenticity of COO certificates in India.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Supreme Court Clarifies Extended Limitation in Excise Valuation for Motor Vehicle Body Building

    Supreme Court Clarifies Extended Limitation in Excise Valuation for Motor Vehicle Body Building

    Date: 18.08.2026

    The Supreme Court of India recently delivered a significant judgment in the case of Audi Automobiles & Ors. vs. Commissioner of Central Excise and Service Tax, Indore, addressing the applicability of the extended period of limitation under Section 11A of the Central Excise Act, 1944, in disputes involving the valuation and assessment of motor vehicle chassis and body-building services.

    Background of the Case

    Audi Automobiles and other appellants are engaged in the business of body building for motor vehicles on a job work basis. Manufacturers supply them with chassis, on which the body is built. The excise duty on the chassis is paid by the manufacturer at 110% of the cost of manufacture, as per Rule 8 of the Central Excise Valuation Rules, 2000. Once the body is built, the completed vehicle is returned to the manufacturer, and excise duty is computed by the job worker on the total value, including the cost of raw materials, job work charges, and profit.

    A dispute arose regarding whether the 10% profit margin (included in the 110% valuation of the chassis) should also be included in the assessable value when the job worker clears the completed vehicle. The Department issued a Show Cause Notice (SCN) demanding duty for the period 01.11.2004 to 31.03.2007, invoking the extended limitation period under Section 11A.

    Key Legal Issues

    1. Valuation of Completed Motor Vehicles
      • The core issue was whether the 10% profit margin, already included in the chassis valuation, should be added again when computing the assessable value of the completed vehicle.
      • The Supreme Court referred to earlier landmark decisions (such as Ujagar Prints and Eicher Motors) and clarified that the value of the completed vehicle must include the full value of the chassis (including the 10% margin), the cost of raw materials, job work charges, and the job worker’s profit. However, profits made by the manufacturer after receiving the completed vehicle are not to be included.
    2. Applicability of Extended Limitation under Section 11A
      • The Department sought to invoke the extended limitation period, alleging suppression of facts by the assessee.
      • The Court emphasized that for the extended period to apply, there must be a wilful suppression or misstatement with intent to evade duty. Mere omission or non-inclusion, when facts are known to both parties, does not amount to suppression.
      • In this case, since the Department was aware of the valuation method and the 10% margin, the invocation of the extended limitation was not justified.

    Supreme Court’s Decision

    • The Supreme Court set aside the orders of the Tribunal and lower authorities, holding that the demand raised by the Department was time-barred as the SCN was issued beyond the one-year limitation period.
    • The Court reaffirmed that the assessee’s liability to include the entire cost price (including the 10% margin) in the assessable value is correct, but the demand for the subject period could not be sustained due to limitation.

    Implications of the Judgment

    1. Clarity on Valuation: The judgment provides clear guidance on how to compute the assessable value for motor vehicles built on job work basis, ensuring that the 10% profit margin included in the chassis valuation is not omitted.
    2. Limitation Safeguards: The decision reinforces the principle that the extended limitation period under Section 11A can only be invoked in cases of wilful suppression or fraud, protecting assessees from arbitrary and delayed demands.
    3. Precedent for Similar Cases: This ruling will serve as a precedent for future disputes involving valuation and limitation in excise matters, especially in job work scenarios.

    Conclusion

    The Supreme Court’s judgment in the Audi Automobiles case brings much-needed clarity to the valuation of motor vehicles in body-building job work and sets strict standards for invoking the extended limitation period under the Central Excise Act. This ensures fairness and legal certainty for both the industry and the tax authorities.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Delhi HC Affirms Importers’ Right to Refund of Excess Customs Duty Paid Without Assessment Order u/s 27 of Customs Act

    Delhi HC Affirms Importers’ Right to Refund of Excess Customs Duty Paid Without Assessment Order u/s 27 of Customs Act

    Date: 17.08.2026

    Aman Medical Products Ltd. found itself in a legal dispute after inadvertently paying a higher customs duty on imported goods. The company failed to claim a concessional rate available under Notification No. 6/2002 dated 1.3.2002 due to ignorance and paid the excess duty while filing the Bill of Entry. The central question was whether an importer who pays excess duty by mistake, without an assessment order or contest, can claim a refund under Section 27 of the Customs Act, 1962.

    Legal Issue

    The Customs, Excise and Service Tax Appellate Tribunal (CESTAT) had previously ruled that a refund could only be claimed if the excess duty was paid “in pursuance to an order of assessment.” According to CESTAT, without an assessment order, the importer could not seek a refund unless an appeal was filed against such an order.

    High Court’s Analysis

    The Delhi High Court, presided over by Justices A.K. Sikri and Valmiki J. Mehta, examined Section 27 of the Customs Act, 1962. The Court highlighted two key points:

    1. Alternative Grounds for Refund: Section 27(1) allows a refund claim for duty “paid by him in pursuance of an order of assessment” or “borne by him.” The use of “or” means these are alternative grounds. Thus, a refund can be claimed even if the duty was not paid under an assessment order.
    2. No Assessment Order Required: The Court clarified that if duty is paid without an assessment orderβ€”such as in cases of ignorance or inadvertenceβ€”the importer is still entitled to claim a refund under Section 27(1)(ii).

    The Court distinguished this case from earlier Supreme Court judgments (CCE, Kanpur v. Flock (India) Pvt. Ltd. and Priya Blue Industries Ltd. v. Commissioner of Customs), noting that those cases involved a formal assessment order and a failure to appeal, which was not the situation here.

    Judgment and Outcome

    The High Court set aside the CESTAT’s order and upheld the order of the Commissioner of Customs (Appeal). The matter was remanded to the Deputy Commissioner of Customs (Refund) to examine the merits of Aman Medical Products Ltd.’s refund claim. The Court confirmed that the company’s claim was maintainable under Section 27 of the Customs Act, even without an assessment order or a prior appeal.

    Key Takeaways

    1. Importers’ Rights: Importers who pay excess customs duty by mistake, without an assessment order, can claim a refund under Section 27(1)(ii) of the Customs Act.
    2. No Appeal Requirement: The absence of an appeal against the Bill of Entry does not bar the importer from seeking a refund.
    3. Legal Clarity: The judgment clarifies the scope of Section 27, ensuring that procedural technicalities do not prevent genuine refund claims.

    This decision strengthens the rights of importers and provides clear guidance on the interpretation of refund provisions under Indian customs law.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Delhi High Court Clarifies Limitation Law in Customs Refunds

    Delhi High Court Clarifies Limitation Law in Customs Refunds

    Date: 14.08.2026

    A recent batch of appeals before the Delhi High Court has brought significant clarity to the application of limitation law in customs refund cases. Senior India Pvt Ltd, a prominent importer, challenged several orders of the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) regarding the classification of imported goods and the timeliness of their refund claims. This article provides a detailed overview of the case, the legal issues involved, and the implications of the Court’s decision.

    Background of the Case

    Senior India Pvt Ltd imported pressure relief valves, which were initially classified under Customs Tariff Item (CTI) 8481 40 00. From September 2018, the company began declaring these goods under CTI 8409 99 41 and paid a higher duty, reportedly at the insistence of Customs authorities. Fourteen Bills of Entry were assessed between September 2018 and February 2019, with two additional Bills in March and May 2019.

    The legal landscape at the time, shaped by earlier Delhi High Court decisions, allowed importers to seek refunds under Section 27 of the Customs Act even if the assessment had not been appealed. Acting on this, Senior India filed two refund applications on 26 August 2019, within the statutory one-year period.

    The Turning Point: Supreme Court Judgment in ITC Limited

    While the refund proceedings were pending, the Supreme Court delivered a landmark judgment in ITC Limited v. Commissioner of Central Excise, Kolkata-IV (2019), holding that a refund claim could not be entertained unless the assessment was first modified in appeal. This fundamentally changed the legal basis for refund claims.

    Within days, Senior India sought to amend the Bills of Entry under Section 149 of the Customs Act and requested that refund proceedings be kept in abeyance. However, the refund authority rejected one claim as premature, and the company subsequently filed appeals under Section 128, seeking exclusion of the period spent on the refund process from the limitation period, invoking principles from Section 14 of the Limitation Act.

    Key Legal Issues

    The High Court focused on two main questions:

    1. Whether the authorities were justified in denying the benefit of Section 14 of the Limitation Act to Senior India, given the change in law by the Supreme Court’s ITC Limited judgment.
    2. Whether CESTAT was correct in dismissing an appeal as time-barred when the underlying appeal had been filed within the prescribed period.

    The Court’s Analysis and Findings

    • Application of Section 14 Principles: The Court recognized that while the Limitation Act does not directly apply to customs appeals, the principles underlying Section 14 (exclusion of time spent in bona fide proceedings) do apply. The Court found that Senior India had acted diligently, pursuing remedies as per the law prevailing at the time, and promptly adjusted its approach after the Supreme Court’s decision.
    • Exclusion of Time: The period during which Senior India pursued the refund remedy and sought amendment of Bills of Entry was excluded from the limitation calculation. The Court held that, due to the legal transition caused by the ITC Limited judgment, the authorities should have allowed this exclusion.
    • Statutory Extension Due to COVID-19: The Court also noted that the period for filing appeals was further extended by government notifications issued during the COVID-19 pandemic, making Senior India’s appeals timely.
    • Error in Dismissing Appeals as Time-Barred: In one case, the Court found that the appeal had been filed well within the statutory period, and its dismissal by CESTAT as time-barred was manifestly erroneous.

    Outcome and Directions

    • The High Court set aside the orders of CESTAT and the Commissioner (Appeals) that had rejected Senior India’s appeals on limitation grounds.
    • The appeals were restored for decision on merits, with instructions to the authorities not to revisit the limitation issue.
    • The Court directed that the restored appeals be decided within four months, and that refund and amendment applications be processed in accordance with the final outcome.

    Implications of the Judgment

    This decision is significant for importers and legal practitioners dealing with customs disputes:

    1. Clarifies Limitation Law: The judgment affirms that bona fide pursuit of remedies under the law as it stood can justify exclusion of time from limitation, especially when the legal position changes due to a higher court ruling.
    2. Ensures Fairness: The Court’s approach prevents penalizing parties for following the law as it existed before a judicial shift.
    3. Guidance for Future Cases: The decision provides a roadmap for handling similar disputes where refund claims or appeals are affected by changes in legal interpretation.

    Conclusion

    The Delhi High Court’s ruling in the Senior India Pvt Ltd case underscores the importance of judicial flexibility and fairness in applying limitation law, especially in the context of evolving legal standards. Importers and legal professionals should take note of this precedent when navigating refund and appeal processes under the Customs Act.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

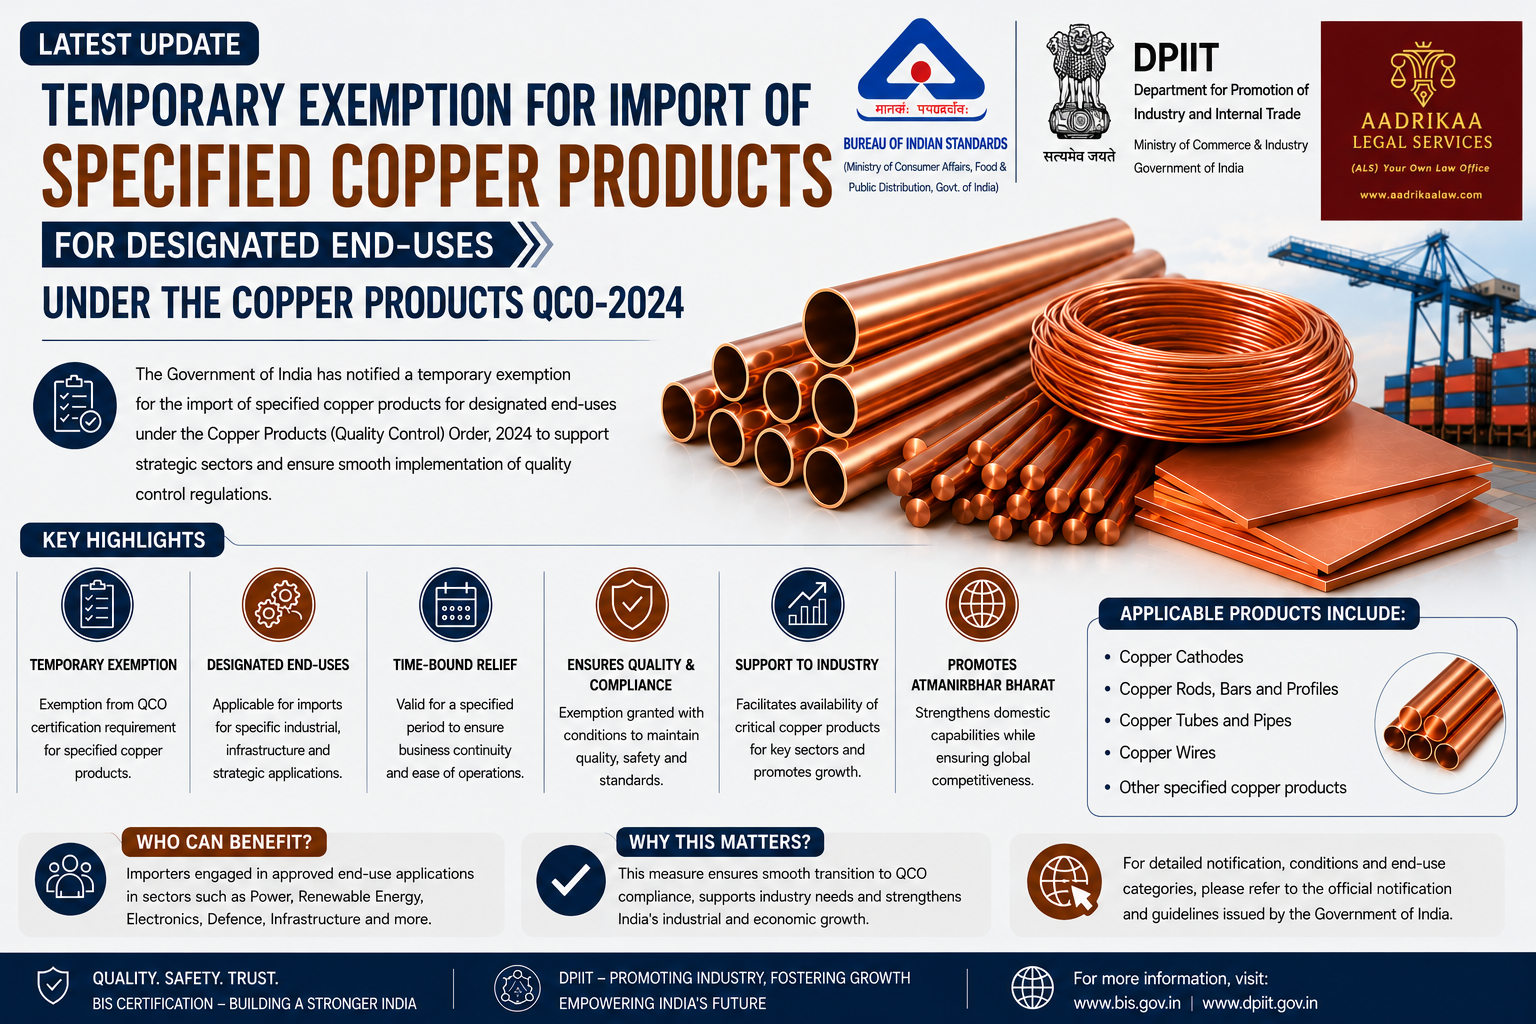
  • Temporary Exemption for Import of Specified Copper Products for Designated End-Uses under the Copper Products QCO-2024

    Temporary Exemption for Import of Specified Copper Products for Designated End-Uses under the Copper Products QCO-2024

    Date: 13.08.2026

    The Government of India has issued a significant order granting temporary exemptions for the import of specific copper products, addressing the needs of various industrial sectors. This move aims to bridge the gap between domestic supply and specialized requirements not currently met by Indian manufacturers or covered under the Copper Products (Quality Control) Order, 2024.

    Background and Rationale

    Industry stakeholders and associations highlighted challenges in sourcing certain high-purity and specialized copper products domestically, either due to lack of standards coverage or insufficient quality and quantity. Responding to these concerns, the Department for Promotion of Industry and Internal Trade (DPIIT), in consultation with the Bureau of Indian Standards (BIS), has provided a one-year exemption for select copper products, strictly for designated end-uses.

    List of Exempted Copper Products and Their End-Uses

    The exemption covers a range of copper products, each tied to a specific industrial application. Here’s a summary of the key products and their permitted uses:

    1. Oxygen Free Copper rods, bars, strips, and sheets (min. purity 99.995%, max. oxygen 5 PPM)
      • End-use: Vacuum interrupters
    2. Silver bearing Oxygen Free Copper, Zirconium Copper, High Conductivity Phosphorous-Deoxidised Copper rods, bars, and strips
      • End-use: Generator rotor coils, generators, electrical shunts
    3. Beryllium Alloy Copper Bar (End Wadge/Rotor Center Wedge-material grade)
      • End-use: Generators
    4. Oxygen Free Copper strips (min. purity 99.995%, max. oxygen 5 PPM)
      • End-use: Automotive bus bars for battery packs
    5. OFC Grade Copper Tape (0.18 mm x 81 mm and 0.095 mm x 85 mm)
      • End-use: RF feeder cables
    6. Billet & Section of Copper Alloy Grades (CuCr 90:10, CuZr 50:50, CuSi 90:10, CuP 85:15, CuTe 50:50)
      • End-use: Electrical contacts, short circuit rings, rotor bars for industrial and traction motors
    7. Copper Alloys C15000 (Zirconium Copper) and C18150 (Chromium Zirconium Copper) billets
      • End-use: Short circuit rings and rotor bars for traction and industrial motors
    8. Copper Alloy Strips (TRKFC 4, C151, DK Alloy, DSC-3N 1/2H, DK-3)
      • End-use: Bus bars for automobiles
    9. ETP Copper Plate in Coils (Grade C11000, Cu-ETP)
      • End-use: Electrical applications
    10. Hard Drawn Grooved Copper Tin alloy (150 sqmm and above, GT-SN)
      • End-use: Overhead electrical conductors
    11. Hard-Drawn Copper Wire (Dia 2.6mm, 99.9%+ purity)
      • End-use: Wiring harnesses for the automobile industry
    12. Enameled Copper Wire/Magnet Wire (0.01 to 0.16 mm, various grades)
      • End-use: Electrical wound components
    13. Copper Finned Tubes (externally and internally finned, various grades)
      • End-use: Chillers
    14. High Strength Copper Alloy Tubes (multiple grades)
      • End-use: Air-conditioning systems and electrical applications

    Conditions for Availing the Exemption

    To ensure traceability and promote future indigenization, importers must comply with the following conditions:

    1. Notification to BIS: Inform the Bureau of Indian Standards within 7 days of consignment clearance, using company letterhead and authorized signatory, via email.
    2. Quarterly Reporting: Maintain and submit quarterly records of imported goods to Central Government authorities, again on company letterhead and signed, via email.
    3. Indigenization Plan: Submit a plan for local manufacturing (indigenization) of the imported goods to the Central Government.

    Scope and Limitations

    • The exemption is valid for one year from the date of the order’s publication.
    • It applies strictly to the products and end-uses listed, and only to actual users (not traders or resellers).
    • The government reserves the right to review and amend the list of products and end-uses as needed.

    Implications for Industry

    This exemption provides immediate relief to sectors reliant on specialized copper products, such as electrical, automotive, and industrial equipment manufacturers. It also encourages importers to plan for future domestic production, aligning with the government’s broader Make in India initiative.

    For further details or compliance queries, stakeholders should contact the relevant government departments as specified in the official order.

    This proactive measure is expected to support critical industries while paving the way for enhanced domestic capabilities in the copper sector.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Madras High Court Quashes Customs Order and Emphasizes Right to Fair Hearing in Duty Drawback Disputes

    Madras High Court Quashes Customs Order and Emphasizes Right to Fair Hearing in Duty Drawback Disputes

    Date: 13.08.2026

    A recent judgment by the Madras High Court has significant implications for exporters and customs authorities alike. The case of M/s. Meegan Exports versus the Assistant Commissioner of Customs highlights the importance of due process, the right to be heard, and adherence to principles of natural justice in customs proceedings.

    Background of the Case

    M/s. Meegan Exports, represented by its proprietor Mr. Aashish Modi, exported construction materials to the Maldives under nine shipping bills between April and August 2022. The company availed itself of the duty drawback scheme, which allows exporters to claim a refund of certain duties paid on inputs used in exported goods.

    However, customs authorities initiated proceedings under Section 75(1) of the Customs Act, 1962, and relevant Drawback Rules, alleging that Meegan Exports failed to realize export sale proceeds within the period prescribed by the Foreign Exchange Management Act (FEMA), 1999. This led to the issuance of an Order-in-Original and a recovery letter demanding repayment of the availed drawback.

    Key Issues Raised

    1. Lack of Opportunity to be Heard
      • Meegan Exports contended that it never received the show cause notice and was not given a chance for a personal hearing before the adverse order was passed.
    2. Realization of Export Proceeds
      • The petitioner produced receipts from the Ministry of Commerce, Directorate General of Foreign Trade, evidencing realization of export proceeds, countering the basis for the customs action.
    3. Customs Authorities’ Stand
      • The respondents argued that notices were sent to the address on record and that the petitioner failed to respond despite multiple opportunities.

    The High Court’s Findings

    Justice Hemant Chandangoudar, after considering submissions from both sides, made several important observations:

    • No Proof of Non-Receipt: The petitioner did not provide concrete evidence that the show cause notice was not received.
    • Possession of Realization Receipts: Since Meegan Exports had receipts showing realization of export proceeds, enforcing the impugned order would cause undue monetary loss.
    • No Prejudice to Customs: Granting another opportunity to the petitioner would not prejudice the customs authorities.

    The Court’s Order

    The High Court set aside both the Order-in-Original and the recovery letter. The matter was remanded to the customs authorities for fresh consideration, with clear directions:

    1. Personal Hearing: The petitioner must be given an opportunity for a personal hearing.
    2. Consideration of Evidence: All documents, including bank realization certificates, must be reviewed.
    3. Timely Disposal: The process must be completed within two months from the date of receipt of the court’s order.
    4. Proper Notice: Notices must be sent to the updated address provided by the petitioner.

    Implications for Exporters and Authorities

    This judgment reinforces several key principles:

    • Natural Justice: Authorities must ensure that affected parties receive proper notice and a fair chance to present their case.
    • Documentation: Exporters should maintain and promptly submit all relevant documents, such as bank realization certificates, to defend their claims.
    • Procedural Fairness: Even if procedural lapses occur, courts may grant another opportunity to prevent undue hardship, provided no prejudice is caused to the authorities.

    Conclusion

    The Madras High Court’s decision in the Meegan Exports case serves as a reminder of the critical role of procedural fairness in administrative actions. Exporters facing similar issues should be vigilant about responding to notices and maintaining comprehensive records, while authorities must adhere strictly to principles of natural justice.

    This case sets a precedent for balancing enforcement with fairness, ensuring that justice is not only done but seen to be done.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • CESTAT Kolkata Overturns Customs Valuation and Penalties on Polyester Quilt Cover Imports

    CESTAT Kolkata Overturns Customs Valuation and Penalties on Polyester Quilt Cover Imports

    Date: 13.08.2026

    The Customs, Excise and Service Tax Appellate Tribunal (CESTAT) Kolkata recently delivered a significant judgment in the case involving M/s. Annapurna Industries and the classification, valuation, and penalization of imported polyester quilt covers. This article provides a detailed analysis of the case, the legal issues involved, and the implications for importers and customs authorities.

    Background of the Case

    M/s. Annapurna Industries imported polyester quilt covers from China, declaring them under Customs Tariff Heading (CTH) 63022200 at a transaction value of USD 1.20–1.25 per piece (CIF). Customs authorities, after a first-check examination, observed that the goods were one-side folded and two sides stitched. They opined that these could be converted into bed sheets by removing the stitches, leading to:

    1. Rejection of the declared value under Rule 12 of the Customs Valuation Rules, 2007.
    2. Enhancement of the assessable value to USD 2.85 per piece.
    3. Confiscation of goods under Section 111(m) of the Customs Act.
    4. Imposition of redemption fine and penalty.

    Faced with heavy demurrage and detention charges, Annapurna Industries paid the enhanced duty, fine, and penalty under protest to secure release of the goods, and subsequently appealed the decision.

    Key Legal Issues Examined

    The Tribunal addressed four main questions:

    1. Can imported goods be re-characterized based on their potential for further processing?
    2. Is it lawful to enhance valuation solely on the basis of contemporaneous imports?
    3. Are confiscation and redemption fine sustainable without proven misclassification or undervaluation?
    4. Is the penalty under Section 112(a) of the Customs Act justified in this context?

    1. Classification of Goods: Actual Condition vs. Hypothetical Use

    The Tribunal reaffirmed the principle that goods must be assessed in the condition in which they are imported, not on the basis of what they could become after further processing. The Department’s assumption that the quilt covers could be converted into bed sheets was deemed hypothetical and not a valid basis for reclassification. The Tribunal noted:

    • The goods were presented as stitched quilt covers, fitting the statutory definition of “made-up articles.”
    • The Textile Committee, an expert body, had previously classified similar goods under Heading 6302, supporting the appellant’s position.
    • Previous CESTAT decisions (e.g., Indra Fab, C.F. Inc., and M/s. Annapurna Industries & Others) upheld similar classifications.

    2. Valuation: Transaction Value vs. Comparables

    The Tribunal found that Customs had rejected the declared transaction value without objective evidence, relying instead on unrelated imports of “bed sheets” without ensuring comparability in terms of manufacturer, quality, GSM, construction, brand, finish, commercial level, or quantity. Key points:

    • Rule 12 of the Valuation Rules allows rejection of transaction value only with reasonable doubt supported by evidence.
    • No evidence of additional remittance, relationship, fabricated invoices, or false pricing was found.
    • Legal precedents (Eicher Tractors, Mirah Exports, Mahindra & Mahindra, etc.) require positive evidence for value rejection.

    3. Confiscation and Redemption Fine

    Since misclassification and undervaluation were not established, the foundation for confiscation under Section 111(m) and redemption fine under Section 125 was absent. The Tribunal also noted that Section 125 requires a market price determination before fixing redemption fine, which was not conducted in this case.

    4. Penalty Under Section 112(a)

    With the main allegations unproven, the Tribunal held that the ingredients for imposing a penalty under Section 112(a) did not exist, and thus the penalty was set aside.

    Final Outcome and Implications

    The CESTAT Kolkata set aside the impugned orders, allowing the appeals filed by Annapurna Industries with consequential relief. This judgment reinforces several important principles for importers and customs authorities:

    1. Goods must be classified and valued as presented at import, not based on hypothetical future use.
    2. Transaction value cannot be rejected without concrete evidence of undervaluation or misdeclaration.
    3. Penalties and fines require a solid legal foundation and proper procedural compliance.

    Conclusion

    The Annapurna Industries case is a landmark in clarifying the approach to classification, valuation, and penalization of imported goods. It underscores the need for objective evidence and adherence to statutory procedures, providing valuable guidance for both importers and customs officials.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Gujarat High Court on Recovery of Duty Drawback from Exporters

    Gujarat High Court on Recovery of Duty Drawback from Exporters

    Date: 12.08.2026

    This article analyzes a significant judgment by the Gujarat High Court regarding the recovery of duty drawback payments made to exporters under the Customs and Central Excise Duty Drawback Rules. The case, involving Pratibha Syntex Limited and others versus the Union of India, addresses the legality and timeliness of recovering excess drawback payments from exporters.

    Background: Duty Drawback Scheme and Dispute

    The petitioners, recognized export houses, exported fabrics made from 100% polyester filament yarn. Under the Drawback Rules, exporters of specified goods are entitled to a refund (drawback) of duties paid on inputs. The relevant schedule (Sub Serial No. 5404) initially allowed a 20% drawback (subject to a maximum of Rs. 62 per kg of filament yarn content) if certain conditions were met. Later, a reduced rate of 17% was introduced for cases where exporters could not provide specific excise certificates, but there was confusion about whether the Rs. 62 per kg cap applied to this reduced rate.

    Sequence of Events

    1. Initial Payments: Exporters received drawback at 17% of FOB value without the Rs. 62 per kg cap, based on the authorities’ interpretation at the time.
    2. Clarifications Issued: In September 1996, the Commissioner (Drawback) clarified that the Rs. 62 per kg ceiling applied even to the 17% rate. This was later reinforced in 1999, stating the clarification was effective from the original notification date.
    3. Recovery Notices: Over three years after the original payments, show cause notices were issued to recover the excess drawback paid above the Rs. 62 per kg limit.
    4. Legal Proceedings: The exporters challenged these recovery actions, arguing that such delayed demands were time-barred and violated principles of fairness.

    Key Legal Issues

    1. Applicability of Limitation Period

    • Rule 16 of the Drawback Rules: Allows recovery of erroneously paid drawback but does not specify a time limit.
    • Petitioners’ Argument: Even if no explicit limitation is prescribed, a reasonable period must be implied, drawing on Supreme Court precedents.
    • Government’s Argument: The absence of a statutory limitation means recovery can be initiated at any time.

    2. Judicial Reasoning

    The High Court examined:

    • Supreme Court rulings (e.g., Government of India v. Citedal Fine Pharmaceuticals) that, in the absence of a statutory limitation, authorities must act within a “reasonable period.”
    • The facts: Drawback was paid between December 1995 and August 1996; recovery notices were issued only in February 2000, despite clarifications being available much earlier.

    The Court’s Decision

    • The Court held that a delay of more than three years in issuing recovery notices was not reasonable.
    • It ruled that, although Rule 16 does not specify a limitation period, the concept of a reasonable period must be read into the rule to prevent arbitrary and disruptive actions against exporters.
    • The show cause notices and subsequent recovery orders were quashed as time-barred.

    Implications of the Judgment

    1. Protection for Exporters: The judgment safeguards exporters from indefinite exposure to recovery actions, ensuring administrative certainty.
    2. Guidance for Authorities: Customs and excise authorities must act promptly and within a reasonable timeframe when seeking to recover excess payments.
    3. Legal Precedent: The decision reinforces the principle that, in the absence of explicit statutory limitation, a reasonable period is implied by law.

    Conclusion

    This Gujarat High Court judgment is a landmark in balancing government powers and exporters’ rights under the duty drawback scheme. It underscores the necessity for timely administrative action and provides clarity on the interpretation of limitation in recovery proceedings under the Drawback Rules.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • CESTAT New Delhi- The reassessment was held to be invalid and legally unsustainable

    CESTAT New Delhi- The reassessment was held to be invalid and legally unsustainable

    Date: 03.05.2025

    The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), Principal Bench, New Delhi, ruled in favour of M/s Trina Steelcarb Pvt. Ltd., setting aside a reassessment order that enhanced the assessable value of imported goods without issuing a speaking order as mandated under Section 17(5) of the Customs Act, 1962.

    1. Violation of Section 17(5): The Tribunal found that the assessing officer failed to issue a speaking order despite the reassessment being contrary to the importer’s declared self-assessment and without written acceptance. Section 17(5) mandates issuance of a speaking order within 15 days in such cases.

    Handy Download: