Tag: #Lawyers

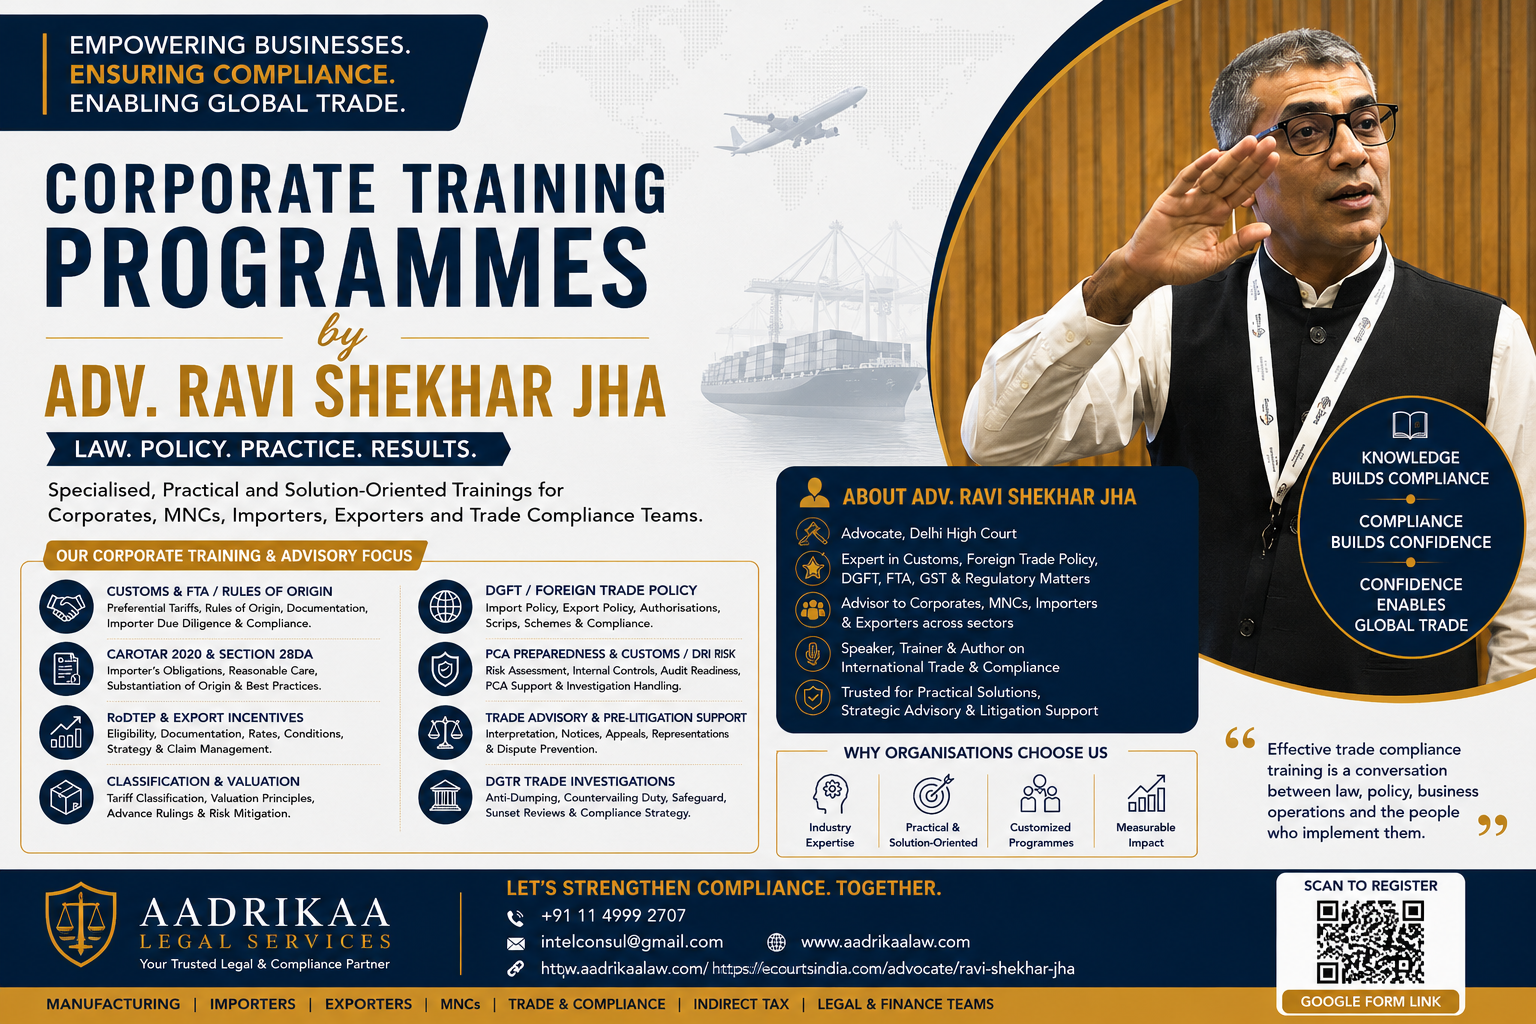
  • Advocate Ravi Shekhar Jha conducts a corporate Masterclass for Syngenta India on FTAs, CAROTAR 2020, Customs compliance, Rules of Origin, RoDTEP, export incentives and Foreign Trade Policy

    Advocate Ravi Shekhar Jha conducts a corporate Masterclass for Syngenta India on FTAs, CAROTAR 2020, Customs compliance, Rules of Origin, RoDTEP, export incentives and Foreign Trade Policy

    Date: 31.08.2026

    From Trade Benefits to Trade Readiness β€” Compliance Must Come First

    It was a privilege to conduct an intensive Masterclass on Free Trade Agreements (FTAs), Customs Compliance, RoDTEP and Export Incentives for the Syngenta India team at its Pune headquarters, with professionals participating across functions and geographies.

    The programme focused on an increasingly important reality of international trade: trade benefits can be effectively realised only when they are supported by strong regulatory compliance, documentation and internal controls.

    The session brought together professionals from Trade Compliance & Customs, R&D, Logistics, GST, Trade Finance and Procurement, resulting in highly engaging discussions around the practical application of Customs law, Foreign Trade Policy and FTA requirements.

    From FTA Benefits to Compliance Readiness

    A major focus of the programme was the effective utilisation of preferential tariff benefits under India’s Free Trade Agreements.

    FTA benefits are not simply about claiming a lower rate of Customs duty. Businesses must consider the complete compliance framework surrounding the transaction, including:

    • correct tariff classification;
    • applicable Rules of Origin and Product Specific Rules (PSR);
    • origin documentation and supporting records;
    • importer due diligence;
    • valuation and Customs compliance; and
    • preparedness for subsequent verification by Customs authorities.

    The discussions also examined Section 28DA of the Customs Act, 1962 and CAROTAR 2020, including the importer’s responsibility to exercise reasonable care and maintain sufficient information to substantiate the origin criteria applicable to preferential imports.

    The underlying message was clear: a proof/certificate of origin should form part of a wider origin-compliance framework rather than being treated as the sole basis for an FTA claim.

    Classification, Valuation and Origin: Connected Compliance Controls

    Another important theme was the relationship between tariff classification, Customs valuation and origin. Although these are legally distinct concepts, they frequently interact in determining the ultimate Customs duty exposure, availability of preferential tariff treatment and overall transaction risk.

    Businesses therefore need to examine these issues before imports are undertaken, rather than addressing them only when a query is raised during Customs assessment or a subsequent audit or investigation.

    RoDTEP & Export Incentives

    The programme also covered RoDTEP and India’s export remission and incentive framework, with emphasis on evaluating benefits strategically. Exporters should assess eligibility, notified rates, documentation requirements, product classification and applicable conditions before structuring their claims.

    The objective should not merely be to identify available benefits, but to establish processes capable of supporting those benefits during subsequent regulatory scrutiny.

    Compliance Should Begin Before the Transaction

    Perhaps the most important takeaway from the Masterclass was simple:

    Compliance should begin before the transaction β€” not after Customs raises a query.

    Effective trade compliance requires coordination between law, policy and actual business operations. Procurement, logistics, finance, taxation, R&D and trade-compliance teams therefore need to work together rather than treating Customs and FTA compliance as isolated functions.

    The quality of participation, practical questions and cross-functional discussions from the Syngenta India team made the programme particularly rewarding. My sincere appreciation to the entire participating team for investing in continuous capability development and for the thoughtful and highly engaging discussions throughout the programme.

    Customised Corporate Trade Compliance Programmes

    Through Aadrikaa Legal Services, customised executive workshops, corporate training and advisory programmes can be structured for MNCs, manufacturers, importers, exporters and trade-compliance teams covering

    a. FTA , CAROTAR 2020 & Section 28DA

    b. RoDTEP & export incentives,

    c. Classification & General Rules of Interpretation  (GRI)

    d. Valuation

    e. DGFT/Foreign Trade Policy- EPCG/Advance License

    f. Customs Special Programmes- SVB, AEO, MOOWR, EMI

    g. PCA preparedness and Customs/DRI risk

    h. trade advisory and pre-litigation support

    i. DGTR trade investigations

    j. Customs & allied regulatory laws (PGAs)

    Secure your operations. Strengthen compliance. Reduce cross-border friction.

    Advocate Ravi Shekhar Jha
    Customs | Foreign Trade Policy | FTA | Trade & Regulatory Advisory

    Google Form Link

    🌐 Aadrikaa Legal Services
    πŸ“§ intelconsul@gmail.com
    βš–οΈ Professional Profile – Advocate Ravi Shekhar Jha

    Knowledge builds compliance. Compliance builds confidence. Confidence enables global trade.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

  • Karnataka High Court Grants Bail to Nigerian National in Major NDPS Drug Trafficking After Four Years in Custody

    Karnataka High Court Grants Bail to Nigerian National in Major NDPS Drug Trafficking After Four Years in Custody

    Date: 31.08.2026

    A recent order by the High Court of Karnataka has brought significant attention to the legal processes surrounding bail for foreign nationals accused under the Narcotic Drugs and Psychotropic Substances (NDPS) Act. The case involves Mr. Samuel Chinweike Anoh, a Nigerian national, who was granted bail after spending over four years in custody, despite serious allegations of drug trafficking. This article provides a detailed overview of the case, the court’s reasoning, and the broader legal context.

    Background of the Case

    • Case Details:
      • Petitioner: Mr. Samuel Chinweike Anoh (Accused No. 3)
      • Respondent: Union of India, represented by the Customs Intelligence Unit (CIU), Bengaluru
      • Offences: Sections 8(c), 21(c), 22, 23, 28, and 29 of the NDPS Act
      • Allegations: Involvement in the shipment and attempted collection of consignments containing MDMA (4.581 kg) and heroin (1.002 kg) disguised as machine parts and personal items.
    • Chronology:
      • Shipments intercepted at FedEx, Bengaluru, based on credible information.
      • Accused Nos. 1 and 2 arrested while collecting the shipments; contraband seized from their possession.
      • Petitioner (Accused No. 3) arrested based on their confession statements.
      • Petitioner remained in custody for over four years; trial delayed at the stage of witness examination.

    Legal Arguments and Court Observations

    Arguments by the Petitioner

    • No contraband was seized from the petitioner directly.
    • Arrest and charges based solely on co-accused confessions.
    • Co-accused (Accused Nos. 1 and 2) had already been granted bail due to prolonged incarceration and trial delays.
    • Petitioner has been in custody for an extended period with little progress in the trial.

    Arguments by the Respondent

    • Petitioner allegedly played an active role and has similar criminal antecedents.
    • As a foreign national without valid documents, the petitioner poses a flight risk and must be detained even if granted bail, as per Supreme Court and High Court precedents.

    Court’s Analysis

    • Delay in Trial: The court noted that out of eight charge sheet witnesses, not even one had been fully examined after four years, echoing Supreme Court judgments that prolonged incarceration without trial progress justifies bail.
    • No Direct Seizure: The petitioner was not found in possession of contraband; his arrest was based on confessions of others.
    • Precedents Cited:
      • Chitta Biswas v. State of West Bengal: Bail granted due to long custody and slow trial.
      • Nitish Adhikary v. State of West Bengal: Bail granted when only one witness examined after long custody.
      • Mohd. Muslim v. State (NCT of Delhi): Courts should consider bail if guilt is not prima facie established and trial is unduly delayed.
      • Javed Gulam Nabi Shaikh v. State of Maharashtra: Right to speedy trial under Article 21 applies regardless of crime seriousness.

    Guidelines for Foreign Nationals

    The court reiterated and applied guidelines from previous judgments regarding foreign nationals:

    • Immediate initiation of deportation proceedings if a foreign national is found without valid documents.
    • If bail is granted, the individual must be detained in a detention center until trial concludes or deportation is arranged.
    • Courts and authorities must prioritize speedy disposal of such cases and ensure humane treatment in detention centers.

    Bail Order and Conditions

    The High Court allowed the bail petition with the following conditions:

    1. Execution of a personal bond of Rs. 1,00,000 with two sureties.
    2. Detention in a designated center in Bangalore until the trial concludes.
    3. Regular appearance before the trial court.
    4. No tampering with evidence or witnesses.
    5. No involvement in similar offences in the future.

    Broader Legal Implications

    • Right to Speedy Trial: The order reinforces the constitutional right to a speedy trial, especially in cases involving severe charges under the NDPS Act.
    • Treatment of Foreign Nationals: The judgment clarifies the process for handling foreign nationals accused of serious crimes, balancing legal procedures with human rights and national security.
    • Judicial Precedents: The court’s reliance on Supreme Court decisions ensures consistency and fairness in bail jurisprudence, even in high-stakes narcotics cases.

    Conclusion

    This case highlights the importance of upholding fundamental rights, even in serious criminal matters. The High Court’s decision underscores the judiciary’s commitment to fair trial standards, due process, and humane treatment of all accused, including foreign nationals, while ensuring that legal safeguards and national interests are maintained.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.
    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi

  • Customs Classification of Imported Polyester Knitted Fabrics

    Customs Classification of Imported Polyester Knitted Fabrics

    Date: 31.08.2026

    The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), Kolkata, recently delivered a significant judgment in the case of M/s. Elvance Overseas LLP regarding the customs classification and duty assessment of imported polyester knitted fabrics. This article provides a detailed overview of the dispute, the legal arguments, and the Tribunal’s final decision, offering valuable insights for importers, customs professionals, and legal practitioners.

    Background of the Case

    Elvance Overseas LLP, a Delhi-based importer, brought in consignments described as “Mixed Lot of Polyester Knitted Fabrics” from Chinese suppliers. The company filed six Bills of Entry, classifying the goods under Customs Tariff Item (CTI) 6006 9000 and claimed a concessional Basic Customs Duty (BCD) rate of 10% under Notification No. 82/2017-Customs. The total assessable value of the imports was over Rs. 2.17 crore, and the declared customs duty paid was Rs. 36 lakh.

    Table: Summary of Bills of Entry

    Sl. No.Bill of Entry No.DateSupplierDescriptionAssessable Value (Rs.)
    1822992827.09.2018Dauer International Ltd., U.K.Mixed lot of Polyester Knitted Fabric28,42,278.51
    2805626115.09.2018Dauer International Ltd., U.K.Mixed lot of Polyester Knitted Fabric49,21,368.00
    3844511413.10.2018LCL Group Co. Ltd., H.K.Mixed lot of Polyester Knitted Fabric (non printed)28,21,408.00
    4844493713.10.2018LCL Group Co. Ltd., H.K.Mixed lot of Polyester Knitted Fabric (non printed)28,51,792.00
    5793936606.09.2018Dauer International Ltd., U.K.Mixed lot of Polyester Knitted Fabric54,67,566.00
    6833828505.10.2018Dauer International Ltd., U.K.Mixed lot of Polyester Knitted Fabric (non printed)28,53,163.00
    Total2,17,57,575.51

    The Department’s Stand

    The Customs Department challenged the classification, arguing that the imported goods should be classified under CTI 6006 3200 (knitted fabrics of synthetic fibres), attracting a higher BCD of 20%. The Department alleged that Elvance Overseas LLP misclassified the goods to avail a lower duty rate, and issued a Show Cause Notice demanding differential duty of Rs. 25.13 lakh, along with interest and penalty under Section 114A of the Customs Act, 1962.

    Legal Arguments

    Appellant’s Contentions

    1. Burden of Proof: The importer argued that the burden to prove misclassification lies with the Revenue, which must provide technical or scientific evidence.
    2. Need for Laboratory Testing: Classification depends on fiber composition and other technical parameters, which require laboratory analysis. No such testing was conducted by the Department.
    3. Interpretation of Chapter 60: The chapter requires careful analysis, and mixed lots cannot be presumed to be 100% synthetic without scientific proof.
    4. Contemporaneous Assessment: Other customs ports had accepted similar goods under the same classification, and any deviation must be justified.
    5. Finality of Assessment: The original assessment was completed and accepted by the proper officer; changing it without new evidence is not permissible.
    6. Lack of Evidence: The Department failed to provide any laboratory reports, technical literature, or expert opinions to support reclassification.

    Department’s Arguments

    • The Department maintained that the goods were polyester knitted fabrics, which are synthetic by definition, and thus should be classified under CTI 6006 3200.
    • They argued that the importer’s own description supported this classification and that the lower duty rate was wrongly claimed.

    Tribunal’s Analysis and Findings

    The Tribunal examined the facts and legal submissions in detail:

    1. Original Assessment Holds Weight: The goods were assessed and cleared under the declared classification, and the Department did not challenge this at the time.
    2. No Laboratory Evidence: The Department did not conduct any laboratory testing to establish the actual composition of the imported fabrics.
    3. Mixed Lot Description: The term β€œMixed Lot” indicates a variety of fabrics, not necessarily homogeneous synthetic fibre content. Without testing, the Department could not conclusively prove the goods were synthetic.
    4. Contemporaneous Practice: Other importers had similar goods classified under CTI 6006 9000, and the Department had accepted this practice elsewhere.
    5. No Evidence of Suppression or Malafide: There was no proof of deliberate misstatement or intent to evade duty by the importer.

    Final Order and Impact

    The CESTAT Kolkata ruled in favor of Elvance Overseas LLP, holding:

    • The goods are correctly classifiable under CTI 6006 9000.
    • The demand for differential duty and penalty is set aside.
    • The appeal is allowed with consequential relief.

    Key Takeaways for Importers

    1. Importance of Evidence: Customs authorities must provide concrete evidence, such as laboratory reports, to challenge an importer’s declared classification.
    2. Finality of Assessment: Once an assessment is completed and accepted, it cannot be changed without new, substantive evidence.
    3. Consistency in Classification: Uniformity in classification across ports is crucial; arbitrary changes can be challenged.
    4. Interpretational Disputes: Penalties should not be imposed in cases involving genuine interpretational differences without evidence of malafide intent.

    Conclusion

    This ruling reinforces the principle that customs classification disputes must be resolved based on evidence and established legal standards, not assumptions or administrative convenience. Importers should ensure accurate documentation and be prepared to defend their classification with technical data, while authorities must adhere to due process and evidentiary requirements.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi

  • Bombay High Court Sets Aside Patent Refusal for Lack of Reasoned Order and Remands for Fresh Consideration under Section 117A of the Patents Act, 1970

    Bombay High Court Sets Aside Patent Refusal for Lack of Reasoned Order and Remands for Fresh Consideration under Section 117A of the Patents Act, 1970

    Date: 31.08.2026

    The Bombay High Court recently delivered a significant judgment in the case of Deepak Nitrite Limited vs. The Assistant Controller of Patents & Designs. This case revolved around the refusal of a patent application for a novel food-grade sodium nitrite and its production method. The judgment not only impacts the parties involved but also sets important precedents for patent examination standards in India.

    Background of the Case

    Deepak Nitrite Limited filed a patent application (No. 202021019409) for “A Free-Flowing Food Grade Sodium Nitrite and Production Method Thereof.” The Assistant Controller of Patents & Designs, Mumbai, refused the application under Section 15 of the Patents Act, 1970, citing lack of inventive step as per Section 2(1)(ja) of the Act. The refusal was based on the assertion that the claimed reduction in impurities was common general knowledge and that the process steps were routine laboratory procedures.

    Key Arguments Presented

    Petitioner’s Submissions

    1. Product Claims (Claims 1-3):
      • The claimed product was distinguished from prior art by its unique impurity profile, crucial for achieving food-grade quality.
      • The Controller’s order failed to cite any authoritative source for the alleged “common general knowledge” and did not analyze whether the specific impurity profile was disclosed or suggested in prior art.
    2. Process Claims (Claims 4-8):
      • The process involved a synergistic combination and specific sequencing of steps, not merely routine filtration.
      • The Controller isolated a single step (filtration) and ignored the inventive contribution of the integrated process.
    3. Legal Precedents:
      • The petitioner cited several judgments emphasizing the need for a reasoned analysis, identification of inventive concepts, and proper assessment of common general knowledge.

    Respondent’s Submissions

    • The Respondent defended the refusal, arguing that the order was passed after due examination.
    • Upon judicial questioning, the Respondent conceded that the order lacked independent analysis of the process claims and that it would have been more appropriate to consider the invention as a whole.

    Court’s Analysis and Findings

    1. On Common General Knowledge:
      • The Court held that invoking “common general knowledge” without citing identifiable sources is impermissible and arbitrary.
      • The Controller must substantiate such assertions with published sources predating the patent application.
    2. On Reasoned Orders:
      • The Court criticized the recurring pattern of non-speaking, inadequately reasoned orders from the Patent Office.
      • It emphasized the mandatory obligation of Controllers to provide well-reasoned, speaking orders that demonstrate independent application of mind and address all objections and responses.
    3. On Remand and Future Conduct:
      • The Court set aside the impugned order and remanded the matter for fresh consideration by a different Controller.
      • It directed that the application be decided within twelve weeks, ensuring compliance with the standards outlined in the judgment.

    Broader Implications

    This judgment highlights systemic issues in patent examination, such as:

    • Failure to provide applicants a fair opportunity to address objections.
    • Lack of independent reasoning and mechanical reproduction of prior art or objections.
    • The need for transparency and accountability in quasi-judicial decisions.

    The Court’s directions reinforce the importance of reasoned decision-making and adherence to natural justice principles in the patent grant process. The judgment is expected to influence future conduct of the Patent Office and improve the quality of patent examination in India.

    Conclusion

    The Bombay High Court’s decision in Deepak Nitrite Limited vs. Assistant Controller of Patents & Designs is a landmark ruling that strengthens procedural safeguards for patent applicants. It underscores the judiciary’s commitment to upholding fairness, transparency, and reasoned analysis in intellectual property adjudication.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi

  • Madras High Court Quashes Customs Duty and Penalty on Shipping Agent

    Madras High Court Quashes Customs Duty and Penalty on Shipping Agent

    Date: 29.08.2026

    A recent judgment by the Madras High Court in the case of C.Solomon Selvaraj vs. Principal Commissioner of Customs has significant implications for customs law, particularly regarding the liability of agents and facilitators in import transactions involving alleged smuggling. This article provides a detailed overview of the case, the legal arguments, the court’s reasoning, and its broader impact.

    Background of the Case

    The dispute centers on an import consignment declared as gas stoves and spare parts, but upon inspection, authorities discovered a large quantity of undeclared sewing machine needles and steel measuring tapes. The consignment was imported under the name of M/s. R.M. Enterprises, whose ownership and address were found to be fictitious. The Directorate of Revenue Intelligence (DRI) initiated an investigation, leading to the involvement of Mr. C. Solomon Selvaraj, proprietor of M/s. The Sea Shipping Forwarders.

    Allegations and Department’s Stand

    The Customs Department alleged that:

    1. Mr. Selvaraj received import documents from an individual named Vishal and handed them to the Customs Broker.
    2. He instructed the Customs Broker to file the Bill of Entry in the name of M/s. R.M. Enterprises.
    3. He paid customs duty from his firm’s bank account and arranged for the clearance of the consignment.
    4. The Department relied on Mr. Selvaraj’s statement under Section 108 of the Customs Act, where he admitted to handling the clearance on behalf of Vishal and to previous similar transactions.

    Based on these findings, the Department imposed a differential customs duty of Rs. 4,56,00,374 and equivalent penalties on Mr. Selvaraj, treating him as jointly and severally liable with other parties.

    Legal Proceedings and Arguments

    Mr. Selvaraj challenged the order, arguing that:

    • He was neither the owner nor the beneficial owner of the goods.
    • The Department failed to prove he had knowledge of the undeclared goods or knowingly participated in smuggling.
    • Previous penalties imposed on him in similar cases had been set aside by the Customs, Excise and Service Tax Appellate Tribunal (CESTAT).

    The High Court had earlier remitted the matter for fresh consideration, directing the Department to specifically determine whether Mr. Selvaraj had knowledge of the attempted smuggling and to assess his liability based on his actual role.

    Court’s Analysis and Findings

    The High Court made several key observations:

    1. Involvement in Clearance Not Sufficient: Merely facilitating customs clearance does not make a person the owner or beneficial owner of goods, nor does it establish knowledge of smuggling.
    2. Agency Under Customs Act: Section 147(3) of the Customs Act requires clear evidence that a person was expressly or impliedly authorized by the actual owner/importer to act as an agent. This was not established in Mr. Selvaraj’s case.
    3. No Evidence of Knowledge or Intent: The court found no specific or reasoned finding that Mr. Selvaraj had prior knowledge of the concealed goods or knowingly facilitated their smuggling.
    4. Reliance on Previous Proceedings Unjustified: The Department’s reliance on earlier proceedings was misplaced, as those penalties had been set aside by the CESTAT.
    5. Penalty Provisions Not Attracted: For penalties under Sections 114A and 114AA of the Customs Act, the law requires proof of knowledge, intent, or collusion, which was absent in this case.

    Judgment and Impact

    The High Court set aside the order imposing duty and penalties on Mr. Selvaraj, holding that:

    • The Department failed to establish the necessary findings regarding his knowledge or intent.
    • Liability for customs duty and penalties cannot be fastened merely on the basis of involvement in the clearance process or unproven allegations of abetment.
    • The order is confined to Mr. Selvaraj and does not affect proceedings against other parties.

    Key Takeaways

    1. Due Process in Customs Investigations: Authorities must establish clear evidence of knowledge or intent before imposing liability on agents or facilitators.
    2. Limits of Agency Liability: The mere act of facilitating customs clearance does not automatically make one liable as an importer or beneficial owner.
    3. Importance of Specific Findings: Penalties under customs law require specific and reasoned findings, not just circumstantial involvement.

    Conclusion

    This judgment reinforces the principle that liability under customs law must be based on concrete evidence of knowledge and intent, not mere association or procedural involvement. It serves as a crucial precedent for importers, customs brokers, and logistics professionals, emphasizing the need for thorough investigations and adherence to due process.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi

  • Train for your CBLR Exams 2027 under the most with Prolific Trainer in India: Enrollment Now Open

    Train for your CBLR Exams 2027 under the most with Prolific Trainer in India: Enrollment Now Open

    Date: 29.08.2026

    The National Academy of Customs, Indirect Taxes and Narcotics (NACIN) has officially set the stage for the Customs Brokers Licensing Regulations (CBLR) Examination 2027. This lifetime-valid Regulation 6 license is the golden ticket to top-tier career opportunities in global logistics, customs clearance, and international trade compliance.

    This critical public announcement has been picked up and advanced by India’s most prolific and versatile customs law trainer: Advocate Ravi Shekhar Jha. Practicing at the Delhi High Court and an esteemed DHCBA Member, he is launching the highly anticipated CBLR 2027 Preparation Batch-2. This intensive program bridges complex legal statutory frameworks with practical port compliance rules.

    πŸš€ Key Highlights of the CBLR 2027 Exam

    • Massive Weightage: Written paper consists of 150 Multiple Choice Questions (MCQs).
    • Negative Marking: Features a strict +3 for correct and -1 for incorrect marking scheme.
    • Passing Benchmark: Requires a mandatory score of 60% (270 out of 450 marks) to pass.
    • Strict Attempt Cap: Candidates are permitted a maximum of 6 lifetime attempts.
    • Dual-Stage Clearance: Written exam clearance is mandatory to sit for the subsequent Oral Viva Voce.

    πŸ‘¨β€πŸ« Meet Your Trainer: Advocate Ravi Shekhar Jha

    • Legal Authority: Practicing Advocate at the Delhi High Court (DHCBA Member).
    • Proven Track Record: Acclaimed expert and prolific trainer in Customs Law & EXIM Policy.
    • Practical Legal Approach: Simplifies complex judicial principles and Section 149/Section 14 amendments.
    • Direct Communication: Accessible directly for candidate queries via email at intelconsul@gmail.com.

    πŸ“… 3-Month Accelerated Program Schedule

    • Total Program Length: Exactly 3 Months.
    • Weekly Frequency: Twice a week on Wednesdays and Fridays.
    • Batch Timings: Evening sessions from 7:00 PM to 9:00 PM (2 Hours each).
    • Digital Backup: Full Recorded Sessions support to revise complicated case laws at your convenience.

    πŸ“š Broad Course Structure

    Month 1: Customs Core & Valuation Systems

    • The Customs Act, 1962: In-depth entry, assessment, and port clearance protocols.
    • Customs Tariff Act: Rules of interpretation and cargo classification principles.
    • Valuation Rules: Breakdown of transaction value, related party rules, and transfer pricing.

    Month 2: Allied Acts & Trade Documentation

    • Foreign Trade Policy (FTP): Decoding DGFT handbooks, SEZ, and export incentive schemes.
    • Allied Laws: Compliance integration with FSSAI, AQCS, PQCS, and Drug Controller regulations.
    • Documentation Architecture: Mastering electronic Bill of Entry and Shipping Bill layouts.

    Month 3: Simulated Drills & Viva Prep

    • High-Yield MCQ Drill: Speed and accuracy practice under simulated negative marking pressures.
    • Digital Trade Training: Navigation over ICEGATE and CBLMS portal updates.

    πŸ› οΈ The Strategic Edge: Treximerce Trade Companion

    Theoretical knowledge isn’t enough to pass this technical exam. Candidates in this batch get exclusive access to the Treximerce Trade Companion tool, providing an elite competitive advantage:

    • Instant Tariff Lookup: Speeds up learning of complex HS Codes, duty rates, and notifications.
    • Live Circular Mapping: Links raw legal sections directly to current CBIC circulars and anti-dumping acts.
    • Visual Memory Retention: Translates dry statutory text into clear, operational digital trade compliance flows.

    πŸ’° All-Inclusive & Catchy Fee Structure

    Invest in your professional future with a transparent, high-value fee design that leaves no hidden costs behind:

    • Complete 3-Month Tuition: Fee to be discussed
    • Premium PDF Notes Included: Exhaustive, chapter-wise digital summaries, ready for offline reading.
    • Dedicated Doubt Resolution: Zero unanswered queries with 24/7 forum support and live Q&A intervals.

    πŸ“ Secure Your Spot Immediately!

    Seats for Batch-2 are strictly capped to ensure personalized attention and optimal doubt resolution for every student. Don’t risk exhausting your limited attempts.

    πŸ‘‰ Click Here to Access the Official Google Registration Form and Enroll Now: CBLR Batch Enrollment Form

    How Advocate Ravi Shekhar Jha & Treximerce Train Candidates to Master the CBLR 2027 Exam Framework

    Through a powerful blend of courtroom litigation experience and cutting-edge trade intelligence, Advocate Ravi Shekhar Jha and Treximerce are fundamentally rewriting how candidates prepare for and ace the CBLR 2027 Examination.

    This unique preparation ecosystem divides your study strategy into two highly effective pillars: the mastery of law and the simplifying of trade execution. While Advocate Ravi Shekhar Jha will personally train candidates on the core letter of the law, unpacking complex legal statutes, judicial precedents, and litigation pitfalls, the Trade Companion tool by Treximerce will help them understand the complexities of trade in the most simplified way ever built for the trade.

    Their combined methodology dismantles overwhelming study blocks by training aspiring Customs Brokers to master the technical intricacies of the General Rules of Interpretation (GIR), Chapter Notes, and strict CAROTAR 2020 legal triggersβ€”all of which form the highest-yielding segments of the official NACIN written syllabus.

    By transforming raw legal principles into actionable operational workflows, this training empowers candidates to spot high-risk tariff anomalies and execute precise HSN vetting seamlessly. This strategy is specifically designed to eliminate the risk of critical errors, effectively killing negative marking risks in the MCQ paper and building bulletproof confidence for the practical board interview.

    To bridge the gap between classroom theory and real-world exam application, every candidate receives complimentary, unrestricted access to the powerful Treximerce Trade Companion product for a period of 3 weeks only, giving them the ultimate operational edge needed to clear both the CBLR written exam and the final Viva Voce.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Download the Advertisement Notice for Customs Brokers Examination, 2027

    Sister Concern: www.sjexim.services/

    Tech Partners: www.treximerce.com

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi

  • Compilation of Judicial Decisions on Indian Intellectual Property Rights

    Compilation of Judicial Decisions on Indian Intellectual Property Rights

    Date: 29.08.2026

    India’s intellectual property (IP) regime continues to evolve rapidly, with courts issuing pivotal judgments that clarify, reinforce, and sometimes reshape the legal landscape. This article presents a detailed review of the most significant judicial decisions from July 2026, as compiled by the Office of the Controller General of Patents, Designs & Trade Marks. The focus spans patents, copyrights, designs, and trademarks, offering insights for practitioners, businesses, and scholars alike.

    Patents: Defining Inventive Step, Product Claims, and Exclusions

    1. Pharmaceutical Combinations and Section 3(d) Bar

    • Case: ARRAY BIOPHARMA INC v. Deputy Controller of Patents and Designs
    • Key Takeaway: The Delhi High Court clarified that a product claim for a combination of distinct active drugs is not barred by Section 3(d) of the Patents Act. The court emphasized that such combinations, when supported by clinical data showing technical advancement, are patentable even if the specification includes administration schedules. The decision also reinforced that product claims should not be rejected as β€œmethods of treatment” merely due to functional descriptors in the claims.

    2. Inventive Step and Reasoned Orders

    • Case: DEEPAK NITRITE LIMITED v. Assistant Controller General of Patents and Designs
    • Key Takeaway: The Bombay High Court set aside a patent rejection for lack of a reasoned order. The court held that patent office decisions must be based on clear, substantiated reasoning, especially when relying on β€œcommon general knowledge.” The inventive step must be assessed holistically, considering the integrated process and technical advancement.

    3. Therapeutic Efficacy in Pharmaceutical Patents

    • Case: INTRA-CELLULAR THERAPIES, INC. v. Controller of Patents
    • Key Takeaway: The court reaffirmed that increased bioavailability or improved physicochemical properties alone do not satisfy Section 3(d) unless there is evidence of enhanced therapeutic efficacy. The applicant must demonstrate a corresponding improvement in medical outcomes.

    4. Obviousness and Prior Art

    • Case: SULZER MIXPAC AG v. Assistant Controller of Patents and Designs
    • Key Takeaway: Minor modifications of known techniques, even if they improve performance, are not patentable unless they represent a non-obvious technical advance. The court clarified that the substance of the inventive step inquiry is more important than strict adherence to judicial formulas.

    5. Mental Acts and Patent Exclusions

    • Case: T-MOBILE INTERNATIONAL AG AND CO. KG. v. Controller General of Patents, Designs and Trademarks
    • Key Takeaway: The Delhi High Court issued guidelines for assessing exclusions under Section 3(m), clarifying that claims must be evaluated as a whole. Exclusions target purely abstract or mental acts, not technical implementations involving tangible outputs.

    Copyright: Fair Dealing, Moral Rights, and Digital Challenges

    1. AI Training and Fair Dealing

    • Case: ANI MEDIA Pvt. Ltd. vs. OPEN AI OPCO LLC
    • Key Takeaway: The Delhi High Court held that using copyrighted works for AI training can qualify as fair dealing under Section 52(1)(a), provided the use is internal, non-commercial, and does not result in substantial reproduction. The court recognized the evolving nature of β€œresearch” in the digital age.

    2. Artistic Work and Trade Dress

    • Case: OPELLA HEALTHCARE GROUP v. PURECA LABORATORIES PVT LTD
    • Key Takeaway: The court granted summary judgment against a defendant whose label was a colourable imitation of the plaintiff’s well-known packaging, reinforcing the protection of trade dress as artistic work.

    3. Moral Rights and AI Deepfakes

    • Case: PREITY G. ZINTA v. GOOGLE LLC & ORS.
    • Key Takeaway: Unauthorized creation and dissemination of AI-generated deepfakes and morphed content violate a performer’s moral rights under Section 38-B, justifying urgent injunctive relief.

    4. Ownership of Musical Works

    • Case: SAREGAMA INDIA LTD. V. BLACK MADRAS FILMS & ORS.
    • Key Takeaway: Copyright in musical compositions is distinct from sound recordings and cinematograph films; composers retain rights in their works even when incorporated into films.

    Designs: Novelty and Litigation Costs

    1. Design Infringement and Prior Publication

    • Case: CROCS INC USA V. M/S BATA INDIA LTD AND ORS.
    • Key Takeaway: Lack of novelty and prior publication can invalidate a registered design. Successful defendants are entitled to recover actual litigation costs, emphasizing the need for parties to assess the strength of their case before pursuing litigation.

    Trademarks: Well-Known Marks, Passing Off, and Procedural Safeguards

    1. Well-Known Marks and Cross-Class Protection

    • Case: COLUMBIA PICTURES INDUSTRIES, INC v. REGISTRAR OF TRADE MARKS & ANR
    • Key Takeaway: A mark need not be formally declared “well-known” to claim cross-class protection; evidence of reputation and recognition is sufficient. The Registrar must consider well-known status claims before focusing on goods’ dissimilarity.

    2. Priority of Application vs. Actual Use

    • Case: Parle Products Pvt. Ltd. v. The Registrar of Trade Marks & Anr.
    • Key Takeaway: In registration disputes, the date of application determines priority, not the date of first use, unless the dispute involves passing off. Administrative delays by the Registry cannot penalize diligent applicants.

    3. Deceptive Similarity in Pharmaceuticals

    • Case: SUN PHARMA LABORATORIES LTD. v. FINECURE PHARMACEUTICALS LTD. & ORS
    • Key Takeaway: Even minor differences in pharmaceutical trademarks can cause confusion; public interest justifies a stricter approach to similarity. Delay in seeking relief does not defeat an injunction in such cases.

    4. Restoration and Procedural Compliance

    • Cases: ARUN KUMAR GUPTA V. REGISTRAR OF TRADE MARKS and AMRIT SINGH MEHTA TRADING AS MEHTA COSMETICS V. CONTROLLER GENERAL OF PATENTS, DESIGNS AND TRADE MARKS
    • Key Takeaway: Removal of a trademark for non-renewal is invalid without issuing the mandatory renewal notice; procedural safeguards protect proprietors’ rights.

    Conclusion

    The July 2026 judicial decisions underscore the Indian judiciary’s nuanced approach to balancing innovation, public interest, and procedural fairness in IP law. Stakeholders should closely monitor these developments to ensure compliance and to leverage evolving legal standards in protecting their intellectual property.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi

  • Suspension of Sentence Granted to NDPS Convict Pending Appeal: High Court of Gujarat Allows Bail Citing Procedural Lapses and Delay in Hearing

    Suspension of Sentence Granted to NDPS Convict Pending Appeal: High Court of Gujarat Allows Bail Citing Procedural Lapses and Delay in Hearing

    Date: 29.08.2026

    In a significant development, the High Court of Gujarat at Ahmedabad granted suspension of sentence to Pravinkumar Balvantram Vana (Bishnoi), who was convicted under Sections 8(c), 22(c), and 29 of the Narcotic Drugs and Psychotropic Substances (NDPS) Act. The conviction, delivered by the Special (NDPS) Judge & 10th Additional Sessions Judge, Surat, sentenced the applicant to 10 years of rigorous imprisonment and a fine of Rs. 1,00,000, with an additional year of imprisonment in case of default in payment.

    Grounds for Suspension of Sentence

    The applicant, through his legal counsel, sought suspension of sentence on several grounds:

    1. Substantial Sentence Already Served: The applicant had already undergone over 3 years and 4 months of incarceration out of the total 10-year sentence.
    2. Delay in Appeal Hearing: The criminal appeal was admitted recently, and there were remote chances of it being heard in the near future.
    3. Compliance with Legal Provisions: The defense argued that the mandatory provisions of Section 50 of the NDPS Act were not properly complied with during the investigation.
    4. Willingness to Pay Fine: The applicant expressed readiness to deposit the fine imposed by the trial court.

    Arguments Presented

    • For the Applicant: The defense emphasized the fixed-term nature of the sentence, the significant portion already served, and the lack of compliance with mandatory legal procedures. Reliance was placed on Supreme Court judgments advocating liberal consideration for suspension of sentence in fixed-term cases, especially when appeals are unlikely to be heard soon.
    • For the State: The prosecution opposed the application, citing the seriousness of the offense and the evidence establishing the applicant’s complicity. The State argued that the trial court had properly appreciated both ocular and documentary evidence before convicting the applicant.

    Court’s Observations and Reasoning

    The Court carefully reviewed the evidence and legal precedents, noting:

    • The incident occurred in 2021, and the applicant had already served a significant portion of the sentence.
    • There was a prima facie violation of Section 50 of the NDPS Act, which mandates certain procedural safeguards during search and seizure.
    • Supreme Court judgments (including Bhagwan Rama Shinde Gosai v. State of Gujarat and others) support the suspension of sentence in cases where the appeal is unlikely to be heard before the sentence is completed.
    • The applicant had no antecedents and had already undergone more than 40% of the sentence.

    Court’s Decision

    Based on the above, the Court ruled in favor of the applicant, suspending the sentence pending the final hearing of the appeal. The applicant was ordered to be released on bail upon furnishing a bond of Rs. 15,000 with one surety of the like amount, subject to several conditions:

    1. Not to misuse liberty or leave Gujarat without court permission.
    2. To provide and not change residential address without permission.
    3. To cooperate with the appeal process and mark monthly presence at the local police station.
    4. To deposit the fine within four weeks.

    Significance of the Ruling

    This judgment underscores the judiciary’s approach to balancing the rights of convicts with the practical realities of delayed appellate hearings. It reiterates the principle that fixed-term convicts should not be unduly deprived of their liberty due to systemic delays, provided there are no exceptional circumstances or statutory bars.

    The case also highlights the importance of strict compliance with procedural safeguards under the NDPS Act, as lapses can significantly impact the outcome of post-conviction relief applications.

    This decision serves as a reference point for similar cases where convicts seek suspension of sentence during the pendency of their appeals, especially in the context of lengthy sentences and delayed hearings.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi

  • CESTAT Chandigarh Clarifies Classification of Aluminum Profiles for Solar Panel Manufacturing

    CESTAT Chandigarh Clarifies Classification of Aluminum Profiles for Solar Panel Manufacturing

    Date: 29.08.2026

    Saatvik Green Energy Limited, a leading manufacturer of solar photovoltaic modules, recently secured a significant victory before the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) Chandigarh. The case revolved around the customs classification and duty assessment of imported aluminum profiles used in solar panel manufacturingβ€”a dispute with far-reaching implications for the renewable energy sector and importers of industrial components.

    Background: The Dispute Over Aluminum Profiles

    Saatvik Green Energy imported β€œAluminum Hollow Profiles” for use in manufacturing solar PV modules. These were declared under Customs Tariff Item (CTI) 76042100, which covers aluminum bars, rods, and profiles of aluminum alloys (hollow profiles). However, the commercial invoices described the goods as β€œAluminum Solar Frame.” Saatvik claimed that these profiles underwent substantial processing before being incorporated into finished solar modules.

    The Customs Department, after an audit, argued that the goods should be classified under CTH 76169990 (other articles of aluminum), not as hollow profiles. This reclassification would attract a higher basic customs duty (BCD) and deny the benefit of concessional duty under Notification No. 24/2005-Cus. The department issued a show cause notice demanding differential duty of nearly Rs. 6 crore, along with interest, penalties, and a hefty redemption fine.

    Key Legal Issues Examined

    The Tribunal considered several critical questions:

    1. Correct Classification: Should the imported goods be classified as hollow profiles (CTI 76042100) or as finished aluminum frames (CTH 76169990)?
    2. Eligibility for Duty Exemption: Was Saatvik entitled to the concessional duty benefit under Notification No. 24/2005-Cus for goods used in manufacturing solar PV modules?
    3. Applicability of Extended Limitation Period: Could the department invoke the extended period for demanding duty in a bona fide classification dispute?
    4. Sustainability of Penalties and Fines: Were confiscation, redemption fine, and penalties justified?

    Tribunal’s Analysis and Findings

    1. Classification Must Reflect Goods as Imported

    The Tribunal emphasized that classification should be based on the goods’ objective characteristics at the time of importβ€”not their intended use or commercial description. The mere labeling of goods as β€œAluminum Solar Frame” in invoices was not conclusive. The Tribunal found:

    • The imported profiles, though cut to size, retained the essential character of hollow profiles.
    • Cutting profiles to shorter lengths is a standard industry practice and does not transform them into finished articles.
    • There was no evidence that the goods had become complete frames or articles of aluminum at the time of import.

    2. Specific vs. Residual Tariff Headings

    The Tribunal reiterated that a specific tariff heading (CTI 76042100 for profiles) prevails over a residual heading (CTH 76169990 for other articles of aluminum). Since the goods fit the definition of profiles, they could not be classified under the more general heading.

    3. Eligibility for Duty Exemption

    Saatvik had followed all procedural requirements for concessional duty, including providing end-use certificates. The Tribunal held that the exemption under Notification No. 24/2005-Cus was available for goods used in manufacturing solar PV modules, regardless of their precise classification within Chapter 76, as long as the end-use condition was satisfied.

    4. No Grounds for Penalties or Extended Limitation

    The Tribunal found no evidence of willful misstatement, suppression, or fraud. The dispute was purely interpretational. Therefore, extended limitation, penalties, and redemption fines were not sustainable.

    Final Order and Impact

    The CESTAT set aside the Commissioner’s order, holding:

    • The goods are classifiable under CTI 76042100 (aluminum hollow profiles).
    • Saatvik is eligible for the concessional duty benefit for imports made before 1 April 2022 (when the notification was amended).
    • All penalties, fines, and demands were quashed.

    This ruling provides clarity for importers of industrial components, especially in the renewable energy sector, reinforcing the principle that classification must be based on the goods’ condition at importβ€”not on commercial labels or intended use. It also underscores the importance of following procedural requirements to avail duty exemptions.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi

  • Supreme Court Affirms Acquittal Under Sections 8/18(B) and 29 of the Narcotic Drugs and Psychotropic Substances Act, 1985

    Supreme Court Affirms Acquittal Under Sections 8/18(B) and 29 of the Narcotic Drugs and Psychotropic Substances Act, 1985

    Date: 27.08.2026

    The Supreme Court of India, in a significant judgment, upheld the acquittal of Jarooparam, who was charged under the Narcotic Drugs and Psychotropic Substances Act, 1985 (NDPS Act). This article provides a comprehensive overview of the case, the legal issues involved, and the reasoning behind the Court’s decision.

    Background of the Case

    On May 11, 2004, law enforcement authorities intercepted Jarooparam and two others at Bhilkhanda Square, seizing 7.2 kg of opium from their possession. The authorities prepared two samples of 30 grams each from the seized material and marked them for evidence. Jarooparam was arrested, and a complaint was filed under Sections 8/18 and 29 of the NDPS Act. The trial court convicted him, sentencing him to ten years of rigorous imprisonment and a fine of Rs. 1,00,000.

    High Court Proceedings

    Jarooparam appealed to the High Court of Madhya Pradesh, which acquitted him. The High Court found several procedural lapses:

    1. Improper Disposal of Seized Property: The bulk quantity of opium was not disposed of by the Executive Magistrate as required by law. Instead, after sampling, the remaining contraband was returned to the investigating officer without proper judicial authorization or documentation.
    2. Doubtful Evidence Handling: The prosecution failed to produce the bulk quantity of opium during the trial, raising doubts about the authenticity of the samples presented as evidence.
    3. Questionable Confessional Statement: The accused’s confession under Section 67 of the NDPS Act was recorded while he was in police custody, and there were allegations that his signature was obtained on blank papers. The High Court found this confession unreliable.
    4. Hostile Witnesses: Independent witnesses presented by the prosecution turned hostile, further weakening the case.

    Supreme Court’s Analysis and Judgment

    The Union of India appealed the High Court’s acquittal to the Supreme Court. After reviewing the case, the Supreme Court concurred with the High Court’s findings, emphasizing the following points:

    • Mandatory Compliance with Section 52A NDPS Act: The law requires that seized narcotics be disposed of only after a Magistrate’s order. In this case, there was no such order or application for disposal, and the prosecution failed to explain the fate of the bulk contraband.
    • Evidentiary Gaps: The absence of the bulk opium at trial and the lack of proper documentation undermined the prosecution’s case. The Court noted that the destruction or disposal of evidence must be properly authorized and documented to maintain the chain of custody and evidentiary value.
    • Unreliable Confession: The confession was not considered voluntary, as it was obtained while the accused was in custody and without proper safeguards.

    Final Outcome

    The Supreme Court dismissed the appeal by the Union of India, affirming the acquittal of Jarooparam. The Court highlighted the importance of strict procedural compliance in narcotics cases, given the severe penalties involved.

    Key Takeaways

    1. Strict Adherence to Procedure: Law enforcement must strictly follow procedures for seizure, sampling, and disposal of narcotics to ensure the integrity of evidence.
    2. Judicial Oversight: Disposal or destruction of seized contraband must be authorized by a competent court, with proper documentation and notice to the accused.
    3. Voluntariness of Confession: Confessions obtained in custody without safeguards are likely to be disregarded by courts.
    4. Role of Independent Witnesses: Hostile or unreliable witnesses can significantly weaken the prosecution’s case.

    This judgment serves as a reminder of the critical role of due process and evidentiary safeguards in criminal prosecutions under the NDPS Act.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi