Tag: #Advocate

  • Supreme Court on Bail, Sureties, and Drug Trafficking

    Supreme Court on Bail, Sureties, and Drug Trafficking

    Date: 18.08.2026

    This article provides a comprehensive overview of a recent Supreme Court judgment that addresses critical issues in criminal justice, particularly concerning bail, surety verification, and the handling of foreign nationals accused under the Narcotic Drugs and Psychotropic Substances Act (NDPS Act). The judgment not only resolves the specific case at hand but also sets out far-reaching guidelines and suggestions for systemic reform.

    Background of the Case

    The case involved the Union of India appealing against the grant of bail to a foreign national accused of masterminding a drug trafficking operation involving a commercial quantity of heroin. The accused, previously convicted in a similar case, was released on bail after furnishing sureties. However, subsequent investigations revealed that the sureties were fake, and the accused absconded, highlighting systemic vulnerabilities in the bail and surety process.

    Key Legal Issues Addressed

    1. Bail Under Special Statutes

    • NDPS Act, PMLA, and UAPA: The judgment analyzes the stringent bail provisions under the NDPS Act, Prevention of Money Laundering Act (PMLA), and Unlawful Activities Prevention Act (UAPA), emphasizing the “twin conditions” for bail in NDPS cases involving commercial quantities.
    • Article 21 Considerations: While upholding statutory rigour, the Court reiterates that prolonged incarceration without trial can violate the right to personal liberty under Article 21 of the Constitution.

    2. Bail for Foreign Nationals

    • Principle: Foreign nationals are entitled to Article 21 protection, but the State retains the power to regulate and restrict their movement.
    • Special Conditions: The Court affirms that bail conditions for foreign nationals may include surrender of passports, registration with authorities, and restrictions on travel, provided these are reasonable and proportionate.

    3. The Problem of Fake Sureties

    • Systemic Weakness: The case exposed how fake sureties enable accused persons, especially foreign nationals, to abscond, undermining the justice system.
    • Verification Gaps: Despite existing procedures, lack of robust verification and accountability allows professional sureties and touts to exploit the system.

    Data and Trends Highlighted

    • Rising Drug Offences: NDPS cases have nearly doubled between 2018 and 2023, with a significant number involving foreign nationals, particularly from Nigeria, Bangladesh, and Nepal.
    • Fake Sureties: At least 47 foreign nationals are currently absconding after furnishing fake sureties, with the problem being widespread across several states.

    Supreme Court’s Directions and Guidelines

    The Court, invoking its powers under Article 142, issued binding directions for all cases involving foreign nationals accused under the NDPS Act for commercial quantities:

    1. Mandatory Deposit of Passport: Accused must deposit their passport with the court; travel restrictions may be imposed.
    2. Registration with FRRO: Accused must register with the Foreigners Regional Registration Office within one week of release.
    3. Production of Two Sureties: Two genuine, verified sureties are required, with exceptions only for documented hardship.
    4. Surety Verification: Police and court officials must verify surety credentials within three days before release.
    5. Lien on Surety Property: A lien/charge is to be created on the surety’s property, enforceable in case of bail violation.
    6. Centralized Database: The Ministry of Law and Justice and NIC must create a national database of accused and sureties in NDPS cases involving foreign nationals.
    7. Departmental Action: Officials responsible for verifying fake sureties will face departmental inquiry.
    8. Affidavit of Income: Accused must file an affidavit disclosing sources of income and bank accounts in India.
    9. Embassy Notification: Investigating officers must inform the accused’s embassy of the criminal proceedings.
    10. Digital Verification Portals: High Courts are to implement digital portals for speedy verification of surety documents.

    Suggestions for Systemic Reform

    • Professional Bail Bondsperson Regulation: The Court annexed draft rules for licensing and regulating professional bail bondspersons, aiming to curb the menace of fake sureties and touts.
    • Training and Awareness: Judicial academies are to train judges on the socio-economic impact of surety-based bail and access to justice for indigent undertrials.
    • Technological Integration: Suggestions include using Aadhaar authentication, geo-fencing, and centralized digital systems for real-time verification and monitoring.

    Comparative International Perspective

    The judgment draws on practices from the US, Canada, Singapore, and Australia, noting that robust verification, regulated professional sureties, and digital tracking are common features in advanced legal systems.

    Impact and Significance

    This judgment is a watershed moment for criminal justice reform in India, especially in the context of transnational crime and the rights of foreign nationals. By mandating stricter verification, digital integration, and accountability, the Supreme Court aims to balance the rights of the accused with the imperative of public safety and the integrity of the justice system.

    The directions and suggestions, if implemented, promise to make the bail and surety process more transparent, accountable, and resistant to abuse, setting a new standard for handling serious offences involving foreign nationals.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Authenticity of Country of Origin Certificates, Preferential Duty Exemption, and Customs Valuation Dispute

    Authenticity of Country of Origin Certificates, Preferential Duty Exemption, and Customs Valuation Dispute

    Date: 18.08.2026

    The Customs, Excise & Service Tax Appellate Tribunal (CESTAT) Allahabad recently delivered a significant judgment in the case of M/s SSN Steel Impex, a New Delhi-based importer and trader of stainless steel products. The case revolved around the denial of preferential customs duty benefits, allegations of unauthentic Country of Origin (COO) certificates, undervaluation of goods, and imposition of penalties. This article provides a detailed analysis of the case, the Tribunal’s findings, and its broader implications for importers and customs administration in India.

    Background of the Case

    M/s SSN Steel Impex imported stainless steel cold rolled sheets, coils, and circles, primarily from Malaysia, to avail preferential duty benefits under Notification No. 46/2011-Cus (ASEAN-India Free Trade Agreement). The customs authorities alleged that many COO certificates submitted by the appellant were unauthentic, leading to the denial of duty exemption and the imposition of differential duty, interest, and penalties. The appellant challenged these actions, arguing that due process was not followed and that most COOs were genuine.

    Key Issues Examined

    1. Authenticity of COO Certificates
      • Customs authorities, based on communications from Malaysia’s MITI, claimed that 87 out of 143 COOs were unauthentic.
      • SSN Steel Impex submitted 38 COOs; only one was found unauthentic, for which the company had already paid the differential duty.
      • The Tribunal found that the remaining 37 COOs were not listed as unauthentic and thus should be accepted.
    2. Eligibility for Preferential Duty
      • The Tribunal held that since the majority of COOs were authentic and verified at the time of import, the appellant was eligible for duty exemption under Notification No. 46/2011-Cus.
      • The Tribunal emphasized that subsequent communications from MITI could not retroactively invalidate COOs that were valid and verified at the time of import.
    3. Allegations of Undervaluation
      • Customs authorities alleged undervaluation based on statements from third parties and price comparisons.
      • The Tribunal found no evidence that SSN Steel Impex paid amounts over and above the declared invoice prices or that the declared values were not at arm’s length.
      • The Tribunal relied on Supreme Court precedents, holding that transaction values could not be rejected without concrete evidence.
    4. Imposition of Penalties
      • Penalties were imposed for alleged mis-declaration and undervaluation.
      • The Tribunal found no evidence of intent to evade duty or collusion and set aside all penalties.

    Tribunal’s Final Order

    The CESTAT Allahabad ruled in favor of SSN Steel Impex, with the following key directives:

    • All 37 COOs (except the one already settled) were deemed authentic and acceptable.
    • The appellant was entitled to the benefit of duty exemption for all consignments covered by these COOs.
    • The declared transaction values were accepted; the enhanced values determined by customs were set aside.
    • All penalties imposed on the appellant were quashed.

    Legal Precedents and Principles Affirmed

    • Due Process: The Tribunal reiterated the importance of natural justice, including the right to cross-examination and proper consideration of evidence.
    • Finality of Assessment: Once goods are assessed and cleared based on valid documents, subsequent doubts cannot retroactively deny benefits unless clear evidence emerges.
    • Burden of Proof: The onus is on customs authorities to provide concrete evidence for allegations of mis-declaration or undervaluation.

    Implications for Importers and Customs Administration

    1. Reliance on Valid COOs: Importers can rely on COOs issued and verified by competent authorities at the time of import, unless there is clear evidence of fraud or forgery.
    2. Protection Against Retroactive Actions: Subsequent communications or doubts from foreign authorities cannot, by themselves, invalidate benefits already granted unless accompanied by formal revocation or evidence.
    3. Importance of Documentation: Importers should maintain comprehensive records of all import documents, including COOs, invoices, and customs clearances.
    4. Customs’ Investigative Standards: Customs authorities must adhere to due process and provide substantive evidence before denying benefits or imposing penalties.

    Conclusion

    The CESTAT Allahabad’s decision in the SSN Steel Impex case sets a strong precedent for the protection of importers’ rights and the importance of procedural fairness in customs adjudication. It underscores the need for robust evidence and adherence to natural justice before denying statutory benefits or imposing penalties. This ruling will likely influence future disputes involving preferential duty claims and the authenticity of COO certificates in India.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Supreme Court Clarifies Extended Limitation in Excise Valuation for Motor Vehicle Body Building

    Supreme Court Clarifies Extended Limitation in Excise Valuation for Motor Vehicle Body Building

    Date: 18.08.2026

    The Supreme Court of India recently delivered a significant judgment in the case of Audi Automobiles & Ors. vs. Commissioner of Central Excise and Service Tax, Indore, addressing the applicability of the extended period of limitation under Section 11A of the Central Excise Act, 1944, in disputes involving the valuation and assessment of motor vehicle chassis and body-building services.

    Background of the Case

    Audi Automobiles and other appellants are engaged in the business of body building for motor vehicles on a job work basis. Manufacturers supply them with chassis, on which the body is built. The excise duty on the chassis is paid by the manufacturer at 110% of the cost of manufacture, as per Rule 8 of the Central Excise Valuation Rules, 2000. Once the body is built, the completed vehicle is returned to the manufacturer, and excise duty is computed by the job worker on the total value, including the cost of raw materials, job work charges, and profit.

    A dispute arose regarding whether the 10% profit margin (included in the 110% valuation of the chassis) should also be included in the assessable value when the job worker clears the completed vehicle. The Department issued a Show Cause Notice (SCN) demanding duty for the period 01.11.2004 to 31.03.2007, invoking the extended limitation period under Section 11A.

    Key Legal Issues

    1. Valuation of Completed Motor Vehicles
      • The core issue was whether the 10% profit margin, already included in the chassis valuation, should be added again when computing the assessable value of the completed vehicle.
      • The Supreme Court referred to earlier landmark decisions (such as Ujagar Prints and Eicher Motors) and clarified that the value of the completed vehicle must include the full value of the chassis (including the 10% margin), the cost of raw materials, job work charges, and the job worker’s profit. However, profits made by the manufacturer after receiving the completed vehicle are not to be included.
    2. Applicability of Extended Limitation under Section 11A
      • The Department sought to invoke the extended limitation period, alleging suppression of facts by the assessee.
      • The Court emphasized that for the extended period to apply, there must be a wilful suppression or misstatement with intent to evade duty. Mere omission or non-inclusion, when facts are known to both parties, does not amount to suppression.
      • In this case, since the Department was aware of the valuation method and the 10% margin, the invocation of the extended limitation was not justified.

    Supreme Court’s Decision

    • The Supreme Court set aside the orders of the Tribunal and lower authorities, holding that the demand raised by the Department was time-barred as the SCN was issued beyond the one-year limitation period.
    • The Court reaffirmed that the assessee’s liability to include the entire cost price (including the 10% margin) in the assessable value is correct, but the demand for the subject period could not be sustained due to limitation.

    Implications of the Judgment

    1. Clarity on Valuation: The judgment provides clear guidance on how to compute the assessable value for motor vehicles built on job work basis, ensuring that the 10% profit margin included in the chassis valuation is not omitted.
    2. Limitation Safeguards: The decision reinforces the principle that the extended limitation period under Section 11A can only be invoked in cases of wilful suppression or fraud, protecting assessees from arbitrary and delayed demands.
    3. Precedent for Similar Cases: This ruling will serve as a precedent for future disputes involving valuation and limitation in excise matters, especially in job work scenarios.

    Conclusion

    The Supreme Court’s judgment in the Audi Automobiles case brings much-needed clarity to the valuation of motor vehicles in body-building job work and sets strict standards for invoking the extended limitation period under the Central Excise Act. This ensures fairness and legal certainty for both the industry and the tax authorities.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Supreme Court on Section 311 Cr.P.C.: Limits of Recalling Witnesses and Ensuring Fair Trial

    Supreme Court on Section 311 Cr.P.C.: Limits of Recalling Witnesses and Ensuring Fair Trial

    Date: 17.08.2026

    This article provides a comprehensive overview and analysis of the Supreme Court of India’s judgment in the case of Rajaram Prasad Yadav vs. State of Bihar & Anr., focusing on the application and interpretation of Section 311 of the Code of Criminal Procedure (Cr.P.C.) regarding the re-examination of witnesses.

    Background of the Case

    1. Incident and Initial Proceedings
      • The dispute arose from a conflict over the construction of a latrine, leading to an alleged shooting incident on July 7, 1999.
      • The complainant (PW-9) initially accused the appellant, Rajaram Prasad Yadav, of firing at him. However, during his court testimony, PW-9 retracted his allegations, stating the injury was accidental.
      • The prosecution closed its evidence, and the defense began presenting its case.
    2. Subsequent Developments
      • A further altercation led to another police case, after which PW-9 sought re-examination under Section 311 Cr.P.C., claiming his earlier testimony was given under duress.
      • The trial court rejected the application for re-examination, citing lack of immediate complaint about coercion and the absence of ambiguity in the original testimony.
      • The High Court, however, allowed the re-examination, prompting the appellant to approach the Supreme Court.

    Legal Issues and Arguments

    Section 311 Cr.P.C. and Section 138 Evidence Act

    • Section 311 Cr.P.C. empowers courts to summon or recall witnesses if their evidence is essential for a just decision.
    • Section 138 Evidence Act prescribes the order and scope of examination, cross-examination, and re-examination of witnesses.

    Appellant’s Arguments

    • The appellant argued that the High Court’s order was passed without proper hearing and allowed the prosecution to fill gaps in its case, which is not the intent of Section 311.
    • The trial court had already provided reasoned grounds for rejecting the re-examination request.

    Respondents’ Arguments

    • The respondents contended that Section 311 grants wide discretion to courts to ensure justice, including recalling witnesses if necessary.

    Supreme Court’s Analysis

    Principles for Application of Section 311 Cr.P.C.

    The Supreme Court reviewed several precedents and distilled key principles:

    1. Essentiality for Just Decision: The court must be convinced that new evidence is necessary for a just decision.
    2. Judicious Exercise of Power: The wide discretion under Section 311 must be exercised with care, not arbitrarily.
    3. Not for Filling Lacunae: The provision should not be used merely to fill gaps in a party’s case unless justice demands it.
    4. Fair Trial: The right to a fair trial is paramount, balancing the interests of the accused, victim, and society.
    5. Opportunity for Rebuttal: If additional evidence is allowed, the opposing party must have a chance to rebut.

    Application to the Present Case

    • The Supreme Court found that the trial court had properly considered all relevant factors, including the absence of any immediate complaint of coercion by PW-9 and the lack of ambiguity in his testimony.
    • The application for re-examination appeared to be an afterthought, possibly motivated by subsequent events rather than genuine concern for justice.
    • The High Court’s order was set aside, and the trial court’s decision was restored.

    Key Takeaways for Legal Practice

    1. Section 311 Cr.P.C. is a Safeguard, Not a Loophole
      • Courts have broad powers to recall or re-examine witnesses, but this must be done to serve justice, not to allow parties to mend their cases opportunistically.
    2. Timeliness and Credibility Matter
      • Applications for re-examination must be supported by credible reasons and made promptly. Delayed claims of coercion or error are viewed with skepticism.
    3. Fairness and Judicial Discretion
      • The judiciary must balance the need for a fair trial with the risk of prejudice to either party, ensuring that the process is not misused.

    Conclusion

    The Supreme Court’s judgment in Rajaram Prasad Yadav vs. State of Bihar & Anr. reinforces the principle that the power to recall or re-examine witnesses under Section 311 Cr.P.C. is to be exercised judiciously, with the primary aim of achieving a just decision. The decision serves as a guiding precedent for lower courts on the careful and fair application of procedural powers in criminal trials.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Delhi HC Affirms Importers’ Right to Refund of Excess Customs Duty Paid Without Assessment Order u/s 27 of Customs Act

    Delhi HC Affirms Importers’ Right to Refund of Excess Customs Duty Paid Without Assessment Order u/s 27 of Customs Act

    Date: 17.08.2026

    Aman Medical Products Ltd. found itself in a legal dispute after inadvertently paying a higher customs duty on imported goods. The company failed to claim a concessional rate available under Notification No. 6/2002 dated 1.3.2002 due to ignorance and paid the excess duty while filing the Bill of Entry. The central question was whether an importer who pays excess duty by mistake, without an assessment order or contest, can claim a refund under Section 27 of the Customs Act, 1962.

    Legal Issue

    The Customs, Excise and Service Tax Appellate Tribunal (CESTAT) had previously ruled that a refund could only be claimed if the excess duty was paid “in pursuance to an order of assessment.” According to CESTAT, without an assessment order, the importer could not seek a refund unless an appeal was filed against such an order.

    High Court’s Analysis

    The Delhi High Court, presided over by Justices A.K. Sikri and Valmiki J. Mehta, examined Section 27 of the Customs Act, 1962. The Court highlighted two key points:

    1. Alternative Grounds for Refund: Section 27(1) allows a refund claim for duty “paid by him in pursuance of an order of assessment” or “borne by him.” The use of “or” means these are alternative grounds. Thus, a refund can be claimed even if the duty was not paid under an assessment order.
    2. No Assessment Order Required: The Court clarified that if duty is paid without an assessment orderβ€”such as in cases of ignorance or inadvertenceβ€”the importer is still entitled to claim a refund under Section 27(1)(ii).

    The Court distinguished this case from earlier Supreme Court judgments (CCE, Kanpur v. Flock (India) Pvt. Ltd. and Priya Blue Industries Ltd. v. Commissioner of Customs), noting that those cases involved a formal assessment order and a failure to appeal, which was not the situation here.

    Judgment and Outcome

    The High Court set aside the CESTAT’s order and upheld the order of the Commissioner of Customs (Appeal). The matter was remanded to the Deputy Commissioner of Customs (Refund) to examine the merits of Aman Medical Products Ltd.’s refund claim. The Court confirmed that the company’s claim was maintainable under Section 27 of the Customs Act, even without an assessment order or a prior appeal.

    Key Takeaways

    1. Importers’ Rights: Importers who pay excess customs duty by mistake, without an assessment order, can claim a refund under Section 27(1)(ii) of the Customs Act.
    2. No Appeal Requirement: The absence of an appeal against the Bill of Entry does not bar the importer from seeking a refund.
    3. Legal Clarity: The judgment clarifies the scope of Section 27, ensuring that procedural technicalities do not prevent genuine refund claims.

    This decision strengthens the rights of importers and provides clear guidance on the interpretation of refund provisions under Indian customs law.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Permissibility of Introducing Late-Stage Documentary Evidence in Criminal Proceedings

    Permissibility of Introducing Late-Stage Documentary Evidence in Criminal Proceedings

    Date: 14.08.2026

    A recent judgment by the Delhi High Court has provided significant clarity on the admissibility of late-stage documentary evidence in criminal proceedings, particularly in cases involving promissory notes and alleged cheque dishonour under Section 138 of the Negotiable Instruments Act, 1881 (NI Act). The case, SRS Infratech Pvt Ltd & Anr. vs. Kumud Chaudhary & Ors., addresses the scope of Section 311 of the Code of Criminal Procedure, 1973 (CrPC), and the rights of parties to introduce and challenge evidence during trial.

    Case Background

    The dispute originated from a complaint by Late Shyam Chaudhary, who alleged that SRS Infratech Pvt Ltd had availed a loan of Rs. 25 lakhs, supported by a loan agreement and a promissory note dated 16.11.2009. After the complainant’s death, his legal representatives continued the proceedings. The petitioners (SRS Infratech and its representative) denied the loan transaction, claiming the cheque was issued as security for a property deal that never materialized.

    Key Legal Issues

    1. Introduction of New Evidence:
      • During the defence stage, the respondents sought to introduce a promissory note that had not been previously placed on record, claiming it was discovered after the complainant’s death.
      • The trial court allowed the recall of a witness (Ms. Kavita Chowdhary) under Section 311 CrPC to introduce the promissory note.
    2. Petitioners’ Objections:
      • The petitioners argued that introducing the promissory note at a late stage was impermissible, especially after the defence had been disclosed.
      • They contended that the application was an attempt to fill gaps in the respondents’ case and amounted to a review of an earlier withdrawn application, which is barred by Section 362 CrPC.
      • They also argued that the document’s genuineness was disputed, and thus it could not be admitted without formal proof under Section 294(3) CrPC.

    Court’s Analysis and Findings

    1. Scope of Section 311 CrPC

    The Court emphasized that Section 311 CrPC grants wide powers to recall or summon witnesses at any stage if their evidence is essential for a just decision. The provision is not limited by the stage of proceedings, provided the evidence is germane to the controversy and the opposing party is given a fair opportunity to rebut.

    2. Chronology and Bona Fides

    The promissory note was not introduced for the first time at the late stage; it had been sought to be placed on record earlier via an affidavit in 2020. The subsequent application aimed to recall a witness to formally introduce the document, not to fundamentally alter the case.

    3. No Absolute Bar on Late Evidence

    The Court clarified that delay alone does not bar the introduction of relevant evidence. The key consideration is whether the evidence is connected to the dispute and whether the opposing party can challenge it through cross-examination.

    4. Section 294(3) CrPC and Disputed Documents

    Section 294(3) CrPC only dispenses with formal proof if a document’s genuineness is admitted. If disputed, the party relying on the document must prove its authenticity through standard legal procedures. The marking of the promissory note as an exhibit does not establish its genuineness or admissibility.

    5. No Review under Section 362 CrPC

    The earlier application to introduce the promissory note was withdrawn, not adjudicated on merits. Thus, the subsequent application did not amount to a prohibited review.

    6. Safeguards Against Prejudice

    The petitioners retain the right to cross-examine the witness and challenge the document’s authenticity, ensuring no unfair prejudice.

    Conclusion and Implications

    The Delhi High Court dismissed the petition, allowing the promissory note to be brought on record, subject to proof and cross-examination. The judgment underscores:

    • The broad discretion courts have under Section 311 CrPC to ensure all relevant evidence is considered.
    • The importance of procedural fairnessβ€”late evidence can be admitted if the opposing party is not deprived of the opportunity to challenge it.
    • The distinction between admitting a document for evidence and accepting its genuineness or evidentiary value.

    This decision serves as a guiding precedent for similar disputes, balancing the need for comprehensive adjudication with the rights of both parties to a fair trial.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Delhi High Court Clarifies Limitation Law in Customs Refunds

    Delhi High Court Clarifies Limitation Law in Customs Refunds

    Date: 14.08.2026

    A recent batch of appeals before the Delhi High Court has brought significant clarity to the application of limitation law in customs refund cases. Senior India Pvt Ltd, a prominent importer, challenged several orders of the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) regarding the classification of imported goods and the timeliness of their refund claims. This article provides a detailed overview of the case, the legal issues involved, and the implications of the Court’s decision.

    Background of the Case

    Senior India Pvt Ltd imported pressure relief valves, which were initially classified under Customs Tariff Item (CTI) 8481 40 00. From September 2018, the company began declaring these goods under CTI 8409 99 41 and paid a higher duty, reportedly at the insistence of Customs authorities. Fourteen Bills of Entry were assessed between September 2018 and February 2019, with two additional Bills in March and May 2019.

    The legal landscape at the time, shaped by earlier Delhi High Court decisions, allowed importers to seek refunds under Section 27 of the Customs Act even if the assessment had not been appealed. Acting on this, Senior India filed two refund applications on 26 August 2019, within the statutory one-year period.

    The Turning Point: Supreme Court Judgment in ITC Limited

    While the refund proceedings were pending, the Supreme Court delivered a landmark judgment in ITC Limited v. Commissioner of Central Excise, Kolkata-IV (2019), holding that a refund claim could not be entertained unless the assessment was first modified in appeal. This fundamentally changed the legal basis for refund claims.

    Within days, Senior India sought to amend the Bills of Entry under Section 149 of the Customs Act and requested that refund proceedings be kept in abeyance. However, the refund authority rejected one claim as premature, and the company subsequently filed appeals under Section 128, seeking exclusion of the period spent on the refund process from the limitation period, invoking principles from Section 14 of the Limitation Act.

    Key Legal Issues

    The High Court focused on two main questions:

    1. Whether the authorities were justified in denying the benefit of Section 14 of the Limitation Act to Senior India, given the change in law by the Supreme Court’s ITC Limited judgment.
    2. Whether CESTAT was correct in dismissing an appeal as time-barred when the underlying appeal had been filed within the prescribed period.

    The Court’s Analysis and Findings

    • Application of Section 14 Principles: The Court recognized that while the Limitation Act does not directly apply to customs appeals, the principles underlying Section 14 (exclusion of time spent in bona fide proceedings) do apply. The Court found that Senior India had acted diligently, pursuing remedies as per the law prevailing at the time, and promptly adjusted its approach after the Supreme Court’s decision.
    • Exclusion of Time: The period during which Senior India pursued the refund remedy and sought amendment of Bills of Entry was excluded from the limitation calculation. The Court held that, due to the legal transition caused by the ITC Limited judgment, the authorities should have allowed this exclusion.
    • Statutory Extension Due to COVID-19: The Court also noted that the period for filing appeals was further extended by government notifications issued during the COVID-19 pandemic, making Senior India’s appeals timely.
    • Error in Dismissing Appeals as Time-Barred: In one case, the Court found that the appeal had been filed well within the statutory period, and its dismissal by CESTAT as time-barred was manifestly erroneous.

    Outcome and Directions

    • The High Court set aside the orders of CESTAT and the Commissioner (Appeals) that had rejected Senior India’s appeals on limitation grounds.
    • The appeals were restored for decision on merits, with instructions to the authorities not to revisit the limitation issue.
    • The Court directed that the restored appeals be decided within four months, and that refund and amendment applications be processed in accordance with the final outcome.

    Implications of the Judgment

    This decision is significant for importers and legal practitioners dealing with customs disputes:

    1. Clarifies Limitation Law: The judgment affirms that bona fide pursuit of remedies under the law as it stood can justify exclusion of time from limitation, especially when the legal position changes due to a higher court ruling.
    2. Ensures Fairness: The Court’s approach prevents penalizing parties for following the law as it existed before a judicial shift.
    3. Guidance for Future Cases: The decision provides a roadmap for handling similar disputes where refund claims or appeals are affected by changes in legal interpretation.

    Conclusion

    The Delhi High Court’s ruling in the Senior India Pvt Ltd case underscores the importance of judicial flexibility and fairness in applying limitation law, especially in the context of evolving legal standards. Importers and legal professionals should take note of this precedent when navigating refund and appeal processes under the Customs Act.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

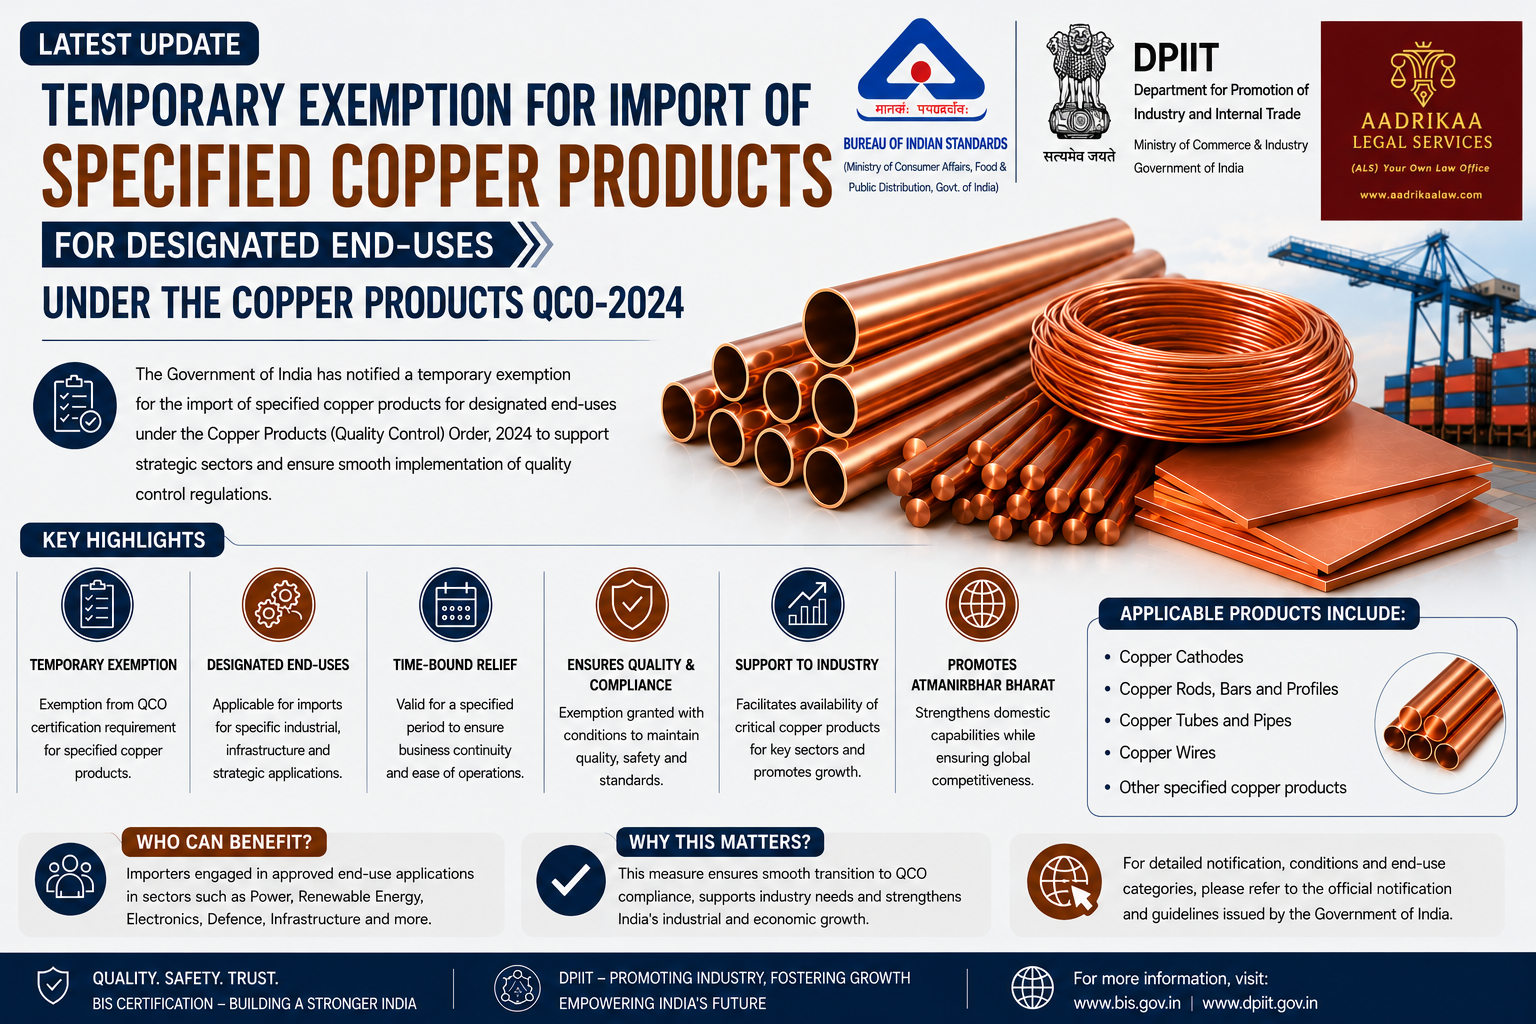
  • Temporary Exemption for Import of Specified Copper Products for Designated End-Uses under the Copper Products QCO-2024

    Temporary Exemption for Import of Specified Copper Products for Designated End-Uses under the Copper Products QCO-2024

    Date: 13.08.2026

    The Government of India has issued a significant order granting temporary exemptions for the import of specific copper products, addressing the needs of various industrial sectors. This move aims to bridge the gap between domestic supply and specialized requirements not currently met by Indian manufacturers or covered under the Copper Products (Quality Control) Order, 2024.

    Background and Rationale

    Industry stakeholders and associations highlighted challenges in sourcing certain high-purity and specialized copper products domestically, either due to lack of standards coverage or insufficient quality and quantity. Responding to these concerns, the Department for Promotion of Industry and Internal Trade (DPIIT), in consultation with the Bureau of Indian Standards (BIS), has provided a one-year exemption for select copper products, strictly for designated end-uses.

    List of Exempted Copper Products and Their End-Uses

    The exemption covers a range of copper products, each tied to a specific industrial application. Here’s a summary of the key products and their permitted uses:

    1. Oxygen Free Copper rods, bars, strips, and sheets (min. purity 99.995%, max. oxygen 5 PPM)
      • End-use: Vacuum interrupters
    2. Silver bearing Oxygen Free Copper, Zirconium Copper, High Conductivity Phosphorous-Deoxidised Copper rods, bars, and strips
      • End-use: Generator rotor coils, generators, electrical shunts
    3. Beryllium Alloy Copper Bar (End Wadge/Rotor Center Wedge-material grade)
      • End-use: Generators
    4. Oxygen Free Copper strips (min. purity 99.995%, max. oxygen 5 PPM)
      • End-use: Automotive bus bars for battery packs
    5. OFC Grade Copper Tape (0.18 mm x 81 mm and 0.095 mm x 85 mm)
      • End-use: RF feeder cables
    6. Billet & Section of Copper Alloy Grades (CuCr 90:10, CuZr 50:50, CuSi 90:10, CuP 85:15, CuTe 50:50)
      • End-use: Electrical contacts, short circuit rings, rotor bars for industrial and traction motors
    7. Copper Alloys C15000 (Zirconium Copper) and C18150 (Chromium Zirconium Copper) billets
      • End-use: Short circuit rings and rotor bars for traction and industrial motors
    8. Copper Alloy Strips (TRKFC 4, C151, DK Alloy, DSC-3N 1/2H, DK-3)
      • End-use: Bus bars for automobiles
    9. ETP Copper Plate in Coils (Grade C11000, Cu-ETP)
      • End-use: Electrical applications
    10. Hard Drawn Grooved Copper Tin alloy (150 sqmm and above, GT-SN)
      • End-use: Overhead electrical conductors
    11. Hard-Drawn Copper Wire (Dia 2.6mm, 99.9%+ purity)
      • End-use: Wiring harnesses for the automobile industry
    12. Enameled Copper Wire/Magnet Wire (0.01 to 0.16 mm, various grades)
      • End-use: Electrical wound components
    13. Copper Finned Tubes (externally and internally finned, various grades)
      • End-use: Chillers
    14. High Strength Copper Alloy Tubes (multiple grades)
      • End-use: Air-conditioning systems and electrical applications

    Conditions for Availing the Exemption

    To ensure traceability and promote future indigenization, importers must comply with the following conditions:

    1. Notification to BIS: Inform the Bureau of Indian Standards within 7 days of consignment clearance, using company letterhead and authorized signatory, via email.
    2. Quarterly Reporting: Maintain and submit quarterly records of imported goods to Central Government authorities, again on company letterhead and signed, via email.
    3. Indigenization Plan: Submit a plan for local manufacturing (indigenization) of the imported goods to the Central Government.

    Scope and Limitations

    • The exemption is valid for one year from the date of the order’s publication.
    • It applies strictly to the products and end-uses listed, and only to actual users (not traders or resellers).
    • The government reserves the right to review and amend the list of products and end-uses as needed.

    Implications for Industry

    This exemption provides immediate relief to sectors reliant on specialized copper products, such as electrical, automotive, and industrial equipment manufacturers. It also encourages importers to plan for future domestic production, aligning with the government’s broader Make in India initiative.

    For further details or compliance queries, stakeholders should contact the relevant government departments as specified in the official order.

    This proactive measure is expected to support critical industries while paving the way for enhanced domestic capabilities in the copper sector.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Delhi High Court on Territorial Jurisdiction and Framing of Charges in Alleged Rice Export Fraud

    Delhi High Court on Territorial Jurisdiction and Framing of Charges in Alleged Rice Export Fraud

    Date: 13.08.2026

    The Delhi High Court recently delivered a significant judgment in the case involving Vishal Exports Overseas Ltd. and the Central Bureau of Investigation (CBI), addressing complex issues of territorial jurisdiction and alleged financial fraud in the export of rice. This article provides a comprehensive overview of the case background, legal arguments, court findings, and the broader implications for export-related criminal proceedings in India.

    Case Background

    1. Government Policy and Export Agreement
      • The case originated from a government policy permitting the export of wheat and rice procured from the Food Corporation of India (FCI) through nominated agencies.
      • Punjab State Warehousing Corporation (PSWC) selected Vishal Exports Overseas Ltd. as an associate for exporting 5,500 MT of rice, with agreements and transactions centered in Punjab.
      • Rice was to be exported via Kandla Port, Gujarat, with supporting documents submitted to customs and banking authorities.
    2. Allegations of Fraud and Forgery
      • While most of the rice was exported as per records, allegations arose that documents for 1,167 MT of rice were forged and that this quantity was diverted to the domestic market instead of being exported.
      • The CBI initiated a preliminary enquiry in 2005, followed by an FIR in 2006, naming company officials and unknown FCI officials as accused.
    3. Legal Proceedings Timeline
      • Charge-sheet filed in 2007; subsequent supplementary charge-sheet in 2009 included the company as an accused.
      • Multiple rounds of litigation ensued, including applications for discharge, revision petitions, and challenges to the framing of charges.

    Key Legal Issues

    Territorial Jurisdiction

    • Petitioners’ Argument:
      • The entire transaction occurred in Punjab and Gujarat, not Delhi. Thus, Delhi courts lacked territorial jurisdiction.
      • Objections to jurisdiction were raised at various stages, including during arguments on charge and in discharge applications.
      • Cited several precedents emphasizing that mere filing of a charge-sheet in Delhi does not confer jurisdiction.
    • CBI’s Argument:
      • The objection was raised belatedly, after significant progress in the trial (over 15 years).
      • Section 508 of the Bharatiya Nagarik Suraksha Sanhita (BNSS), corresponding to Section 462 Cr.P.C., requires proof of a failure of justice due to lack of jurisdiction, which was not demonstrated.
      • More than half of the prosecution witnesses had already been examined, and a de novo trial would be against the interest of justice.

    Court’s Analysis and Findings

    1. Application of Section 508 BNSS
      • The court emphasized that proceedings are not to be set aside merely for being conducted in the wrong local area unless a failure of justice is shown.
      • The petitioners failed to demonstrate any prejudice or failure of justice due to the trial being conducted in Delhi.
    2. Stage of Proceedings
      • With the trial at an advanced stage and most witnesses examined, returning the case would result in unnecessary delay and repetition.
      • The court distinguished the present case from precedents cited by the petitioners, noting those involved objections raised at much earlier stages.
    3. No Infirmity in Lower Court Orders
      • The High Court found no reason to interfere with the orders of the lower courts, as the statutory requirements for setting aside proceedings on jurisdictional grounds were not met.

    Conclusion and Implications

    • The Delhi High Court dismissed the petition, upholding the continuation of proceedings in Delhi.
    • The judgment underscores the importance of raising jurisdictional objections at the earliest and demonstrating actual prejudice for relief.
    • It also highlights the court’s reluctance to disrupt advanced criminal trials on technical grounds, especially when no failure of justice is evident.

    Key Takeaways for Exporters and Legal Practitioners

    1. Early Objection is Crucial: Jurisdictional challenges must be raised promptly and substantiated with evidence of prejudice.
    2. Substance Over Technicality: Courts prioritize substantive justice over procedural technicalities, especially in protracted trials.
    3. Documentary Integrity: Exporters must ensure the authenticity of all export-related documents to avoid criminal liability.

    This case serves as a precedent for handling jurisdictional disputes in complex financial and export fraud cases, reinforcing the need for diligence and timely legal strategy.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

  • Madras High Court Quashes Customs Order and Emphasizes Right to Fair Hearing in Duty Drawback Disputes

    Madras High Court Quashes Customs Order and Emphasizes Right to Fair Hearing in Duty Drawback Disputes

    Date: 13.08.2026

    A recent judgment by the Madras High Court has significant implications for exporters and customs authorities alike. The case of M/s. Meegan Exports versus the Assistant Commissioner of Customs highlights the importance of due process, the right to be heard, and adherence to principles of natural justice in customs proceedings.

    Background of the Case

    M/s. Meegan Exports, represented by its proprietor Mr. Aashish Modi, exported construction materials to the Maldives under nine shipping bills between April and August 2022. The company availed itself of the duty drawback scheme, which allows exporters to claim a refund of certain duties paid on inputs used in exported goods.

    However, customs authorities initiated proceedings under Section 75(1) of the Customs Act, 1962, and relevant Drawback Rules, alleging that Meegan Exports failed to realize export sale proceeds within the period prescribed by the Foreign Exchange Management Act (FEMA), 1999. This led to the issuance of an Order-in-Original and a recovery letter demanding repayment of the availed drawback.

    Key Issues Raised

    1. Lack of Opportunity to be Heard
      • Meegan Exports contended that it never received the show cause notice and was not given a chance for a personal hearing before the adverse order was passed.
    2. Realization of Export Proceeds
      • The petitioner produced receipts from the Ministry of Commerce, Directorate General of Foreign Trade, evidencing realization of export proceeds, countering the basis for the customs action.
    3. Customs Authorities’ Stand
      • The respondents argued that notices were sent to the address on record and that the petitioner failed to respond despite multiple opportunities.

    The High Court’s Findings

    Justice Hemant Chandangoudar, after considering submissions from both sides, made several important observations:

    • No Proof of Non-Receipt: The petitioner did not provide concrete evidence that the show cause notice was not received.
    • Possession of Realization Receipts: Since Meegan Exports had receipts showing realization of export proceeds, enforcing the impugned order would cause undue monetary loss.
    • No Prejudice to Customs: Granting another opportunity to the petitioner would not prejudice the customs authorities.

    The Court’s Order

    The High Court set aside both the Order-in-Original and the recovery letter. The matter was remanded to the customs authorities for fresh consideration, with clear directions:

    1. Personal Hearing: The petitioner must be given an opportunity for a personal hearing.
    2. Consideration of Evidence: All documents, including bank realization certificates, must be reviewed.
    3. Timely Disposal: The process must be completed within two months from the date of receipt of the court’s order.
    4. Proper Notice: Notices must be sent to the updated address provided by the petitioner.

    Implications for Exporters and Authorities

    This judgment reinforces several key principles:

    • Natural Justice: Authorities must ensure that affected parties receive proper notice and a fair chance to present their case.
    • Documentation: Exporters should maintain and promptly submit all relevant documents, such as bank realization certificates, to defend their claims.
    • Procedural Fairness: Even if procedural lapses occur, courts may grant another opportunity to prevent undue hardship, provided no prejudice is caused to the authorities.

    Conclusion

    The Madras High Court’s decision in the Meegan Exports case serves as a reminder of the critical role of procedural fairness in administrative actions. Exporters facing similar issues should be vigilant about responding to notices and maintaining comprehensive records, while authorities must adhere strictly to principles of natural justice.

    This case sets a precedent for balancing enforcement with fairness, ensuring that justice is not only done but seen to be done.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download: