Tag: #LegalUpdates

  • Delhi High Court Grants Bail in NDPS Case Over Absence of Diacetylmorphine in FSL Report

    Delhi High Court Grants Bail in NDPS Case Over Absence of Diacetylmorphine in FSL Report

    Date: 19.11.2026

    The Delhi High Court has granted regular bail to an accused in an NDPS case after the forensic report did not detect diacetylmorphine, the chemical compound commonly known as heroin, in the alleged recovered substance.

    Background of the prosecution case

    The bail application arose from an FIR registered under Sections 21, 25 and 29 of the Narcotic Drugs and Psychotropic Substances Act, 1985 (NDPS Act). The prosecution alleged that the accused was apprehended following secret information about the intended supply of heroin.

    According to the prosecution, a raiding team intercepted the accused at the specified location and recovered a brown powdery substance from a carrying bag. A field-testing kit initially identified the substance as heroin, and the alleged recovery was stated to be 300 grams.

    The investigation subsequently expanded to other alleged members of the supply chain. The prosecution claimed that further recoveries were made from co-accused persons and that disclosure statements linked the alleged transactions. After completion of the investigation, the investigating agency filed its chargesheet before the Special Court dealing with NDPS matters.

    Forensic analysis raised a fundamental issue

    The central issue in the bail proceedings was the final report of the Forensic Science Laboratory (FSL). While the preliminary field test had indicated heroin, the FSL examination of the sample did not identify diacetylmorphine.

    Instead, the report recorded the presence of substances including 6-monoacetylmorphine, acetylcodeine, morphine, codeine, noscapine, clozapine, trimethoprim, caffeine and acetaminophen.

    The High Court noted that diacetylmorphine is the chemical compound commonly known as heroin. Since the FSL report did not confirm its presence, the Court found that the alleged substance could not, at the bail stage, be treated as heroin in the manner asserted by the prosecution.

    Field-test result versus final FSL report

    The decision highlights the distinction between a preliminary field test and a final scientific examination. A field-testing kit may provide an initial indication during seizure, but the final forensic report is material when determining the nature of the substance allegedly recovered.

    The prosecution argued that environmental conditions may have caused degradation of the substance and suggested that it could originally have been heroin. The Court, however, found that the FSL findings raised a serious question about the prosecution’s case, particularly because the allegedly recovered substance did not contain diacetylmorphine.

    The Court relied on previous judicial decisions recognizing that heroin and morphine are separate and distinct substances under the NDPS framework. It also noted earlier rulings in which the absence of diacetylmorphine in a forensic report created a substantial doubt regarding an allegation of heroin recovery.

    Effect on the stringent bail conditions under Section 37

    Section 37 of the NDPS Act imposes restrictive conditions for bail in specified cases, including matters involving commercial quantities of narcotic drugs. The Court held that those stringent conditions were not attracted in this case because the forensic report did not establish the presence of diacetylmorphine.

    The Court observed that the alleged substance was not contraband in the form claimed by the prosecution, namely heroin. This finding was made only for deciding the bail application and was not a final determination of criminal liability.

    Other circumstances considered by the Court

    Along with the forensic issue, the Court considered the stage of the proceedings and the accused’s period of custody:

    • Investigation complete: The chargesheet had already been filed, reducing the need for custodial interrogation.
    • Trial had not commenced: None of the 23 prosecution witnesses had been examined, indicating that the matter was likely to take time.
    • Period of incarceration: The accused had remained in custody for approximately one year and one month.
    • Satisfactory jail conduct: The nominal roll recorded satisfactory conduct during custody.
    • Parity with co-accused: A co-accused allegedly found with a quantity of heroin had already been granted bail.

    The defence had also raised concerns about the absence of independent witnesses during the search and the lack of video recording of the search-and-seizure process. Although the Court’s decision primarily rested on the forensic findings, these issues formed part of the broader bail submissions.

    Bail conditions

    The High Court directed the release of the accused on a bail bond of Rs. 50,000 with one surety of the same amount, subject to conditions designed to protect the pending trial.

    The accused must:

    • Appear before the Special Court on every hearing date.
    • Ordinarily reside at the address recorded in prison records and inform the investigating officer or station house officer before changing it.
    • Keep the registered mobile number active and notify the authorities before changing the number or switching off the phone.
    • Avoid direct or indirect contact with prosecution witnesses or other persons connected with the case.
    • Refrain from tampering with evidence or doing anything that could prejudice the trial.
    • Not commit any offence while the proceedings remain pending.

    Legal significance of the ruling

    The order reinforces that the exact composition of an alleged narcotic substance is critical in NDPS proceedings. Where a preliminary field test identifies a substance as heroin but a subsequent FSL report does not confirm diacetylmorphine, the discrepancy may affect both the classification of the alleged contraband and the applicability of Section 37’s strict bail bar.

    The Court clarified that its observations are confined to the bail application. The pending trial will determine the allegations on the evidence presented before the Special Court.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi
  • Madras High Court Rules on Long-Pending Trademark Renewal Dispute

    Madras High Court Rules on Long-Pending Trademark Renewal Dispute

    Date: 19.11.2026

    The Madras High Court has directed the Registrar of Trademarks to accept and process V.A. Mishra & Sons’ long-pending trademark renewal request after finding no evidence that the mandatory statutory renewal notice had been sent.

    Background of the dispute

    In V.A. Mishra & Sons v. Registrar of Trademarks [WP(IPD) No. 16 of 2024], decided on 1 July 2024, the petitioner sought renewal and restoration-related relief for Trade Mark Application No. 573095 in Class 30.

    V.A. Mishra & Sons, operating as New Vijaya Sweets in Dharwad, Karnataka, stated that it had applied for the trademark in 1992. The application was examined in 1998, but registration was granted only on 15 July 2003. Since the registration occurred after the original term had effectively run, the mark was renewed on 7 November 2003.

    The dispute arose when the petitioner learned through its agent in March 2013 that the Registry’s website reflected 13 May 2009 as the renewal date. The petitioner promptly communicated with the Trademark Registry, seeking restoration of the removed mark, renewal of the registration, and payment of the applicable renewal surcharge. Despite repeated requests and payment of the required amount, no action was taken.

    Central legal issue: mandatory renewal notice

    The case turned on Section 25(3) of the Trade Marks Act, 1999. This provision requires the Registrar to send the registered proprietor notice of the registration’s expiration date and the conditions, including fee requirements, for obtaining renewal.

    The petitioner argued that it had never received this mandatory notice. Crucially, the Registrar was unable to place any material before the Court showing that the required notice had been issued or served.

    Justice P.B. Balaji held that there was no evidence of compliance with the statutory notice requirement. This failure was decisive because a trademark proprietor must receive the prescribed notice before adverse consequences flow from a missed renewal date.

    Court’s directions

    The High Court allowed the writ petition and issued a writ of mandamus directing the Registrar of Trademarks to:

    • accept the petitioner’s renewal request dated 27 March 2013 for Trade Mark Application No. 573095 in Class 30 within eight weeks;
    • allow the petitioner to submit a further renewal request, with the prescribed fee, within four weeks from the date of the order, since the subsequent renewal period had also expired on 13 May 2019; and
    • pass orders on that further renewal request within eight weeks after it is filed.

    The connected miscellaneous petition was closed, and no costs were awarded.

    Why the decision matters

    The ruling reinforces that statutory procedural safeguards in trademark administration are not optional. Where the Registrar cannot establish that the mandatory renewal notice under Section 25(3) was sent, a trademark owner may be entitled to have a delayed renewal request considered.

    For trademark owners, the decision highlights the importance of maintaining renewal records and acting promptly when a discrepancy appears in the Registry’s online records. For the Trademark Registry, it underscores the need to preserve reliable evidence that statutory notices have been dispatched.

    The Court did not itself renew the mark. Instead, it required the Registry to accept and decide the petitioner’s requests within defined timelines, ensuring that the renewal application receives the consideration that the missing statutory notice had prevented.

    Connected Matter

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi
  • Customs Cannot Invoke Extended Limitation After Delay, Holds CESTAT Chennai

    Customs Cannot Invoke Extended Limitation After Delay, Holds CESTAT Chennai

    Date: 19.11.2026

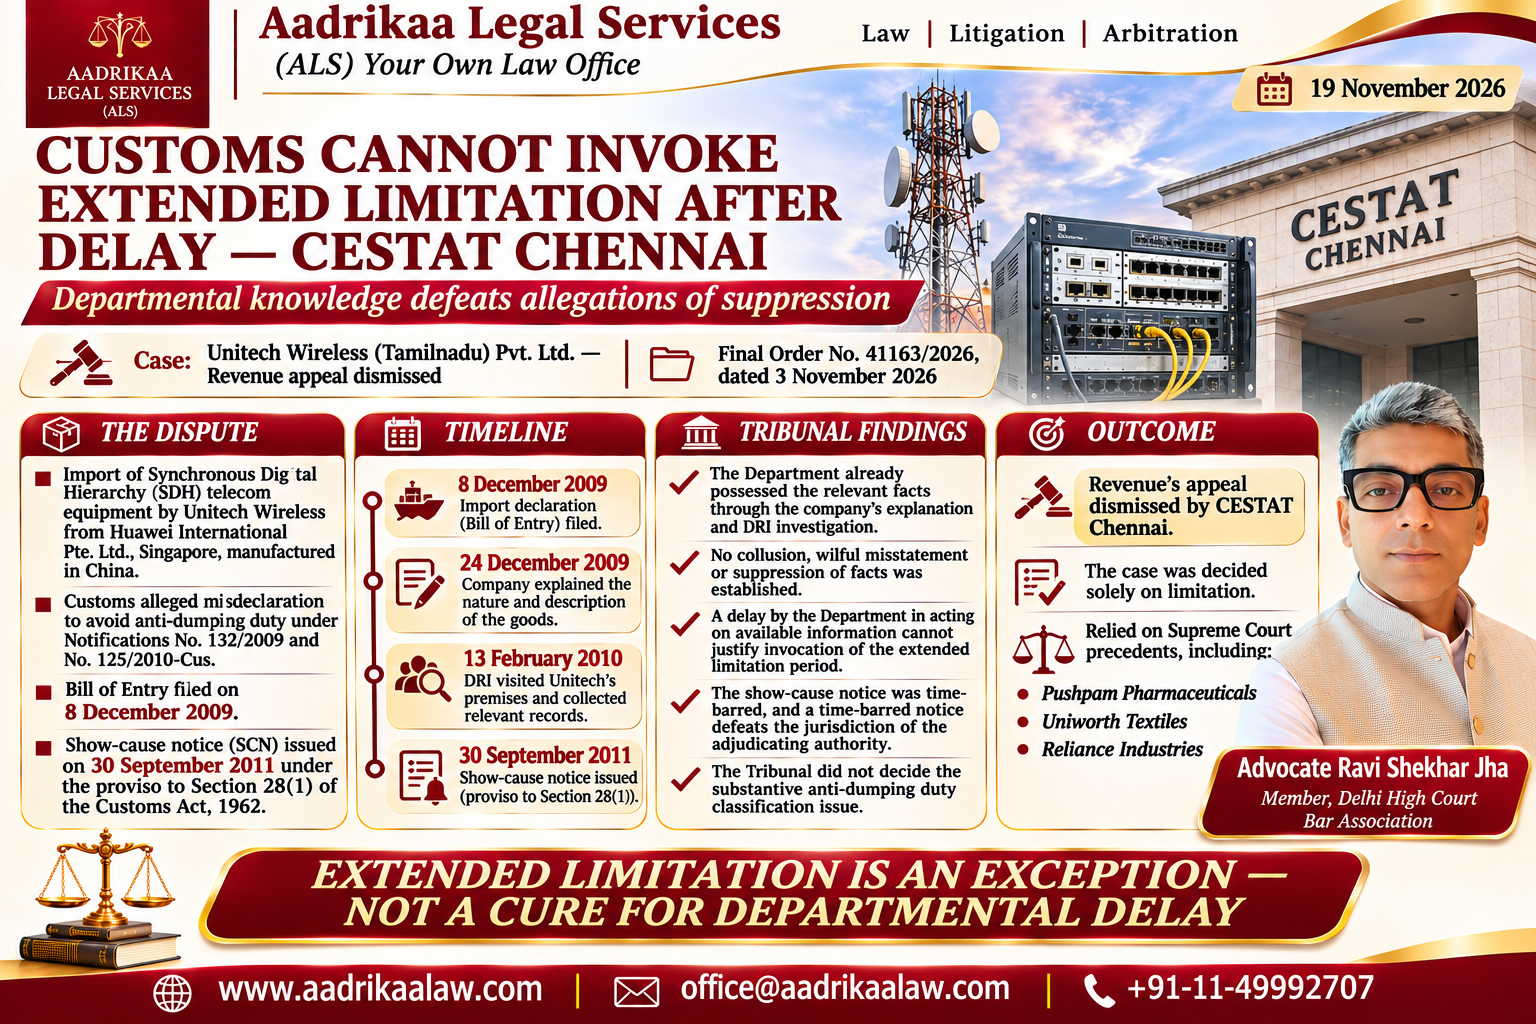
    The Chennai Bench of CESTAT dismissed the Revenue’s appeal against Unitech Wireless (Tamilnadu) Pvt. Ltd., holding that the show-cause notice seeking anti-dumping duty was barred by limitation and that the extended period could not be invoked.

    Background of the dispute

    The case arose from imports of Synchronous Digital Hierarchy (SDH) telecom equipment by Unitech Wireless from Huawei International Pte. Ltd., Singapore. The equipment was manufactured by Huawei Technologies Co. Ltd., China.

    Customs authorities alleged that Unitech had misdeclared the imported goods by using a technical description without stating their trade name. According to the Department, this was intended to avoid anti-dumping duty under Notification No. 132/2009 and the subsequent Notification No. 125/2010-Cus.

    A show-cause notice dated 30 September 2011 was issued under the proviso to Section 28(1) of the Customs Act, 1962. It proposed recovery of anti-dumping duty, confiscation of goods, and penal action. The Commissioner of Customs, Chennai-II later dropped the proceedings. Revenue challenged that decision before the Customs, Excise and Service Tax Appellate Tribunal (CESTAT).

    Revenue’s position: Equipment could attract anti-dumping duty

    The Department argued that the Commissioner had incorrectly interpreted Note 2 to Notification No. 125/2010-Cus. It submitted that the word β€œessentially” should not be read as β€œexclusively.”

    On this interpretation, the Department contended that equipment capable of transmitting signals through media other than optical fibre, including microwave radio or electrical copper media, should not automatically fall outside the anti-dumping-duty levy. Revenue therefore sought reversal of the Commissioner’s order and confirmation of the proposed duty demand.

    Unitech’s defence: No misdeclaration and no basis for extended limitation

    Unitech challenged the very validity of the show-cause notice on limitation. It argued that the relevant Bill of Entry had been filed on 8 December 2009, while the notice was issued only on 30 September 2011, beyond the normal statutory period.

    The company maintained that it had correctly declared both the value and description of the imported equipment. The notice did not identify any false declaration in the Bill of Entry; instead, it alleged that adequate technical details had not been made available. Unitech argued that this did not establish collusion, wilful misstatement, or suppression of facts, which are necessary conditions for invoking the extended limitation period under Section 28(1).

    On the merits, Unitech also maintained that the imported equipment used microwave antennas and was not intended for transmission through optical fibre. It argued that the products therefore came within the exclusion in Note 2 to Notification No. 125/2010-Cus.

    Tribunal’s findings: Department already knew the relevant facts

    CESTAT found that the central issue was whether Revenue could validly invoke the extended limitation period. The Tribunal noted that Directorate of Revenue Intelligence officials had visited Unitech’s premises in Hyderabad on 13 February 2010 and had collected relevant import-related documents and details.

    The Tribunal also recorded that Unitech had explained the nature and description of the goods as early as 24 December 2009. These facts showed that the Department was already aware of the relevant factual position well before issuance of the show-cause notice in September 2011.

    Because the Department had access to the relevant information, the Tribunal held that Unitech could not be accused of collusion, wilful misstatement, or suppression of facts. A delay by the authorities in acting on available information could not justify use of the extended limitation period.

    Why limitation decided the case

    The Tribunal emphasized that a challenge based on the show-cause notice being time-barred goes to the jurisdiction of the adjudicating authority. If the notice is issued outside the legally permissible period, the authority lacks jurisdiction to decide the demand. Such a defect cannot be corrected later in appellate proceedings.

    Relying on Supreme Court precedents cited by Unitech, including Pushpam Pharmaceuticals, Uniworth Textiles, and Reliance Industries, CESTAT concluded that the appeal had to fail on limitation alone. It therefore did not need to rule further on the substantive anti-dumping-duty dispute.

    Outcome and legal significance

    By Final Order No. 41163/2026 dated 3 November 2026, CESTAT Chennai dismissed Revenue’s appeal. The Tribunal also disposed of Unitech’s miscellaneous application for additional evidence and the cross-objections filed in the appeal.

    The ruling reinforces an important customs-law principle: the extended limitation period is an exceptional remedy, not a mechanism to cure departmental delay. Where customs authorities already possess material information about an import, they must act within the normal limitation period unless they can establish deliberate concealment, wilful misstatement, or another statutory ground for extension.

    For importers, the decision highlights the value of maintaining clear, timely records of product descriptions, technical specifications, and communications with investigating authorities. For the Department, it underscores that prior knowledge of the facts can defeat a later allegation of suppression.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi
  • CESTAT Mumbai Overturns Differential Duty Demands on Second-Hand Crane Imports

    CESTAT Mumbai Overturns Differential Duty Demands on Second-Hand Crane Imports

    Date: 18.11.2026

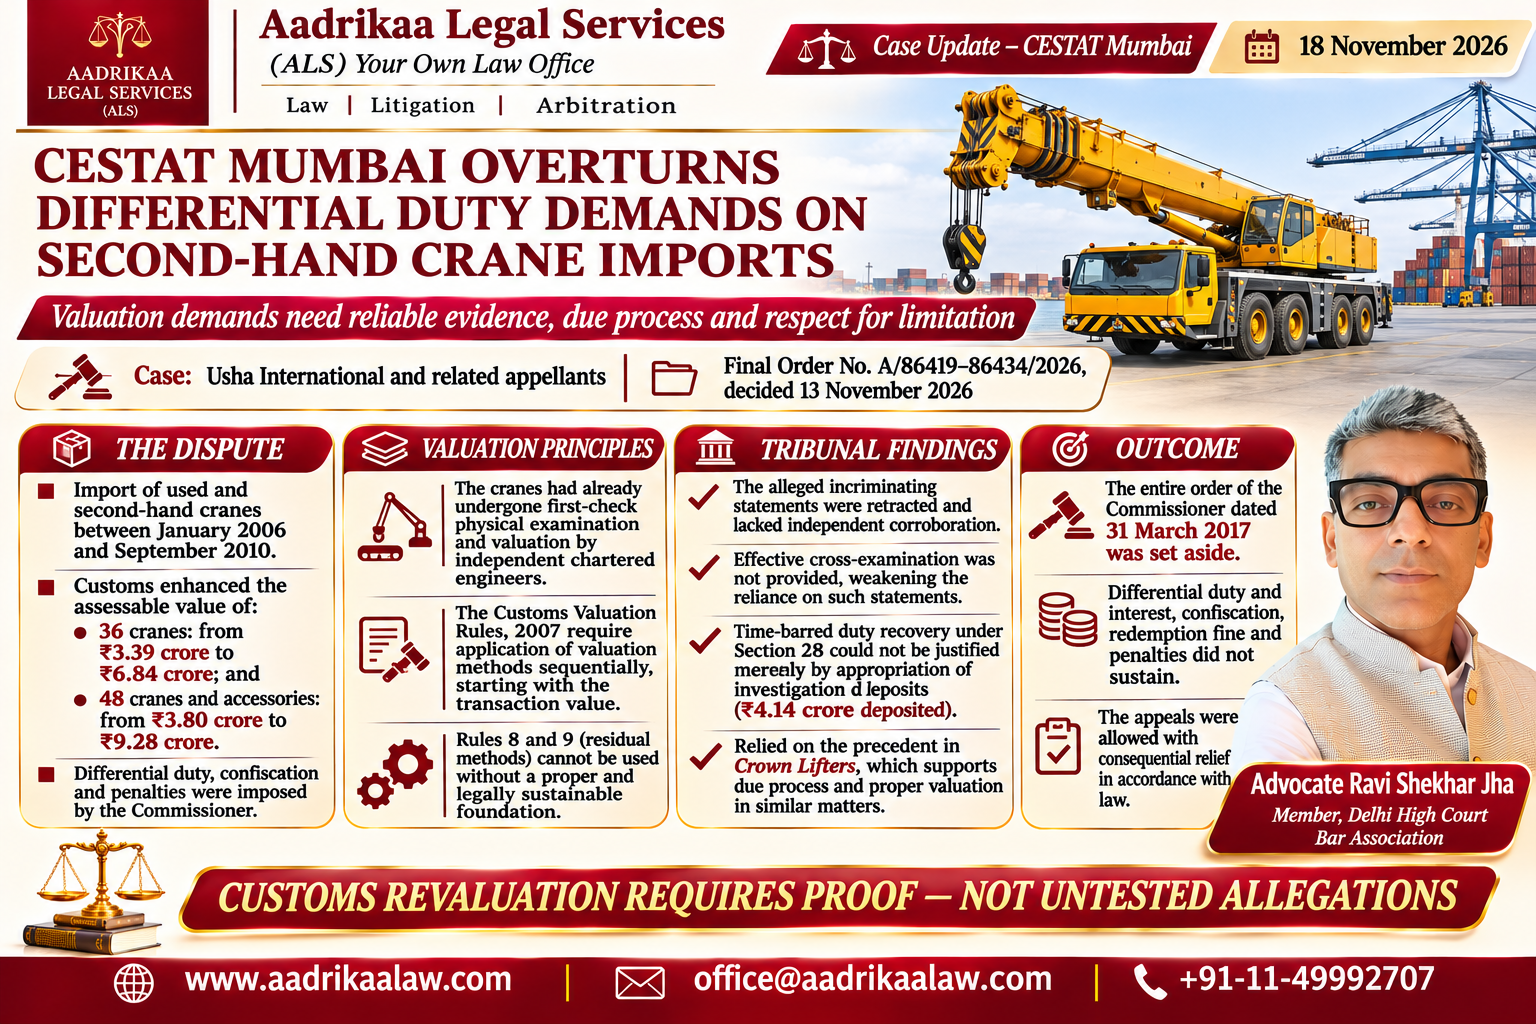
    The Mumbai CESTAT has allowed the appeals of Usha International and related parties, holding that the Customs Department could not sustain a later enhancement of value, differential-duty demands, confiscation, or penalties without legally reliable valuation evidence and procedural safeguards.

    Overview of the dispute

    In Final Order No. A/86419-86434/2026, decided on 13 November 2026, the Customs, Excise & Service Tax Appellate Tribunal (CESTAT), Mumbai, examined a group of appeals arising from the import of used and second-hand cranes between January 2006 and September 2010.

    The principal appellant, Usha International, Kolkata, and several co-noticees, including high-sea-sale buyers, customs-related intermediaries and individuals, challenged an order of the Principal Commissioner of Customs (Import-I), Mumbai. The original order had substantially increased the assessable value of the imported cranes, demanded differential customs duty with interest, ordered confiscation, and imposed penalties.

    The Tribunal set aside the entire adjudication order and granted consequential relief in accordance with law.

    What the Customs Department alleged

    The investigation began after the Directorate of Revenue Intelligence (DRI) received intelligence suggesting that certain importers of used cranes were undervaluing their imports. The alleged practices included:

    • Declaring a lower value for imported cranes;
    • Suppressing or manipulating freight and insurance elements;
    • Using allegedly fabricated shipping, invoice and remittance documents;
    • Making alleged differential payments through unofficial channels; and
    • Relying on a benchmark valuation based on the crane’s weight to secure clearance.

    Following searches, document collection and recorded statements, the Department issued a show-cause notice in November 2013. The Commissioner subsequently re-determined the value of:

    • 36 cranes directly imported by Usha International, increasing their declared value from about Rs. 3.39 crore to Rs. 6.84 crore; and
    • 48 cranes and one consignment of accessories sold through high-sea-sale arrangements, increasing the value from about Rs. 3.80 crore to Rs. 9.28 crore.

    The order also confirmed differential duty, appropriated sums deposited during investigation, and imposed penalties on Usha International’s representative and other co-noticees.

    Why the Tribunal ruled for the importers

    1. Earlier customs assessments had been completed after physical examination

    The Tribunal noted that the used cranes had been physically examined at the port of import on a first-check basis. Local independent chartered engineers had assessed their condition and value, and Customs officers had assessed duty on that basis before clearance.

    The importers had paid duty based on the enhanced values determined during these original assessments. The Tribunal found that a subsequent re-determination of value required specific and legally sustainable evidence showing that duty had escaped assessment or had been short-levied.

    2. Customs valuation rules must be applied sequentially

    Under the Customs Valuation Rules, 2007, transaction value is the starting point. If Customs rejects that value, it must proceed through the prescribed valuation methods in sequence.

    The Tribunal emphasized that the Department could not simply rely on the residual valuation methods under Rules 8 and 9 without a valid foundation. The Board’s guidance on valuation of second-hand machinery likewise requires Customs to reject the declared transaction value on proper grounds before moving to another valuation method.

    In this case, the Tribunal found that the later valuation exercise did not meet this legal standard.

    3. Retracted statements could not be the sole basis for demand

    A key part of the Department’s case relied on a statement attributed to Usha International’s representative regarding the alleged actual transaction values. However, the statement was retracted at an early stage before a judicial authority, with an allegation that it had been obtained through force, threat and coercion.

    The Tribunal held that a retracted statement cannot be relied upon to confirm duty demands without proper corroboration. It also noted that the Department had not addressed the retraction through a fresh statement or by providing an effective opportunity for cross-examination.

    The decision reinforces that allegations of undervaluation cannot rest solely on untested statements, particularly where the witness testimony is disputed and procedural requirements for relying on statements have not been followed.

    4. No effective cross-examination weakened the Department’s evidence

    The Tribunal found that the statements of persons relied upon by Customs were not tested through cross-examination. This was especially significant because the statements formed an important part of the alleged undervaluation case.

    Relying on prior Tribunal authority that had been upheld when the Supreme Court dismissed the Revenue’s appeal, the Bench held that statements cannot be used as conclusive evidence without following the applicable statutory procedure and allowing cross-examination where necessary.

    5. Time-barred imports could not be used for duty recovery through appropriation

    The show-cause notice was issued on 11 December 2013. Some of the relevant imports fell outside the five-year statutory period for recovery under Section 28 of the Customs Act.

    Although Rs. 4.14 crore had been deposited voluntarily during the investigation, the Tribunal held that this did not permit Customs to appropriate amounts toward duty demands that were beyond the statutory limitation period, particularly when there was no documented admission of liability or express consent for such adjustment.

    The Tribunal also noted that the original adjudication order had not confirmed the duty demand for certain time-barred imports. Accordingly, the later appropriation of deposits for those imports was not legally sustainable.

    Reliance on the Crown Lifters precedent

    The Tribunal treated its earlier decision in Karim Haria and Crown Lifters Pvt. Ltd. v. Commissioner of Customs as materially relevant. That decision involved comparable allegations concerning used-crane imports, alleged undervaluation and reliance on statements without adequate corroboration or cross-examination.

    In the earlier matter, the Tribunal had ruled that:

    • Actual purchase prices had not been properly established;
    • Alleged unofficial payment arrangements had not been sufficiently corroborated;
    • Reassessment and recovery of differential duty could not stand on unreliable evidence; and
    • Confiscation and penalties could not be imposed merely on the basis of a subsequent valuation dispute.

    The Revenue’s challenge to that order had not resulted in a stay or reversal by the Bombay High Court. The CESTAT therefore found no basis to depart from the same legal approach in Usha International’s case.

    Final outcome

    The CESTAT set aside the Commissioner’s order dated 31 March 2017 in full. As a result:

    • The re-determined values of the imported used cranes were not sustained;
    • The differential-duty demands and related interest did not survive;
    • The appropriation of investigation deposits for time-barred imports was not upheld;
    • The proposed confiscation and redemption-fine consequences failed; and
    • Penalties imposed on Usha International’s representative and other co-noticees were set aside.

    Key legal takeaway

    The ruling underscores that Customs authorities must follow the statutory valuation sequence, rely on corroborated and procedurally admissible evidence, respect limitation periods, and provide fair opportunities to challenge witness evidence. A completed customs assessment of used machinery cannot be reopened through a later valuation theory based principally on retracted or untested statements.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi

  • Bombay High Court Declines to Cancel Bail in NDPS Prosecution

    Bombay High Court Declines to Cancel Bail in NDPS Prosecution

    Date: 18.11.2026

    The High Court dismissed a challenge to a bail order in an NDPS prosecution, holding that cancellation of bail requires clear post-bail misconduct, a supervening circumstance, or a demonstrably illegal or perverse orderβ€”not merely the seriousness of the allegations.

    Background of the Case

    A criminal writ petition under Article 227 of the Constitution challenged an order of the Sessions Court granting bail to an accused in a case registered under the Narcotic Drugs and Psychotropic Substances Act, 1985 (NDPS Act).

    The prosecution alleged offences under Section 8(c), read with Sections 20(b)(ii)(A), 22(C), 27 and 29 of the NDPS Act. The accused was implicated primarily on the allegation that he owned the rented premises from which contraband was recovered and that a co-accused had stated that the owner was aware of the alleged activities at those premises.

    The prosecuting agency argued that the bail order failed to adequately consider the seriousness of the offence, the risk of witness intimidation, and the possibility of evidence being tampered with. It described the order as mechanical and legally unsustainable.

    Key Legal Issue

    The central question before the High Court was whether the bail order was illegal, perverse, or based on irrelevant considerations so as to justify cancellation of bail.

    The Court distinguished between two separate legal exercises:

    • Refusal of bail: The court assesses whether an accused should receive bail in the first instance.
    • Cancellation of bail: The court considers whether an existing grant of liberty should be withdrawn. This is a more stringent exercise because it directly interferes with personal liberty already conferred by a judicial order.

    When Can Bail Be Cancelled?

    The Court reiterated that cancellation of bail is an exceptional measure and must be approached with caution. It may be warranted where the accused, after obtaining bail:

    • engages in similar criminal activity;
    • obstructs or interferes with the investigation;
    • attempts to influence, threaten, or intimidate witnesses;
    • tampers with evidence;
    • breaches bail conditions;
    • attempts to abscond, leave the country, or evade the court process;
    • becomes unavailable to the investigating agency or trial court; or
    • otherwise acts in a way that makes a fair investigation or trial impossible.

    These factors are illustrative, not exhaustive. The governing consideration is whether subsequent conduct or circumstances demonstrate that continued bail would prejudice the administration of justice.

    Court’s Findings

    The High Court found no basis to interfere with the Sessions Court’s decision. The bail order showed that the trial court had considered the nature of the accusation, the role attributed to the accused, and the gravity of the alleged offence before exercising its discretion.

    Importantly, the challenge did not identify any material event after the grant of bail that justified its cancellation. There was no allegation that the accused had violated bail conditions, influenced witnesses, tampered with evidence, absconded, or obstructed the proceedings.

    The Court also noted that the NDPS trial was continuing and that the accused was appearing before the trial court. The bail order had remained in force for a substantial period without any reported breach or misuse of liberty.

    Decision

    The High Court dismissed the writ petition as lacking merit and declined to cancel bail. No order as to costs was made.

    Legal Significance

    This ruling reinforces that the gravity of an alleged offence, by itself, does not automatically justify cancellation of bail once it has been granted. A party seeking cancellation must generally establish either:

    1. a serious legal defect in the original bail order, such as perversity, illegality, or reliance on irrelevant material; or
    2. a supervening circumstance, including misuse of bail, breach of conditions, interference with justice, or conduct threatening the fairness of the trial.

    The decision reflects the principle that cancellation of bail is not a mechanism for rehearing the original bail application. It is a narrowly exercised power intended to protect the integrity of the investigation and trial while respecting the accused’s personal liberty.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi
  • Bombay High Court Quashes Online Rejection of Delayed Trademark Renewal

    Bombay High Court Quashes Online Rejection of Delayed Trademark Renewal

    Date: 18.11.2026

    The Bombay High Court has held that a trademark proprietor may seek renewal even after an extended lapse where the Trade Marks Registry neither issued the statutory expiry notice nor removed the mark from the register.

    Background of the dispute

    Motwane Private Ltd. owned three registrations for the mark β€œMOTWANE”: Nos. 312470, 312472 and 312473. The company stated that it had used the mark continuously in business since 1976 and that the registrations had last been renewed until 17 February 1983.

    In 2023, during a routine review of its trademark portfolio, the company found that the registrations had not been renewed after 1983. Yet, the marks continued to appear in the official Trade Marks Registry as registered in Motwane’s name.

    When Motwane attempted to renew the registrations through the online system, the portal rejected the applications with the message: β€œApplication cannot be renewed (delay of more than one year).” The company then approached the Bombay High Court under Article 226 of the Constitution.

    Central legal issue

    The case turned on Section 25 of the Trade Marks Act, 1999, which regulates the duration, renewal, removal and restoration of trademark registrations.

    Section 25(3) requires the Registrar to send the registered proprietor a notice before the registration expires. The notice must state the expiry date and the conditions, including fees, for securing renewal. Only after the prescribed time expires and the relevant conditions remain unmet may the Registrar remove the mark from the register.

    Motwane used Right to Information applications to seek records of any removal notice. The Registry’s responses confirmed that no notice had been issued, dispatched or delivered for any of the three registrations. The Registry also accepted before the Court that it had not followed the statutory procedure for removing the marks.

    Court’s reasoning

    The Division Bench of Justices found that the proprietor’s failure to renew did not, by itself, extinguish the right to seek renewal in these circumstances.

    The Court emphasized three connected facts:

    • No mandatory notice: The Registrar had not issued the Section 25(3) notice to Motwane before any removal process.
    • No removal from the register: The marks remained recorded on the Trade Marks Register in Motwane’s name.
    • A mutual lapse, not a unilateral forfeiture: While Motwane had delayed renewal, the Registry had also failed to carry out its statutory duty to issue notice and follow the removal procedure.

    The Court rejected an interpretation under which non-renewal alone would cause the proprietor’s renewal rights to lapse where no Section 25(3) notice was issued. It held that, so long as the marks remained on the register and the mandatory process had not been followed, Motwane’s right to apply for renewal continued to exist.

    The Court also noted that the electronic portal’s refusal, based solely on a delay exceeding one year, was inconsistent with Section 25(3) in the facts of this case.

    Earlier decisions followed

    The judgment aligns with prior rulings that recognize the importance of the statutory notice requirement. The Court referred to decisions involving Cipla Ltd., Harbans Singh Khanduja and Ipca Laboratories Ltd., each supporting the principle that the Registry must comply with Section 25(3) before removing a mark and that the proprietor’s renewal rights remain capable of recognition where this procedure was not followed.

    Final order

    On 16 February 2024, the Bombay High Court allowed Motwane’s petition and:

    1. Quashed the portal-generated rejection stating that renewal could not be sought because the delay exceeded one year.
    2. Held that Motwane may file renewal applications in the prescribed form and on payment of the prescribed fees.
    3. Directed the Registrar to grant renewal in accordance with law, subject to Motwane meeting the remaining procedural requirements.
    4. Allowed filing within two weeks of the order being made available, either physically or through the electronic module if available, and required the Registry to decide the applications within two weeks thereafter.

    Significance for trademark owners

    This decision confirms that an unusually long delay in renewal is not necessarily decisive when the Trade Marks Registry has not served the mandatory statutory notice and has not removed the registration from the register. It reinforces that administrative systems and online filing portals cannot override the protections and procedures prescribed by the Trade Marks Act.

    For trademark proprietors, the ruling underscores the importance of checking both the official register and the Registry’s compliance with notice requirements when addressing old or apparently lapsed registrations.

    The key legal principle is that failure to renew must be assessed together with whether the Registrar followed the mandatory process for notice and removal.

    Connected Matter

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi

  • Madras High Court Clarifies Trademark Renewal Rights for Unremoved Marks

    Madras High Court Clarifies Trademark Renewal Rights for Unremoved Marks

    Date: 17.11.2026

    In Jaisuryas Retail Ventures Pvt. Ltd. v. Registrar of Trade Marks, decided on 13 August 2024, the Madras High Court addressed 11 writ petitions concerning the renewal of registered trademarks across Classes 29, 30, 31, 32, 35 and 43. The decision clarifies the relationship between trademark renewal, statutory notice, removal from the Register and the rights of an unrecorded assignee.

    Background of the dispute

    Jaisuryas Retail Ventures Pvt. Ltd. claimed rights in the trademarks under an assignment deed dated 22 October 2021 from the registered proprietor. However, the assignment had not yet been entered in the Register of Trade Marks.

    The company attempted to file renewal applications but stated that it could not access the online portal. It therefore sought directions requiring the Trade Marks Registry to permit renewal of the marks.

    The Registrar opposed the petitions on two principal grounds:

    • Jaisuryas was not yet the registered proprietor because the assignment had not been recorded.
    • Renewal was argued to be unavailable beyond the statutory time limits, and notice of expiry had allegedly been sent to the registered proprietor’s agent on 25 March 2022.

    The statutory framework for trademark renewal

    The Court examined Section 25 of the Trade Marks Act, 1999, together with Rules 57 to 61 of the Trade Marks Rules, 2017.

    A trademark registration is valid for ten years and can be renewed repeatedly in further ten-year blocks. Unlike intellectual-property rights with a fixed maximum term, trademark registrations can therefore continue indefinitely, provided the statutory renewal requirements are met.

    The legal framework operates broadly as follows:

    • Renewal application: A proprietor may apply in Form TM-R. Rule 57 permits an application to be made from one year before expiry.
    • Pre-expiry notice: If no renewal request has been received, the Registrar must send a notice in Form RG-3, no more than six months before expiry, informing the registered proprietor about the approaching expiry and renewal conditions.
    • Six-month grace period: Even after expiry, the mark cannot be removed if a renewal application is made within six months along with the prescribed fee and surcharge.
    • Restoration: If the mark is removed, the proprietor may seek restoration and renewal within one year from expiry, subject to the relevant requirements.

    Why non-removal of the marks mattered

    The Court found that the trademarks in question had not been removed from the Register. Although the Registrar relied on a dispatch entry to show that the expiry notice had been sent, no acknowledgment of receipt was produced.

    The Court held that, without proof that the registered proprietor received the statutory notice, it could not conclude that notice had been duly received. This was important because the notice requirement exists to alert the proprietor of the approaching expiry and enable timely renewal.

    The Court further reasoned that Rule 57 specifies the earliest point at which a renewal application may be filed, but does not prescribe a final deadline for renewal where the mark remains on the Register. The one-year deadline applies to restoration after removal, not necessarily to renewal of a mark that has never been removed.

    Accordingly, the Court concluded that where the Registrar has not effectively notified the proprietor and has not removed the mark, the proprietor or successor-in-interest may seek renewal even after the ordinary renewal and restoration windows have elapsed.

    Distinguishing renewal from restoration

    The judgment draws an important distinction:

    • Renewal concerns a trademark that remains on the Register. In such circumstances, the Court held that an application may be made after the Rule 57 start date, because no endpoint is expressly prescribed for renewal.
    • Restoration concerns a trademark that has already been removed for non-payment. A strict time limit applies because removal is advertised, and third parties may acquire or pursue conflicting rights after that point.

    This distinction reflects the commercial purpose of the statutory scheme. Once a mark has been removed and the removal is publicized, the law must balance the former proprietor’s interests against the possibility of third-party rights. That concern is materially reduced while the mark continues to appear on the Register.

    Assignment must be recorded before renewal

    Although the Court accepted that renewal could be pursued, it did not permit Jaisuryas to renew immediately. The company was not the recorded proprietor at the time of the order; it relied on an assignment deed that had not yet been registered.

    The Court therefore required the company to first apply for registration of the assignment. Only after the assignment is recorded may it apply for renewal in its own capacity.

    Court’s directions

    The writ petitions were disposed of with the following directions:

    1. Registration of assignment: Jaisuryas may apply to record the assignment under the Trade Marks Act, 1999, and the Registry must consider that application expeditiously.
    2. Renewal after recordal: Within one month of registration of the assignment, Jaisuryas may apply to renew the trademarks.
    3. Protection from removal: The Registrar must not take steps to remove the marks until the company has had the opportunity to complete the assignment and renewal process.
    4. Access to filing: The Registry must provide portal access or allow the necessary papers to be filed physically.
    5. Costs: No order was made as to costs.

    Key implications for trademark owners and assignees

    This ruling reinforces that procedural failures by the Trade Marks Registry can have substantive consequences. Where the required expiry notice is not shown to have been received and the mark remains on the Register, renewal may still be available notwithstanding the passage of time.

    For assignees, the decision also underscores that ownership documentation alone is not enough for Registry-facing actions. The transfer must be formally recorded before the assignee can seek renewal as proprietor. The decision follows the approach adopted by the Bombay High Court in Motwane Private Limited v. Registrar of Trade Marks, while distinguishing a Delhi High Court decision where service of the statutory notice had been duly established.

    The central principle is clear: continued presence of a trademark on the Register, coupled with the absence of proven notice and removal, preserves a route to renewalβ€”subject to proper recordal of title.

    Connected Matters

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi

  • Allahabad High Court Protects Truck Owner From Arrest in NDPS Investigation

    Allahabad High Court Protects Truck Owner From Arrest in NDPS Investigation

    Date: 17.11.2026

    The High Court has granted anticipatory bail to an accused in an NDPS Act case, holding that mere recorded ownership of a vehicle allegedly used for transporting contraband was insufficient, at the pre-arrest bail stage, to establish a direct connection with the offence.

    Background of the case

    The matter arose from an FIR registered in 2020 under Sections 8 and 20 of the Narcotic Drugs and Psychotropic Substances Act, 1985. The prosecution alleged that co-accused persons were apprehended with a large quantity of cannabis, reportedly being transported in a truck.

    The anticipatory bail applicant was not named in the FIR. His alleged connection to the case emerged during further investigation more than five years after the incident, principally because the vehicle was registered in his name.

    The applicant contended that he had sold the vehicle years earlier through a sale document, though the purchaser had not completed the formal transfer of registration. He also submitted that he had cooperated with the investigation, had received a notice requiring his appearance, and had no previous criminal record.

    Submissions before the Court

    The defence argued that the applicant had been falsely implicated and that neither the FIR nor the statements of the co-accused linked him to the alleged transportation or possession of the contraband. The applicant’s position was that registration records alone could not establish his involvement, particularly when the vehicle had allegedly been sold before the incident.

    The prosecution opposed anticipatory bail because of the substantial quantity of contraband allegedly recovered. However, it acknowledged that the co-accused had not named the applicant in their statements and that his name surfaced considerably later. The prosecution also stated that the claimed transfer of the vehicle remained under investigation.

    Why anticipatory bail was granted

    The Court found several circumstances material at the bail stage:

    • No nomination in the FIR: The applicant was not identified in the original FIR.
    • Delayed implication: His name surfaced more than five years after the alleged incident.
    • No statement by co-accused: The arrested co-accused did not name him when their statements were recorded.
    • No evidence of coordination: The prosecution did not produce material showing that he was in contact with the co-accused apprehended at the spot.
    • Limited material against him: At that stage, the primary allegation was based on his recorded ownership of the vehicle.
    • Clean antecedents and cooperation: There was no allegation that he had failed to cooperate, and he had no reported criminal history.

    On this material, the Court held that the possibility of false implication could not be excluded at that stage. It clarified that the order did not express any final view on the merits of the criminal case.

    Legal principles applied by the Court

    The Court relied on the Supreme Court’s decision in Sushila Aggarwal v. State (NCT of Delhi), which requires courts considering anticipatory bail to assess the nature and gravity of the allegations, the specific role attributed to the applicant, and risks such as interference with the investigation, intimidation of witnesses, tampering with evidence, or absconding.

    It also referred to Siddharth v. State of Uttar Pradesh, emphasizing that the legal authority to arrest does not automatically make arrest necessary. Arrest may be justified where custodial interrogation is required, the offence is particularly serious, or there is a real risk of absconding, non-cooperation, witness influence, or obstruction of the investigation. Where an accused is cooperating and such risks are not demonstrated, routine arrest is not warranted merely because it is legally permissible.

    Bail conditions

    The anticipatory bail protection will remain in force until the conclusion of the trial, subject to these conditions:

    1. The accused must furnish a personal bond of Rs. 50,000 with two sureties of the same amount.
    2. The accused must cooperate with the Investigating Officer and appear whenever required for investigation.
    3. The accused must not directly or indirectly threaten, induce, or promise anything to a person acquainted with the facts of the case to influence evidence or testimony.
    4. The accused must not leave India without prior permission of the court.

    The Court further allowed the prosecution, investigating agency, or complainant to seek cancellation of bail if any condition is breached or the protection is misused.

    Significance of the ruling

    This decision reinforces that a serious allegation under the NDPS Act does not, by itself, resolve an application for anticipatory bail.

    The court must separately assess the evidence linking the particular applicant to the alleged offence and the necessity of arrest. In this case, delayed implication, the absence of a direct allegation by co-accused, lack of evidence of contact with those arrested, cooperation with the investigation, and the limited nature of the material against the applicant collectively supported pre-arrest protection.

    The ruling also underlines that vehicle registration may be a relevant investigative circumstance, but it is not necessarily conclusive proof of participation in an alleged narcotics offence.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi

  • Pre-2019 Solar EPC Contracts: Supreme Court Strikes Down Retrospective GST Demand

    Pre-2019 Solar EPC Contracts: Supreme Court Strikes Down Retrospective GST Demand

    Date: 17.11.2026

    The Supreme Court has ruled that the 70:30 GST valuation mechanism for solar EPC contracts cannot be imposed retrospectively on supplies made before 1 January 2019, and that a detachable solar power generating (SPG) system is not automatically a works contract merely because it is mounted on a civil foundation.

    The dispute: GST demand on solar EPC projects

    Sterling and Wilson Pvt. Ltd., an EPC contractor that supplies and installs solar power generating systems across India, faced a GST demand for projects executed between 1 July 2017 and 31 December 2018. The tax authorities treated these turnkey contracts as works contracts and applied a valuation split of 70% goods and 30% services.

    This approach resulted in 5% GST on 70% of the contract value and 18% GST on the remaining 30%. The demand, including CGST, SGST and penalties, totalled approximately β‚Ή53.36 crore.

    The company had instead paid GST at 5% on the supply and installation of the SPG systems, relying on the then-applicable entry for solar power generating systems under the GST rate notification.

    How the GST regime changed from 2019

    When GST was introduced, renewable energy devices, including a solar power generating system, were covered by a concessional 5% GST rate. The policy reflected the GST Council’s objective of limiting the cost impact on renewable-energy generation.

    From 1 January 2019, the Government introduced a specific valuation mechanism for renewable-energy EPC contracts. Under this mechanism:

    • 70% of gross consideration is deemed to be the value of eligible goods and taxed at 5%.
    • 30% is deemed to be the value of specified services and taxed at 18%.
    • The effective combined GST rate becomes 8.9%.

    For example, on a contract value of β‚Ή10,000, the pre-2019 5% rate produced GST of β‚Ή500. Under the later 70:30 method, GST would be β‚Ή350 on the goods portion plus β‚Ή540 on the services portion, or β‚Ή890 in total.

    The Court’s key finding: the 70:30 formula was optional for the earlier period

    In 2021, the Government issued a circular allowing taxpayers to use the 70:30 method for eligible renewable-energy projects completed between 1 July 2017 and 31 December 2018. The tax department treated that clarification as compulsory and issued demands accordingly.

    The Supreme Court rejected that interpretation. It held that the language of the circular, stating that GST β€œcan” be paid using the 70:30 ratio for the earlier period, gave taxpayers an option. It did not require every taxpayer to retrospectively revalue pre-2019 supplies using that formula.

    The Court emphasized that the 2018 notifications creating the 70:30 scheme expressly took effect from 1 January 2019. They did not operate retrospectively. Accordingly, the department could not mandate the later regime for transactions completed under the earlier legal framework.

    Solar EPC supply was not a works contract on these facts

    The Revenue also argued that the turnkey supply and installation arrangement was a works contract because the SPG systems were installed on civil foundations and therefore became immovable property.

    The Court disagreed. It distinguished between a composite supply and a works contract:

    • A composite supply may include goods and services supplied together.
    • A works contract is a narrower category that requires work relating to an immovable property end product.

    The Court found that the solar panels and related SPG components could be detached from their foundations and used elsewhere. Their attachment was intended to provide stability and enable efficient operation, not to create a permanent addition to the land or to improve the beneficial enjoyment of the foundation.

    Applying established tests on annexation, intention, functionality, permanency and marketability, the Court held that such SPG systems remained movable property. The presence of limited civil work in the EPC contract did not, by itself, convert the transaction into a works contract.

    Extended limitation and penalty could not stand

    The department had alleged wilful misstatement and suppression of facts, invoking the extended limitation period and imposing penalties. The Court found this unsustainable.

    Because the 70:30 valuation model came into force only on 1 January 2019, the taxpayer could not be accused of suppressing facts or misrepresenting its tax position by not applying that later method to earlier transactions. The Court reiterated that allegations of fraud, wilful misstatement or suppression require clear foundational facts; merely using those labels is insufficient.

    Outcome and business significance

    The Supreme Court set aside the tax order dated 17 January 2025 and the consequential summary order dated 24 January 2025. Each party was directed to bear its own costs.

    The ruling provides important clarity for renewable-energy EPC contracts executed before 1 January 2019:

    • The 70:30 goods-services valuation formula cannot be compulsorily applied to that earlier period.
    • A 2021 clarification gave taxpayers an option to adopt the formula; it did not impose a retroactive obligation.
    • Installation on a foundation does not alone make a solar generating system immovable property.
    • A solar EPC arrangement is not necessarily a works contract simply because it includes installation and civil-work elements.
    • Tax demands based on a retrospective application of the 70:30 method, including related extended-limitation allegations and penalties, lack legal support on these facts.

    The judgment reinforces a broader GST principle: tax classification and valuation must follow the legal regime applicable when the supply occurred, rather than a later framework retroactively imposed by the authorities.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

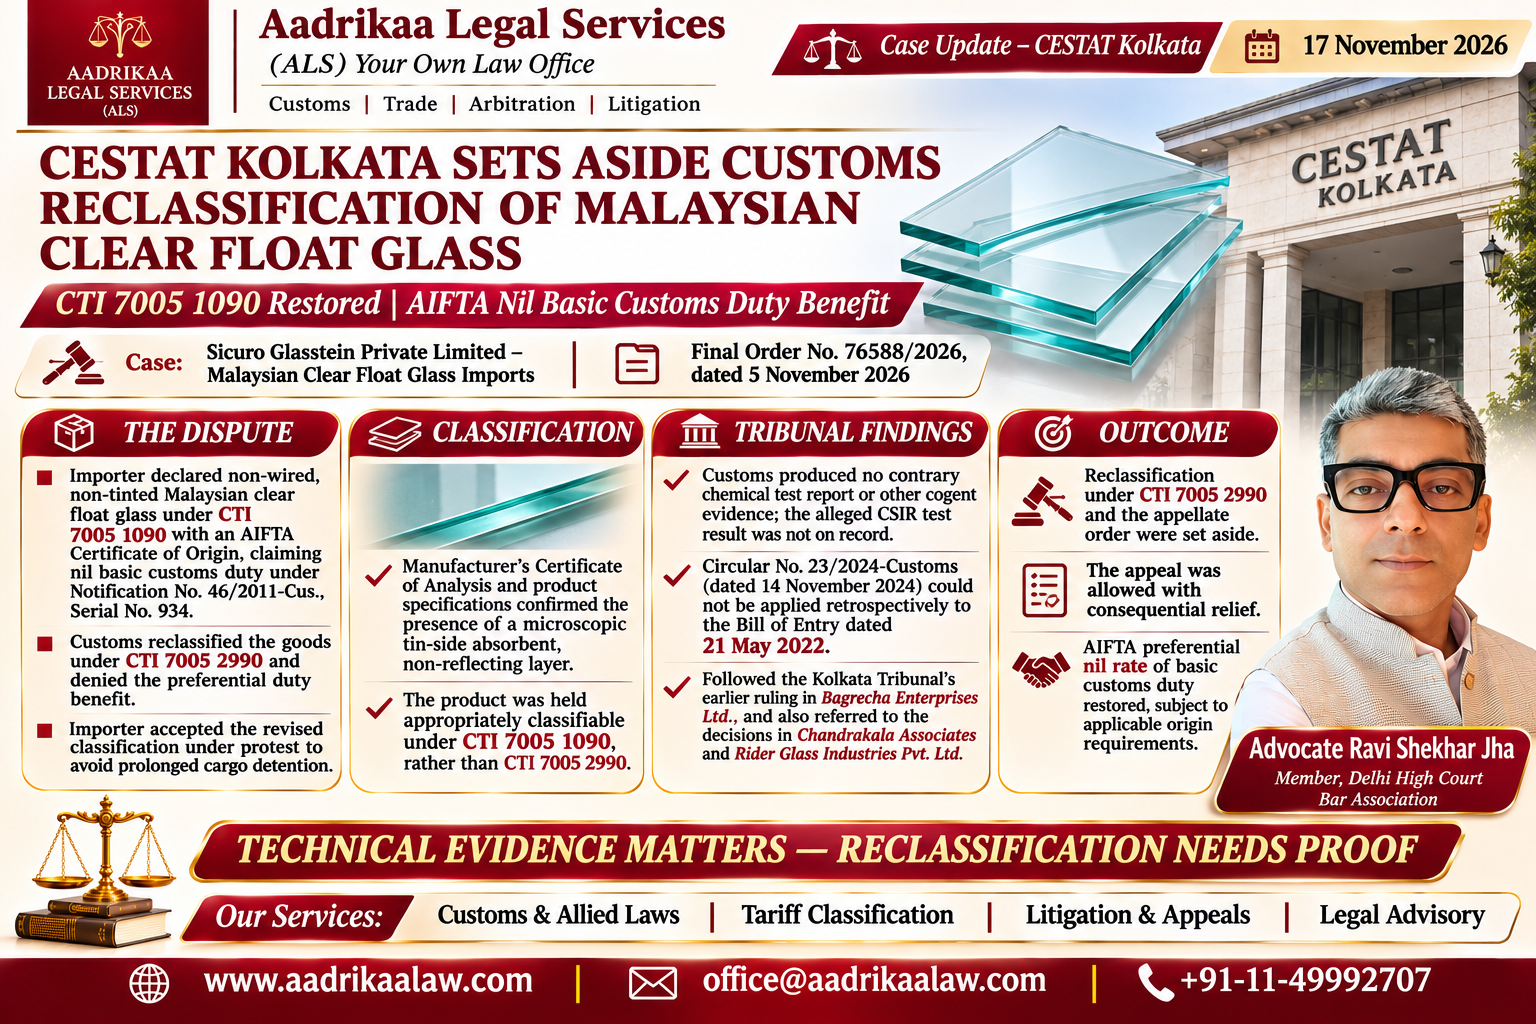
  • CESTAT Kolkata Sets Aside Customs Reclassification of Malaysian Clear Float Glass Imports

    CESTAT Kolkata Sets Aside Customs Reclassification of Malaysian Clear Float Glass Imports

    Date: 17.11.2026

    The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), Kolkata has held that Sicuro Glasstein Private Limited’s imported clear float glass is correctly classifiable under Customs Tariff Item 7005 1090, restoring its eligibility for a nil basic customs duty rate under the ASEAN-India Free Trade Agreement (AIFTA).

    Background of the dispute

    Sicuro Glasstein Private Limited imported clear float glass of different thicknesses and lengths from Malaysia. The consignment, supplied by Kibing Group (M) Sdn. Bhd., was declared under Customs Tariff Item 7005 1090. The importer also claimed preferential nil-rate basic customs duty under Serial No. 934 of Notification No. 46/2011-Cus., relying on a valid AIFTA Certificate of Origin.

    During faceless assessment, Customs questioned whether the glass was tinted, wired, or carried an absorbent or reflecting layer other than on its tin side. Although the importer submitted an analysis report and technical documents, the assessing authority proposed a different classification under Customs Tariff Item 7005 2990.

    To prevent prolonged cargo detention, the importer accepted the revised classification under protest. Customs then denied the AIFTA duty concession. The Commissioner of Customs (Appeals), Kolkata upheld that decision, prompting the company to appeal before CESTAT.

    The central classification issue

    The case turned on whether clear float glass produced through the float process, with a microscopic tin layer on one surface, could be treated as non-wired glass having an absorbent, non-reflecting layer under tariff item 7005 1090.

    The importer maintained that the glass was non-wired and non-tinted, and that the tin-side layer created during manufacture qualified as an absorbent layer. Customs, however, had reclassified the goods under tariff item 7005 2990, which resulted in the loss of preferential duty treatment.

    Tribunal’s findings

    CESTAT found that the manufacturer’s Certificate of Analysis described the product as non-wired glass with an absorbent, non-reflecting layer. The supplier’s product specifications also established the presence of a tin coating on the bottom surface of the glass.

    Crucially, the Tribunal noted that Customs had not produced any chemical test report or other cogent evidence contradicting the manufacturer’s specifications. Although the appellate order referred to samples allegedly sent to CSIR, Kolkata for testing, the result of that test was not on record.

    In the absence of contrary evidence, the Tribunal accepted the factual characteristics stated by the manufacturer and held that the imported product should be classified under Customs Tariff Item 7005 1090.

    Why the 2024 Customs circular did not apply

    Revenue relied on Circular No. 23/2024-Customs, dated 14 November 2024, to argue that a tin coating should not determine classification under Heading 7005 10. CESTAT rejected that argument for this import because the Bill of Entry was filed on 21 May 2022.

    The Tribunal held that the later circular could not be applied retrospectively to an import that had taken place before the circular was issued.

    Reliance on established precedent

    The Tribunal observed that earlier decisions had consistently recognized that the microscopic tin layer produced in the molten-tin float process can function as an absorbent layer for tariff-classification purposes.

    It specifically followed the Kolkata Tribunal’s earlier ruling in Bagrecha Enterprises Ltd., which involved clear float glass imported from the same Malaysian supplier. In that decision, the Tribunal held that clear float glass with a microscopic tin layer was properly classifiable under tariff item 7005 1090. It also noted that Indian manufacturers of identical clear float glass had been clearing such goods under the same tariff item.

    CESTAT also referred to decisions in Chandrakala Associates and Rider Glass Industries Pvt. Ltd., which supported classification of qualifying clear float glass under tariff item 7005 1090.

    Outcome and practical significance

    By Final Order No. 76588/2026, dated 5 November 2026, CESTAT set aside the reclassification under Customs Tariff Item 7005 2990 and the related appellate order. The appeal was allowed with consequential relief in accordance with law.

    The decision confirms that, for the import in question, clear float glass that is non-wired and has an absorbent, non-reflecting tin-side layer falls under Customs Tariff Item 7005 1090. As a result, Sicuro Glasstein was entitled to the AIFTA preferential nil rate of basic customs duty under Notification No. 46/2011-Cus., subject to the applicable origin requirements.

    For importers, the ruling underscores the value of maintaining strong manufacturer-issued technical documentation, including certificates of analysis and product specifications. It also demonstrates that a customs reclassification requires evidentiary support, particularly where the importer’s technical evidence remains unrebutted.

    Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.

    Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.

    Handy Download:

    Ravi Shekhar Jha – Advocate, Bar Council of Delhi