

Aadrikaa Legal Services (ALS)- Law I Litigation I Arbitration
Date: 17.11.2026
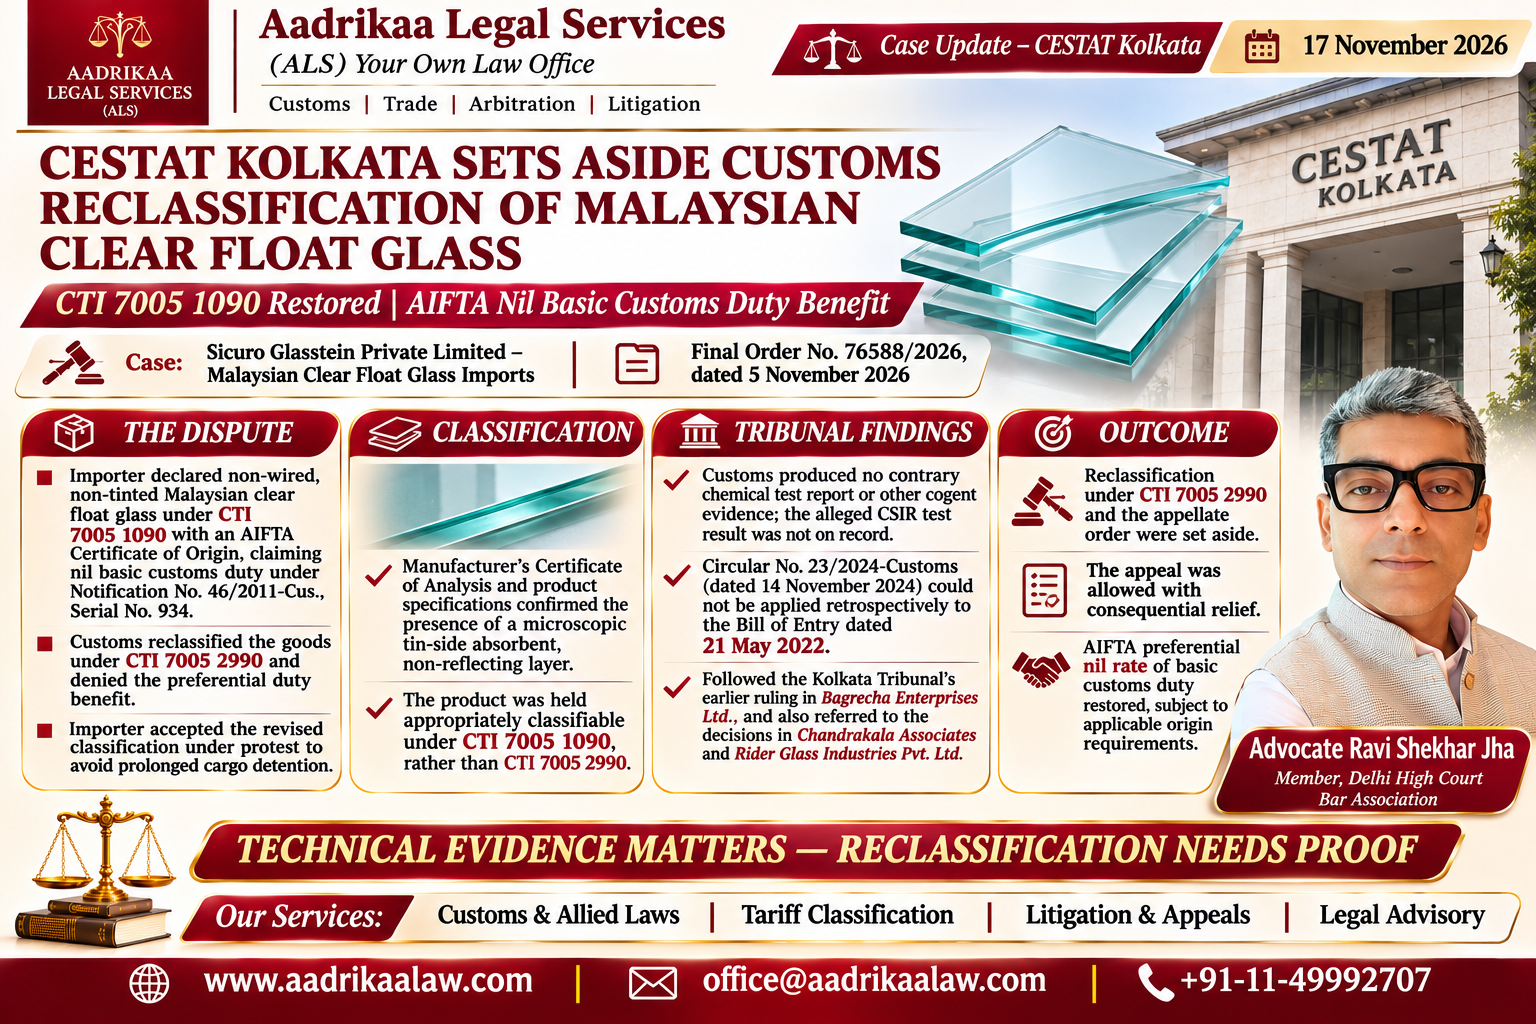
CESTAT Kolkata Sets Aside Customs Reclassification of Malaysian Clear Float Glass Imports

This Short Article has been prepared & written by Advocate Ravi Shekhar Jha-Delhi High Court, New Delhi. The views expressed are based on his interpretation of the law. He can be reached at his email id intelconsul@gmail.com .
The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), Kolkata has held that Sicuro Glasstein Private Limited’s imported clear float glass is correctly classifiable under Customs Tariff Item 7005 1090, restoring its eligibility for a nil basic customs duty rate under the ASEAN-India Free Trade Agreement (AIFTA).
Background of the dispute
Sicuro Glasstein Private Limited imported clear float glass of different thicknesses and lengths from Malaysia. The consignment, supplied by Kibing Group (M) Sdn. Bhd., was declared under Customs Tariff Item 7005 1090. The importer also claimed preferential nil-rate basic customs duty under Serial No. 934 of Notification No. 46/2011-Cus., relying on a valid AIFTA Certificate of Origin.
During faceless assessment, Customs questioned whether the glass was tinted, wired, or carried an absorbent or reflecting layer other than on its tin side. Although the importer submitted an analysis report and technical documents, the assessing authority proposed a different classification under Customs Tariff Item 7005 2990.
To prevent prolonged cargo detention, the importer accepted the revised classification under protest. Customs then denied the AIFTA duty concession. The Commissioner of Customs (Appeals), Kolkata upheld that decision, prompting the company to appeal before CESTAT.
The central classification issue
The case turned on whether clear float glass produced through the float process, with a microscopic tin layer on one surface, could be treated as non-wired glass having an absorbent, non-reflecting layer under tariff item 7005 1090.
The importer maintained that the glass was non-wired and non-tinted, and that the tin-side layer created during manufacture qualified as an absorbent layer. Customs, however, had reclassified the goods under tariff item 7005 2990, which resulted in the loss of preferential duty treatment.
Tribunal’s findings
CESTAT found that the manufacturer’s Certificate of Analysis described the product as non-wired glass with an absorbent, non-reflecting layer. The supplier’s product specifications also established the presence of a tin coating on the bottom surface of the glass.
Crucially, the Tribunal noted that Customs had not produced any chemical test report or other cogent evidence contradicting the manufacturer’s specifications. Although the appellate order referred to samples allegedly sent to CSIR, Kolkata for testing, the result of that test was not on record.
In the absence of contrary evidence, the Tribunal accepted the factual characteristics stated by the manufacturer and held that the imported product should be classified under Customs Tariff Item 7005 1090.
Why the 2024 Customs circular did not apply
Revenue relied on Circular No. 23/2024-Customs, dated 14 November 2024, to argue that a tin coating should not determine classification under Heading 7005 10. CESTAT rejected that argument for this import because the Bill of Entry was filed on 21 May 2022.
The Tribunal held that the later circular could not be applied retrospectively to an import that had taken place before the circular was issued.
Reliance on established precedent
The Tribunal observed that earlier decisions had consistently recognized that the microscopic tin layer produced in the molten-tin float process can function as an absorbent layer for tariff-classification purposes.
It specifically followed the Kolkata Tribunal’s earlier ruling in Bagrecha Enterprises Ltd., which involved clear float glass imported from the same Malaysian supplier. In that decision, the Tribunal held that clear float glass with a microscopic tin layer was properly classifiable under tariff item 7005 1090. It also noted that Indian manufacturers of identical clear float glass had been clearing such goods under the same tariff item.
CESTAT also referred to decisions in Chandrakala Associates and Rider Glass Industries Pvt. Ltd., which supported classification of qualifying clear float glass under tariff item 7005 1090.
Outcome and practical significance
By Final Order No. 76588/2026, dated 5 November 2026, CESTAT set aside the reclassification under Customs Tariff Item 7005 2990 and the related appellate order. The appeal was allowed with consequential relief in accordance with law.
The decision confirms that, for the import in question, clear float glass that is non-wired and has an absorbent, non-reflecting tin-side layer falls under Customs Tariff Item 7005 1090. As a result, Sicuro Glasstein was entitled to the AIFTA preferential nil rate of basic customs duty under Notification No. 46/2011-Cus., subject to the applicable origin requirements.
For importers, the ruling underscores the value of maintaining strong manufacturer-issued technical documentation, including certificates of analysis and product specifications. It also demonstrates that a customs reclassification requires evidentiary support, particularly where the importer’s technical evidence remains unrebutted.
Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.
Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.
Source: CESTAT Kolkata
Handy Download:
Write to us at office@aadrikaalaw.com
Tel: +91-11-4999 2707
Ravi Shekhar Jha – Advocate, Bar Council of Delhi
Leave a Reply