

Aadrikaa Legal Services (ALS)- Law I Litigation I Arbitration
Date: 20.11.2026
CESTAT Kolkata Rejects Customs Department’s Reclassification of Usha Martin’s MCB Imports

This Short Article has been prepared & written by Advocate Ravi Shekhar Jha-Delhi High Court, New Delhi. The views expressed are based on his interpretation of the law. He can be reached at his email id intelconsul@gmail.com .
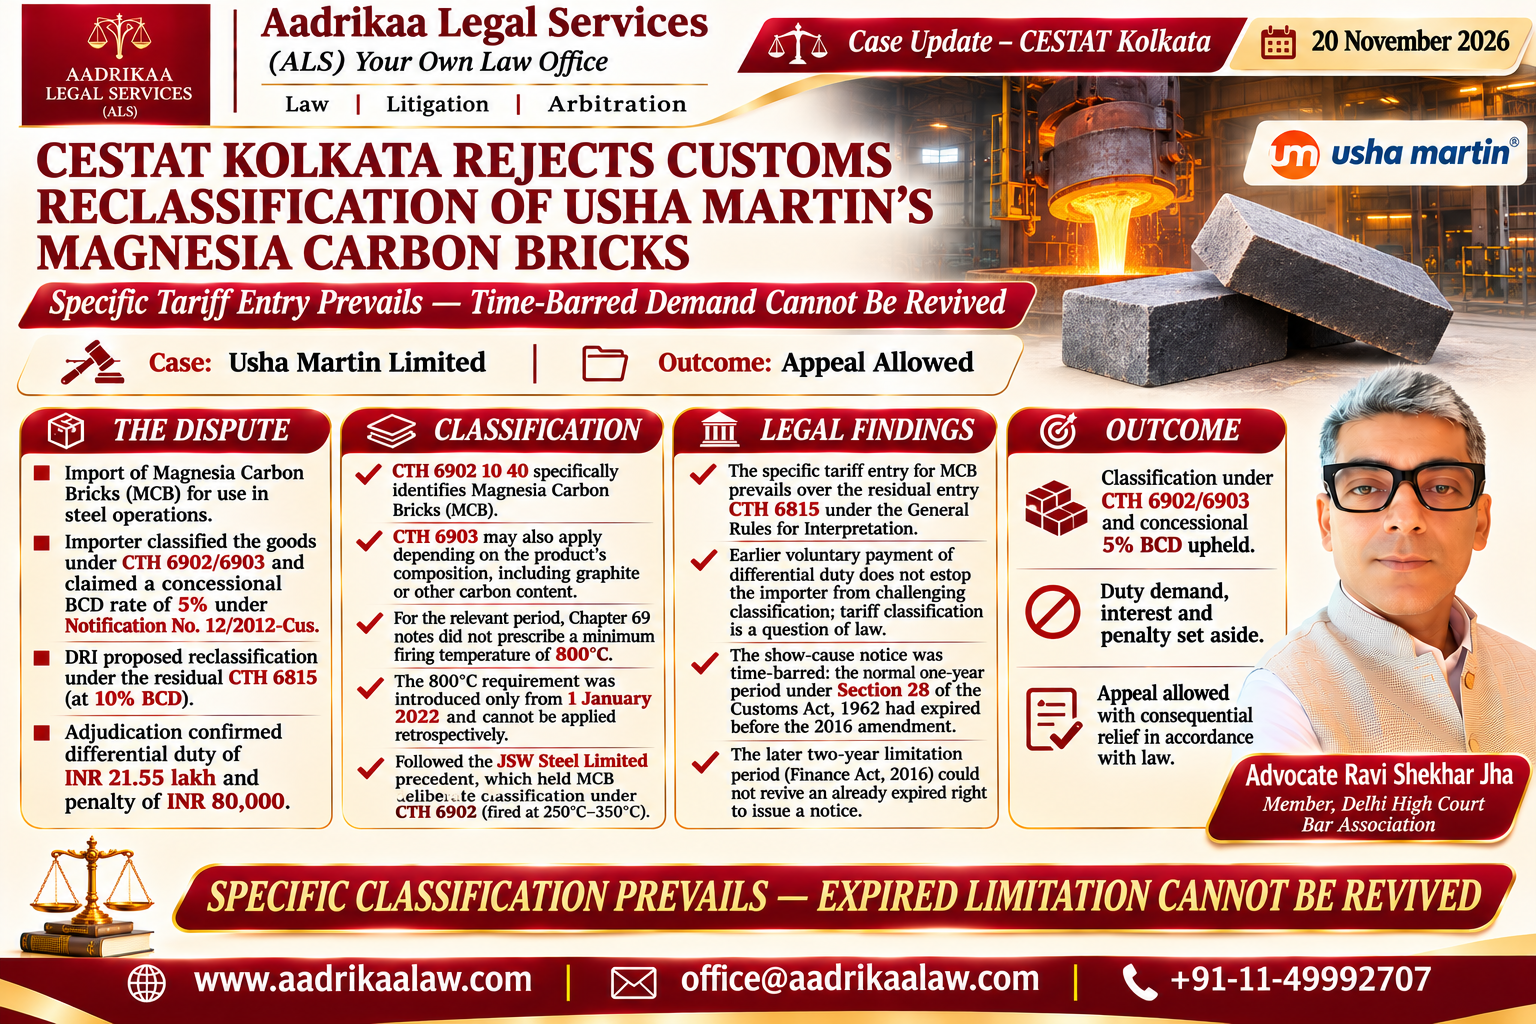
The Customs, Excise and Service Tax Appellate Tribunal (CESTAT), Kolkata has allowed Usha Martin Limited’s appeal, holding that its imported Magnesia Carbon Bricks (MCB) were correctly classified under Customs Tariff Headings (CTH) 6902/6903—not the residual heading 6815—and that the related customs-duty demand, interest and penalty could not stand.
Background of the dispute
Usha Martin, a manufacturer of iron and steel products including wire ropes, strands and steel wires, imported MCB from overseas suppliers for use in its operations. The company classified the goods under CTH 6902/6903 and claimed a concessional basic customs duty (BCD) rate of 5% under Notification No. 12/2012-Cus.
The Directorate of Revenue Intelligence (DRI) disputed this treatment. It alleged that the MCB should instead fall under CTH 6815, which attracted BCD at 10%, and sought differential duty, interest, confiscation and penalty.
Although Usha Martin had earlier paid differential duty of INR 1.83 crore and interest of about INR 19.05 lakh for imports made between November 2014 and October 2015, it maintained that the payment was made to buy peace and without conceding the classification issue. The department initially closed the proceedings, but later revived them and issued a show-cause notice for an earlier period.
The original adjudication order confirmed differential duty of INR 21.55 lakh, with interest, and imposed a penalty of INR 80,000. Usha Martin challenged that order before CESTAT.
Tribunal’s ruling on classification
The central issue was whether MCB should be classified as refractory ceramic goods under Chapter 69 or as articles of stone or other mineral substances under Chapter 68.
CESTAT found that the tariff specifically identifies Magnesia Carbon Bricks under CTH 6902 10 40. It also noted that CTH 6903 can apply depending on the product’s composition, including graphite or other carbon content. In contrast, CTH 6815 is a broader residual category.
The department’s case was based on the view that products under Chapter 69 had to be fired after shaping at a minimum temperature of 800°C. Since the imported bricks were reportedly fired only up to 350°C, it argued that they could not be classified under Chapter 69.
The Tribunal rejected this reasoning for three key reasons:
- No 800°C condition in the applicable tariff note: During the period of import, Chapter Note 1 to Chapter 69 did not prescribe a minimum firing temperature.
- Chapter 69 headings 6901 to 6903 were treated differently: The firing requirement relied upon by the department did not displace classification of refractory products under headings 6901 to 6903.
- Specific entry overrides residual entry: Under the General Rules for Interpretation, the specific tariff entry for Magnesia Carbon Bricks prevails over the general, residuary entry in CTH 6815.
The Tribunal followed its earlier decision in JSW Steel Limited v. Additional Director General, DRI, where MCB fired at 250°C to 350°C had been held classifiable under CTH 6902. It observed that the 800°C requirement was introduced only from 1 January 2022 and could not be applied retrospectively to earlier imports.
Earlier payment did not prevent Usha Martin from contesting classification
The department argued that Usha Martin’s earlier voluntary payment of differential duty meant it could not subsequently dispute classification under CTH 6815.
CESTAT disagreed. It held that tariff classification is a question of law that must be decided from the objective characteristics, composition and function of the goods in each case. A prior payment or earlier classification position does not create an estoppel in tax matters.
The Tribunal relied on the established principle that res judicata and estoppel do not operate in the same way in taxation because each assessment period creates a separate cause of action. As a result, Usha Martin was entitled to challenge the department’s proposed classification despite its earlier payment.
Demand was also barred by limitation
CESTAT separately held that the show-cause notice was time-barred.
Before the 2016 amendment, Section 28 of the Customs Act allowed the department one year to issue a notice in cases without an allegation of fraud, collusion or wilful misstatement. For the relevant imports, that period had expired by 30 October 2015.
The Finance Act, 2016 later extended the normal limitation period from one year to two years, effective from 14 May 2016. The department sought to rely on that amendment when issuing the show-cause notice in September 2016.
The Tribunal held that a later amendment cannot revive a right to issue a notice if that right had already expired under the law in force at the time. Accordingly, the extended two-year period could not be applied to revive a time-barred demand.
Outcome and significance
CESTAT set aside the original adjudication order in full and allowed Usha Martin’s appeal with consequential relief in accordance with law. The Tribunal:
- confirmed that the imported MCB were appropriately classifiable under CTH 6902/6903;
- upheld Usha Martin’s eligibility for the 5% concessional BCD rate;
- cancelled the customs-duty demand and related interest;
- set aside the INR 80,000 penalty; and
- ruled that the department could not revive an already time-barred demand through the 2016 limitation amendment.
The decision reinforces two important customs-law principles: a specific tariff entry for a product must prevail over a residual classification, and an extension of a statutory limitation period cannot reopen demands that had already become time-barred before the amendment took effect.
Listen to this on our #YouTube Channel
Aadrikaa Legal Services is a trusted legal and regulatory support partner providing end-to-end legal solutions to law firms, corporate organizations, and businesses across India. We specialize in paralegal services, litigation support, tax and regulatory matters, delivering reliable, efficient, and result-oriented legal assistance.
Our services include comprehensive paralegal support, drafting and documentation, legal research, case management, litigation handling, and representation support across various judicial and quasi-judicial forums. We also assist in direct and indirect tax matters, customs, GST, corporate regulatory compliance, and legal advisory.
Source: CESTAT Kolkata
Handy Download:
Write to us at office@aadrikaalaw.com
Tel: +91-11-4999 2707
Ravi Shekhar Jha – Advocate, Bar Council of Delhi
Leave a Reply